Decoding 2026 Mortgage Rate Forecasts for Home Loan Decisions
Decoding 2026 mortgage rate forecasts for home loan decisions helps you stress-test your budget and choose the right time to lock or float.
By Hannah Carter
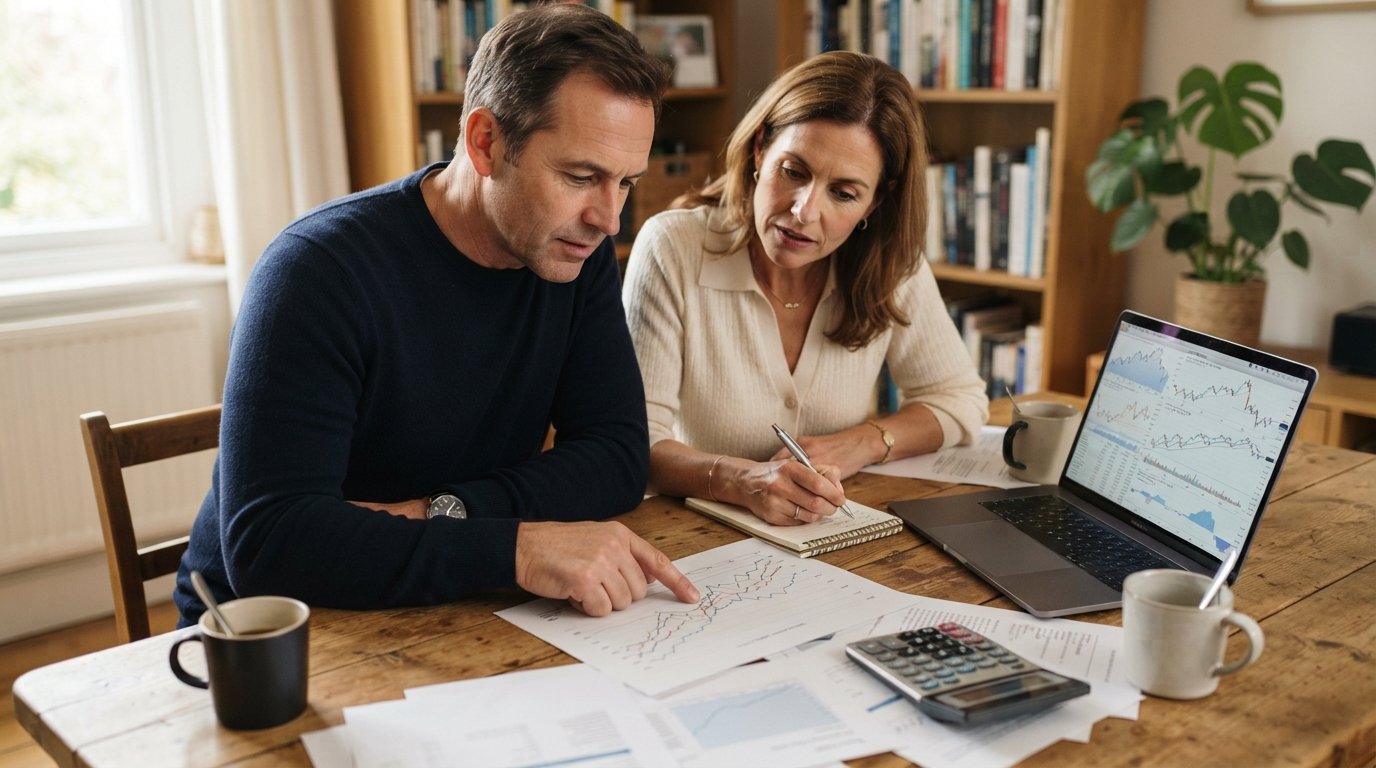
Mortgage rates in 2026 will not be decided by a single headline or a single Fed meeting. They will emerge from a tug-of-war between inflation data, Federal Reserve policy, Treasury yields, and the collective expectations of bond investors. If you are planning to buy a home or refinance in the next 12 to 18 months, the temptation is to wait for a clear signal. But forecasts rarely offer certainty; they offer ranges, probabilities, and shifting narratives. The better approach is to decode what the forecasts actually say, understand the inputs behind them, and map those scenarios onto your own financial tolerances. This guide breaks down the forces that shape 2026 mortgage rate projections, explains why experts disagree, and shows you how to turn a range of possible outcomes into a practical home loan decision.
The Economic Inputs That Drive Mortgage Rate Forecasts
Mortgage rates are not set by the Federal Reserve directly. They are influenced by the yield on the 10-year Treasury note, which moves in response to inflation expectations, Fed policy signals, and global demand for safe assets. When inflation runs hot, bond investors demand higher yields to protect purchasing power, and mortgage rates tend to follow. When inflation cools, yields often fall, pulling mortgage rates lower. The Fed's policy rate, the federal funds rate, affects short-term borrowing costs and shapes market expectations about future inflation, but the 10-year Treasury is the more direct benchmark for 30-year fixed mortgage rates. Understanding this chain is the first step in decoding any 2026 forecast.
The second input is the labor market. A tight job market with rising wages can sustain inflation, keeping upward pressure on rates. A cooling labor market can signal slower growth and lower inflation, which may push rates down. Forecasters watch monthly jobs reports, wage growth, and unemployment claims closely. The third input is global economic conditions. International demand for U.S. Treasuries, currency movements, and geopolitical uncertainty can all influence yields. When global investors seek safety, they buy Treasuries, which can lower yields and mortgage rates. When they sell, rates can rise. No single data point tells the whole story; forecasts are built on a combination of these forces.
Why 2026 Mortgage Rate Forecasts Diverge
If you read three different forecasts for 2026 mortgage rates, you will likely see three different numbers. One might predict the 30-year fixed rate averaging 6.2%, another 6.8%, and a third somewhere in between. This divergence is not a sign that forecasters are incompetent; it reflects genuine uncertainty about inflation, Fed policy, and economic growth. Each forecast is built on a set of assumptions. One may assume the Fed cuts rates twice in 2026, another may assume one cut, and a third may assume no cuts. Small differences in assumptions produce meaningful differences in projected rates. The lesson is to read forecasts as ranges and scenarios, not as point estimates you can bank on.
Another reason forecasts diverge is timing. A forecast published in early 2026 may be outdated by mid-year if inflation surprises or the Fed changes course. Mortgage rates are forward-looking, meaning they price in expectations about the future. When new data arrives, those expectations shift, and rates move. This is why a forecast that was accurate in January may be irrelevant by June. Instead of anchoring to a single number, ask what assumptions drive the forecast and how likely those assumptions are to hold. A forecast that clearly states its assumptions is more useful than one that offers a precise number without context.
How to Read Rate Ranges and Scenarios
A well-constructed forecast usually presents a base case, a more optimistic case, and a more pessimistic case. The base case reflects the most likely path based on current data. The optimistic case might assume faster disinflation and more Fed cuts, leading to lower rates. The pessimistic case might assume sticky inflation and fewer cuts, leading to higher rates. Your job is not to predict which case will happen but to assess how each case would affect your home loan decision. If you are buying a home, a higher-rate scenario might stretch your budget; a lower-rate scenario might make waiting worthwhile. If you are refinancing, a higher-rate scenario might delay your break-even point; a lower-rate scenario might accelerate it.
To make this concrete, consider a hypothetical borrower considering a $400,000 30-year fixed mortgage. At 6.0%, the principal and interest payment is roughly $2,398 per month. At 6.5%, it rises to about $2,528. At 7.0%, it climbs to roughly $2,661. These illustrative figures show how a half-point difference in rate translates to real monthly cash flow. If your budget can comfortably absorb the higher end of the forecast range, you have flexibility. If it cannot, you may need to adjust your price target, save a larger down payment, or consider an adjustable-rate mortgage. The point is to use the forecast range to stress-test your budget, not to wait for a perfect rate that may never arrive.
Floating Versus Locking: Matching Strategy to Risk Tolerance
Once you have a loan application in process, you will face a choice: lock your rate or float it. Locking protects you from rate increases during the lock period, usually 30 to 60 days, but you give up the chance to benefit from rate decreases. Floating means you keep your rate open to market movements; you might get a lower rate if rates fall, but you risk a higher rate if they rise. The right choice depends on your risk tolerance, your timeline, and your view of the forecast. If you are closing soon and a higher rate would jeopardize your budget, locking is the safer path. If you have time and can tolerate uncertainty, floating might make sense, but only if you have a clear trigger for locking.
A common mistake is to float based on a forecast that rates will fall, without a plan for what happens if they rise. A more disciplined approach is to set a target rate and a stop-loss rate. For example, you might decide to lock if rates hit 6.25% or if they rise to 6.75%, whichever comes first. This removes emotion from the decision and ties it to your financial plan. Another option is a float-down lock, which lets you lock now but take advantage of a lower rate if rates drop before closing, usually for a fee. These products can be useful in volatile markets, but they are not free; compare the cost of the float-down feature against the potential savings.
It is also important to remember that the rate you see in forecasts is not necessarily the rate you will be offered. Your credit score, down payment, loan type, property type, and lender fees all affect your actual rate. A forecast for the average 30-year fixed rate is a benchmark, not a quote. To see how your specific profile translates into a rate, you can qualify for low interest mortgage rates by comparing offers from multiple lenders. The forecast tells you the direction of the market; your personal factors determine where you land within that market.
Illustrative Rate Scenarios and Practical Takeaways
To bring the forecast into focus, here are three illustrative scenarios for 2026 and what they might mean for a home loan decision. These are hypothetical examples for educational purposes only; they are not predictions or quotes. Actual rates will vary by lender and borrower and are subject to change.
- Scenario A: Rates drift lower. If inflation continues to cool and the Fed cuts rates modestly, the 30-year fixed rate might average in the low 6% range. In this scenario, buyers with flexible timelines might benefit from waiting, but refinancing could become attractive for homeowners with rates above 7%.
- Scenario B: Rates hold steady. If inflation remains near the Fed's target but does not fall further, rates might trade in a narrow band around 6.5%. In this scenario, timing the market offers little advantage; focus on your personal budget and choose a loan product that fits your long-term plans.
- Scenario C: Rates rise modestly. If inflation proves sticky or global demand for Treasuries weakens, rates could push toward 7% or higher. In this scenario, locking early and buying down points might make sense for buyers who need to close soon, while refinancing may be less attractive.
These scenarios are not exhaustive, and the actual path of rates will depend on data that has not yet arrived. The value of the exercise is to see how your decision changes across outcomes. If you would be comfortable in all three scenarios, you have a robust plan. If one scenario would strain your budget, you may need to adjust your price range, increase your down payment, or choose a different loan structure. For a deeper dive into how loan products work, MortgageDirectory offers plain-language guides on purchase loans, refinances, and home equity products, along with a payment calculator to help you estimate costs.
Translating Forecasts into Your Home Loan Decision
The final step is to connect the forecast to your specific situation. Start by defining your goal: are you buying a home, refinancing an existing mortgage, or accessing home equity? Each goal has a different sensitivity to rates. A home purchase is often driven by life circumstances, such as a growing family or a job relocation, so waiting for a lower rate may not be practical. A refinance is more rate-sensitive; you need a clear break-even point, the time it takes for monthly savings to exceed closing costs. A home equity loan or line of credit is tied to your home's value and your credit profile, and the rate you pay may be fixed or variable depending on the product.
Next, assess your risk tolerance and timeline. If you are closing in 60 days, you have limited ability to wait for a better rate; locking is likely the prudent choice. If you are planning to buy in 12 months, you have more flexibility, but you also face more uncertainty. Use the forecast range to set a target rate and a stop-loss rate, and stick to them. Avoid the trap of trying to time the market perfectly; even professional forecasters are often wrong. The goal is not to get the lowest possible rate but to get a rate that fits your budget and your long-term plans.
Finally, remember that a mortgage is a long-term commitment, and the rate is only one part of the equation. Closing costs, loan terms, mortgage insurance, and prepayment penalties all affect the total cost of the loan. A slightly higher rate with lower fees may be cheaper than a lower rate with high fees. Compare loan estimates side by side, and ask lenders to explain any fees you do not understand. Use an interactive mortgage calculator to estimate your monthly payment and see how different rates and terms affect your budget. The more informed you are, the better equipped you will be to make a decision that serves your financial goals, regardless of where rates go in 2026.