Documents Needed for a Mortgage Application Checklist
A complete documents needed for a mortgage application checklist, from pay stubs and tax returns to gift letters, so underwriting moves faster.
By Alice Shaw
Your mortgage application can stall for weeks over a single missing bank statement. Lenders do not approve loans based on a quick conversation; they verify your income, assets, debts, and identity with paper trails that must line up exactly. Understanding which documents you need before you apply transforms a stressful scavenger hunt into a simple filing exercise. This guide walks through every category of paperwork a typical lender requests, explains why each item matters, and highlights the mistakes that send files back to the borrower instead of forward to underwriting.
Start With the Core: Income and Employment Documents
Every mortgage approval rests on one central question: can you repay the loan? Lenders answer that question by verifying your income through third-party records rather than trusting self-reported numbers. Salaried employees typically provide their two most recent pay stubs covering a 30-day period, W-2 forms for the past two years, and sometimes a written verification of employment that the lender sends directly to your employer. If you receive overtime, bonuses, or commissions, expect to document those separately because lenders average variable income over time and need a history to calculate it reliably.
Self-employed borrowers face a higher documentation bar. Lenders usually ask for two years of personal tax returns with all schedules, two years of business tax returns if you own more than 25 percent of a company, a year-to-date profit and loss statement, and business bank statements. Some lenders also request a CPA letter confirming your business exists and your income continues. The extra paperwork exists because self-employment income is inherently variable, and underwriters need to see the trend, not just a single strong year.
Other income sources each have their own paper trail. Rental income requires lease agreements and tax returns showing the property. Social Security, pension, and disability income need award letters or benefit statements. Child support or alimony requires a divorce decree and proof of receipt. If you plan to use any of these to qualify, gather the documentation early because missing income records are one of the most common causes of conditional approvals that drag on for weeks.
Asset Statements and Down Payment Sourcing
Lenders verify that your down payment and closing costs come from legitimate, traceable sources. Expect to provide your two most recent statements for every asset account you plan to use: checking, savings, money market, certificates of deposit, retirement accounts, and brokerage accounts. The statements must show your name, the account number, and the balance, and they should be complete pages rather than screenshots of a mobile app. Large deposits that appear suddenly on a statement will trigger a request for explanation, so be ready to document any unusual inflows.
Gift funds are common, especially for first-time buyers, but they come with their own rules. If a family member is helping with your down payment, the lender will typically require a signed gift letter stating the amount, the donor's relationship to you, and confirmation that the funds are a gift rather than a loan. You will also need to show the transfer, usually a copy of the donor's check or a bank statement showing the deposit into your account. Some loan programs restrict how much of your down payment can come from gifts, so confirm the rules for your specific loan type before you finalize your numbers.
Down payment sourcing rules exist to prevent borrowed funds from quietly increasing your debt load. If you sold a car, received a tax refund, or cashed out an investment, keep the paperwork that proves where the money came from. A short written explanation paired with a supporting document resolves most of these questions quickly. The same logic applies to closing costs: lenders want to see that you have reserves beyond the down payment, and they will verify those reserves with the same statement requirements.
Identification, Credit, and Legal Paperwork
Identity verification is straightforward but easy to overlook. You will need a government-issued photo ID, typically a driver's license or passport, and in some cases a second form of identification. Lenders also request your Social Security number for credit pulls and tax transcript verification. If you have changed your name, provide the marriage certificate or court order that connects your current name to the name on older documents. These small mismatches can hold up a file for days while an underwriter sorts out which version of you owns which account.
Credit documentation goes beyond the score itself. If you have a recent bankruptcy, foreclosure, or short sale, expect to provide the discharge papers, the trustee's final report, or the relevant court documents. Lenders want to see that the event is behind you and that you have re-established credit responsibly. If you are applying for a VA loan, you will need your Certificate of Eligibility, which you can obtain through the VA or sometimes through your lender. Divorced applicants should have the divorce decree available because it often determines support obligations and property interests that affect your qualification.
Property-related documents enter the picture once you have an accepted offer. For a purchase, you will provide the fully executed purchase contract, the earnest money deposit receipt, and any addenda. The lender will order an appraisal, but you may need to supply access instructions or a survey if one exists. For refinances, gather your current mortgage statement, your homeowner's insurance declaration page, and any HOA contact information. If you are using a mortgage application credit inquiry, remember that multiple lender pulls within a short window are typically treated as a single inquiry for scoring purposes, so shopping around does not have to damage your score.
Property, Insurance, and Later-Stage Documents
Some documents do not belong in the initial application but become essential as the loan moves toward closing. Homeowner's insurance is the clearest example: your lender will require a policy with coverage at least equal to the replacement cost of the home, and they need the declaration page showing the policy number, coverage amount, and mortgagee clause. Flood insurance may be required if the property sits in a designated flood zone, and condominium buyers often need the HOA master policy and the most recent budget or reserve study.
Title and closing documents round out the file. The title company will produce a title commitment, and any liens, easements, or ownership disputes must be resolved before closing. If you are purchasing new construction, expect builder contracts, specifications, and warranty documents. If the property is part of an estate or a trust, the lender will want the trust certification or letters testamentary. None of these items are glamorous, but each one protects the lender's collateral and, by extension, your ability to close on schedule.
One practical way to keep the later-stage paperwork from surprising you is to ask your loan officer for a full closing checklist at the start. A good lender will tell you upfront which insurance documents, HOA records, and title items will be requested. You can then gather them in parallel with the income and asset paperwork instead of scrambling in the final week. Resources like LoanFinancing offer calculators and educational guides that help you estimate payments and understand how each document fits into the broader financing picture, which makes the checklist feel less like busywork and more like a map.
Common Paperwork Mistakes That Slow Underwriting
Most delays are self-inflicted, and they usually fall into a handful of predictable categories. The first is incomplete statements: lenders need every page of a bank statement, including the ones that show only the account summary or the disclosures. A missing page forces the underwriter to request the document again, and the clock restarts. The second is unexplained deposits. A $5,000 transfer from a friend or a cash deposit from a side job will trigger questions, so document the source before it becomes an issue.
The third mistake is inconsistent information across documents. Your name, address, and employer should match across your ID, pay stubs, tax returns, and application. A maiden name on an old W-2 or a former address on a bank statement is easy to explain, but only if you flag it proactively. The fourth mistake is waiting until the last minute to order tax transcripts or verification of employment, both of which are controlled by third parties and can take days to process. Start those requests as soon as your application is submitted.
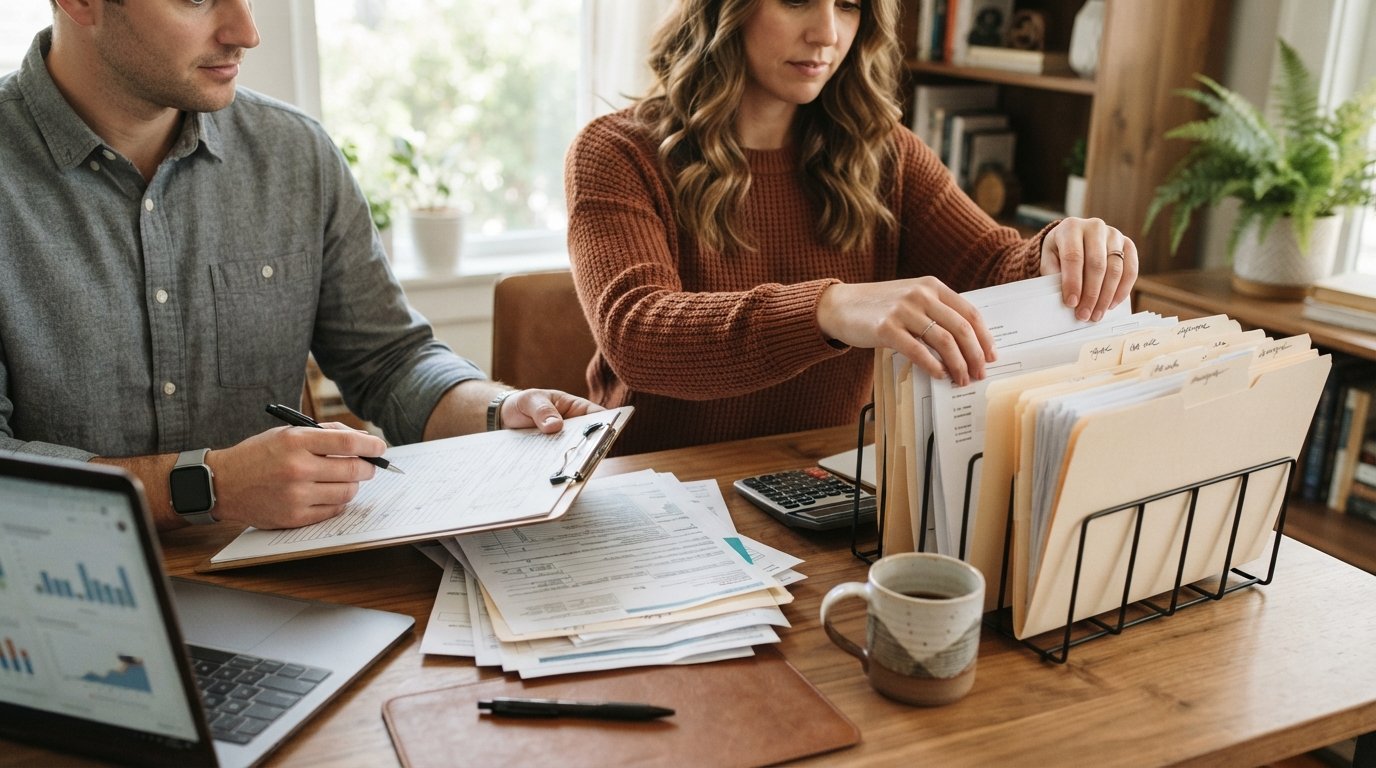
To avoid these pitfalls, build a simple tracking system before you apply. A folder for each category (income, assets, identity, property) with a checklist taped to the front works better than a shoebox of loose papers. Here is a short list of habits that keep files moving:
- Download complete statements directly from your bank rather than photographing them.
- Write a one-sentence explanation for any deposit that is not a regular paycheck.
- Confirm the exact document list with your loan officer in writing at the start.
- Submit documents in batches as you gather them instead of waiting for everything at once.
These habits matter because underwriting is a verification process, not a judgment process. When the paperwork is complete and consistent, the underwriter can approve the file quickly. When it is not, the file bounces back with conditions, and each round trip adds days to your closing timeline. Borrowers who treat documentation as part of the application rather than an afterthought consistently close faster and with fewer surprises.
Frequently Asked Questions About Mortgage Paperwork
How far back do lenders look at income and assets?
Most lenders review two years of income history and two months of asset statements. Self-employed borrowers and those with variable income should expect a deeper look, sometimes including a year-to-date profit and loss statement and business bank statements. The two-year window exists because lenders want to see stability, not just a single strong month.
Can I apply before I have every document ready?
Yes, and many borrowers do. You can start the application with your basic information and submit documents as you gather them. The key is to be honest about what is missing and to set a realistic timeline. A loan officer can often begin pre-approval with partial documentation, but final approval requires the full file.
What if a document is in a former name or a different address?
Provide a brief written explanation and a supporting document such as a marriage certificate, divorce decree, or utility bill. Lenders see name and address changes regularly, and a proactive note prevents the underwriter from treating the mismatch as a red flag.
Do I need to document gift funds even if the donor is my parent?
Yes. Gift funds require a signed gift letter and proof of transfer regardless of the relationship. The lender needs to confirm the money is a gift and not a loan, because a loan would change your debt-to-income ratio and potentially your qualification.
Gathering mortgage documents is tedious, but it is also one of the few parts of the home financing process entirely within your control. Start early, keep complete records, and communicate with your lender about anything unusual before it becomes a question. A well-organized file does more than satisfy underwriting; it gives you confidence that the numbers on your application reflect the reality the lender will verify, which is exactly the position you want to be in when you sign.