FHA 203k Loan for Home Renovation Financing: A Guide
The FHA 203k loan for home renovation financing combines purchase and repair costs into one mortgage, simplifying your fixer-upper project.
By Benjamin Griffin
Buying a fixer-upper can feel like a trade-off: you get a lower purchase price, but you also inherit a long list of repairs and upgrades that need cash. For many buyers, the biggest hurdle is not finding the right house, it is finding the money to make it livable. The FHA 203k loan for home renovation financing solves that problem by letting you borrow for both the purchase price and the renovation costs in a single mortgage. Instead of juggling a home loan, a contractor, and a separate construction loan, you get one closing, one monthly payment, and a clear path from worn-out property to move-in ready home.
This guide explains how the 203k program works, who qualifies, how the two main versions differ, and what to expect during the renovation process. It also compares the 203k with other ways to fund repairs, so you can decide whether this government-backed option fits your project and your budget.
What Is an FHA 203k Loan and How Does It Work?
The FHA 203k loan is a government-insured mortgage backed by the Federal Housing Administration. It allows borrowers to finance the purchase or refinance of a home plus the cost of renovations, repairs, and certain improvements in one loan. The loan amount is based on the projected value of the home after the work is complete, not just the current condition of the property. That feature is what makes the 203k so useful for buyers who want to purchase a distressed home but do not have a large reserve of cash for repairs.
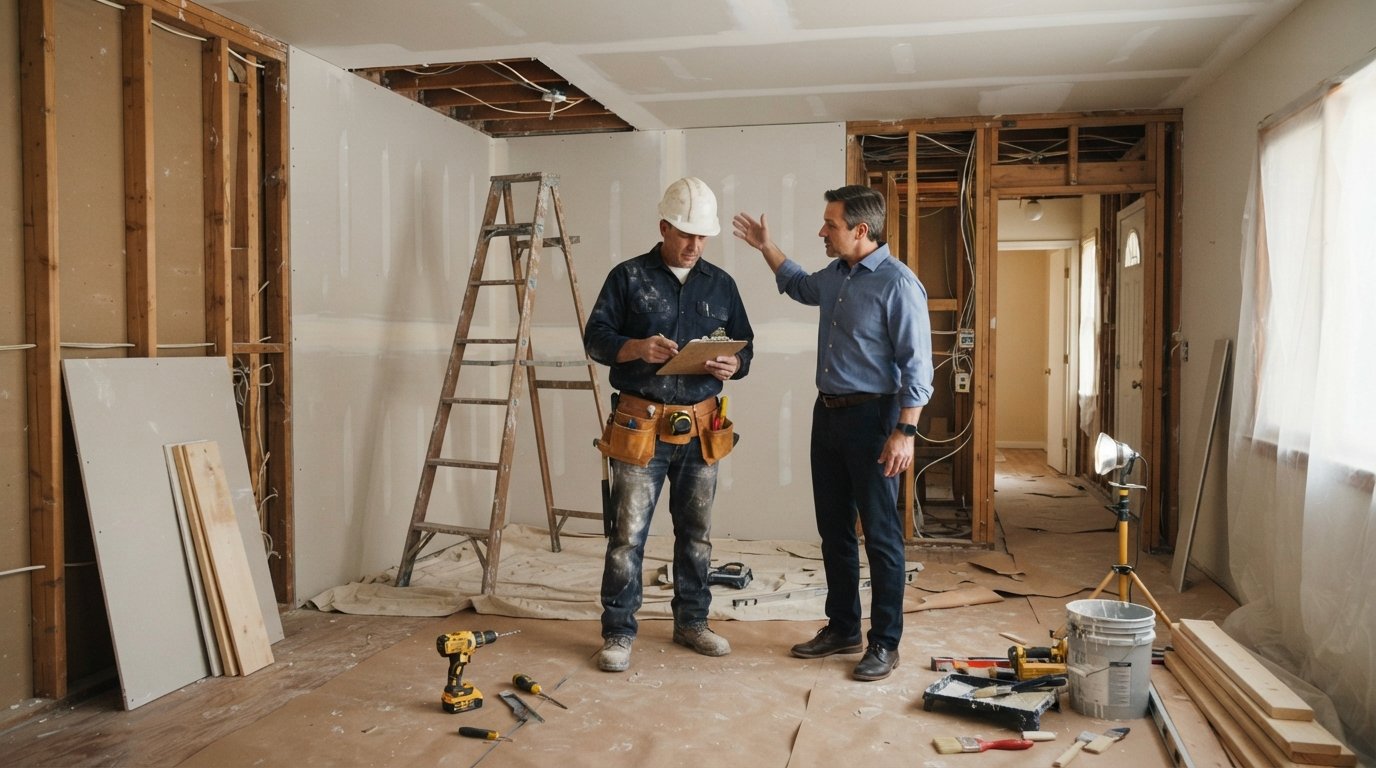
The program is available for single-family homes, and it can also be used for multi-unit properties with up to four units, as long as the borrower occupies one unit. Condominiums may qualify if they meet FHA approval standards. The renovation work must be completed by a licensed contractor, and the lender oversees the disbursement of funds through a draw process. This structure protects both the borrower and the lender by ensuring that money is released only as work is completed and inspected.
One of the most important things to understand is that the 203k is not a blank check. The lender will require a detailed proposal, contractor bids, and a feasibility study for larger projects. The appraised value after renovation must support the loan amount, and the borrower must meet FHA credit and income requirements. For buyers who are also exploring standard FHA financing, our guide on FHA mortgage loans for homeownership explains the baseline eligibility rules that apply to most FHA products.
Because the 203k is insured by the FHA, lenders can offer more flexible credit and down payment terms than they might for a conventional renovation loan. That flexibility is a major reason the program remains popular among first-time buyers and buyers with limited savings. It is also why the 203k is often described as a bridge between a home purchase loan and a construction loan.
Streamlined 203k vs. Standard 203k: Which One Fits Your Project?
The FHA 203k program comes in two main versions: the Streamlined 203k (often called the 203k Streamline) and the Standard 203k. The right choice depends on the scope, cost, and complexity of your renovation. Understanding the differences before you apply can save you time and help you avoid surprises during underwriting.
The Streamlined 203k is designed for smaller, non-structural projects. It is faster and less paperwork-intensive than the Standard version, which makes it attractive for buyers who want to update a kitchen, replace flooring, or make minor repairs. The Standard 203k is built for larger projects that involve structural changes, major systems, or extensive rehabilitation. It requires more documentation, including architectural plans and a feasibility study, but it also allows for much larger renovation budgets.
Here is a quick comparison of the two options:
- Streamlined 203k: Limited to projects with a total renovation cost of $35,000 or less (subject to change), no structural repairs, no major systems replacement, and a minimum of two contractor bids. The borrower can complete some cosmetic work themselves under certain conditions.
- Standard 203k: Allows renovation costs of $5,000 or more with no upper limit other than the FHA loan limit for the area. It permits structural changes, room additions, major plumbing and electrical work, and energy efficiency improvements. A HUD consultant is required to oversee the project.
- Eligibility differences: Both versions require owner-occupancy, a minimum credit score (typically 500 with 10% down or 580 with 3.5% down), and a debt-to-income ratio that meets FHA guidelines. The Standard 203k may require additional reserves and a higher level of documentation.
The Streamlined 203k is often the better choice for buyers who want to move quickly and keep the project manageable. The Standard 203k is the right fit for buyers who are purchasing a property that needs significant work, such as a full gut renovation or a structural repair. In either case, the lender will review the contractor bids and the scope of work to confirm that the project is eligible.
Contractor Bids, Draw Schedules, and Inspections
The renovation process under a 203k loan is more structured than a typical home improvement project. The lender and, for Standard 203k loans, a HUD consultant oversee the work to ensure that funds are used appropriately and that the project meets FHA standards. This oversight protects the borrower, but it also means the borrower needs to plan carefully and work with a contractor who is familiar with the 203k process.
The first step is submitting contractor bids. For a Streamlined 203k, the borrower typically needs at least two bids for the work. For a Standard 203k, the borrower needs a detailed proposal and a feasibility study, which is prepared by a HUD consultant. The bids must cover the full scope of work, including labor, materials, permits, and any required inspections. The lender will review the bids to ensure they are reasonable and that the total renovation cost fits within the program limits.
Once the loan is approved and the property is purchased, the renovation begins. Funds are released through a draw schedule, which is a series of payments tied to specific milestones in the project. The contractor completes a phase of work, the borrower and the lender (or HUD consultant) inspect the work, and then the funds for that phase are released. This process repeats until the project is complete. The draw schedule is a key protection for the borrower because it prevents the contractor from receiving full payment before the work is done.
Inspections are a required part of the process. For Standard 203k loans, the HUD consultant conducts inspections at key stages, and the lender may also require its own inspections. The borrower should expect to be involved in these inspections and should keep detailed records of all work and payments. A well-organized contractor who has experience with 203k loans can make this process much smoother.
Credit, Down Payment, and Owner-Occupancy Requirements
The FHA 203k loan for home renovation financing has specific credit, down payment, and occupancy requirements that borrowers must meet. These requirements are similar to other FHA loans but with a few additional considerations for the renovation component.
Credit score requirements vary by lender, but FHA guidelines allow borrowers with scores as low as 500 to qualify with a 10% down payment. Borrowers with scores of 580 or higher may qualify with a 3.5% down payment. The down payment is based on the total loan amount, which includes the purchase price and the renovation costs. Lenders may also have their own credit overlays, so it is important to check with multiple lenders to find the best fit.
Owner-occupancy is a strict requirement for the 203k program. The borrower must intend to live in the home as a primary residence. This requirement applies to both the Streamlined and Standard versions. Investors and buyers looking for rental properties are not eligible for the 203k, although they may consider other renovation financing options.
Debt-to-income ratio is another key factor. The lender will review the borrower's income, debts, and assets to ensure that the monthly mortgage payment (including taxes and insurance) is affordable. The 203k loan payment includes the renovation costs, so the borrower's DTI must account for the higher loan amount. Borrowers should get pre-approved before making an offer on a property to confirm their budget and avoid surprises.
Comparing 203k with Purchase Plus a Separate Home Improvement Loan
One of the most common questions buyers ask is whether they should use a 203k loan or purchase the home with a standard mortgage and then take out a separate home improvement loan. Both approaches can work, but they have different trade-offs in terms of cost, complexity, and risk.
With a 203k loan, the renovation costs are rolled into the first mortgage. That means one loan, one closing, and one monthly payment. The interest rate on the 203k is typically comparable to other FHA loans, and the borrower benefits from FHA insurance, which can make qualifying easier. The downside is that the 203k process is more involved than a standard purchase loan, with additional paperwork, contractor requirements, and inspections.
With a purchase plus a separate home improvement loan, the buyer gets a standard mortgage for the purchase and then applies for a second loan, such as a home equity loan, a HELOC, or a personal loan. This approach can be faster for the purchase itself, but it comes with higher costs and more risk. The second loan may have a higher interest rate, and the borrower must qualify for both loans separately. There is also the risk that the second loan is not approved or that the funds are not available when needed.
Here are the key differences to consider:
- Closing costs: A 203k loan involves one set of closing costs, while two separate loans mean two sets of closing costs.
- Interest rates: FHA 203k rates are often competitive, while home improvement loans and personal loans may carry higher rates.
- Qualification: The 203k uses FHA guidelines, which can be more flexible for borrowers with lower credit scores or smaller down payments.
- Timeline: The 203k process takes longer upfront but avoids the need to apply for a second loan after closing.
For buyers who are planning a major renovation and want the simplicity of a single loan, the 203k is often the better choice. For buyers who are making minor updates and have access to low-cost financing, a separate home improvement loan may be sufficient. It is also worth exploring personal loan and mortgage financing resources to compare rates and options before making a decision.
Is the FHA 203k Loan Right for Your Renovation?
The FHA 203k loan for home renovation financing is a powerful tool for buyers who want to purchase a home that needs work but do not have the cash to fund repairs separately. It combines the purchase and renovation into one loan, offers flexible credit and down payment requirements, and provides a structured process that protects the borrower and the lender. The program is particularly well-suited for first-time buyers, buyers with limited savings, and buyers who are purchasing a home in a neighborhood where renovated properties are in demand.
Before you apply, take time to understand the differences between the Streamlined and Standard versions, gather contractor bids, and get pre-approved with a lender that has experience with 203k loans. The process takes more planning than a standard mortgage, but the result, a home that is both affordable and move-in ready, can be well worth the effort. With the right preparation and the right team, the 203k can turn a fixer-upper into the home you have been looking for.