Financing Home Improvements With a HELOC: What to Know
A HELOC lets you draw only what you need for renovations and pay interest on that amount, keeping project costs flexible and affordable.
By Olivia White
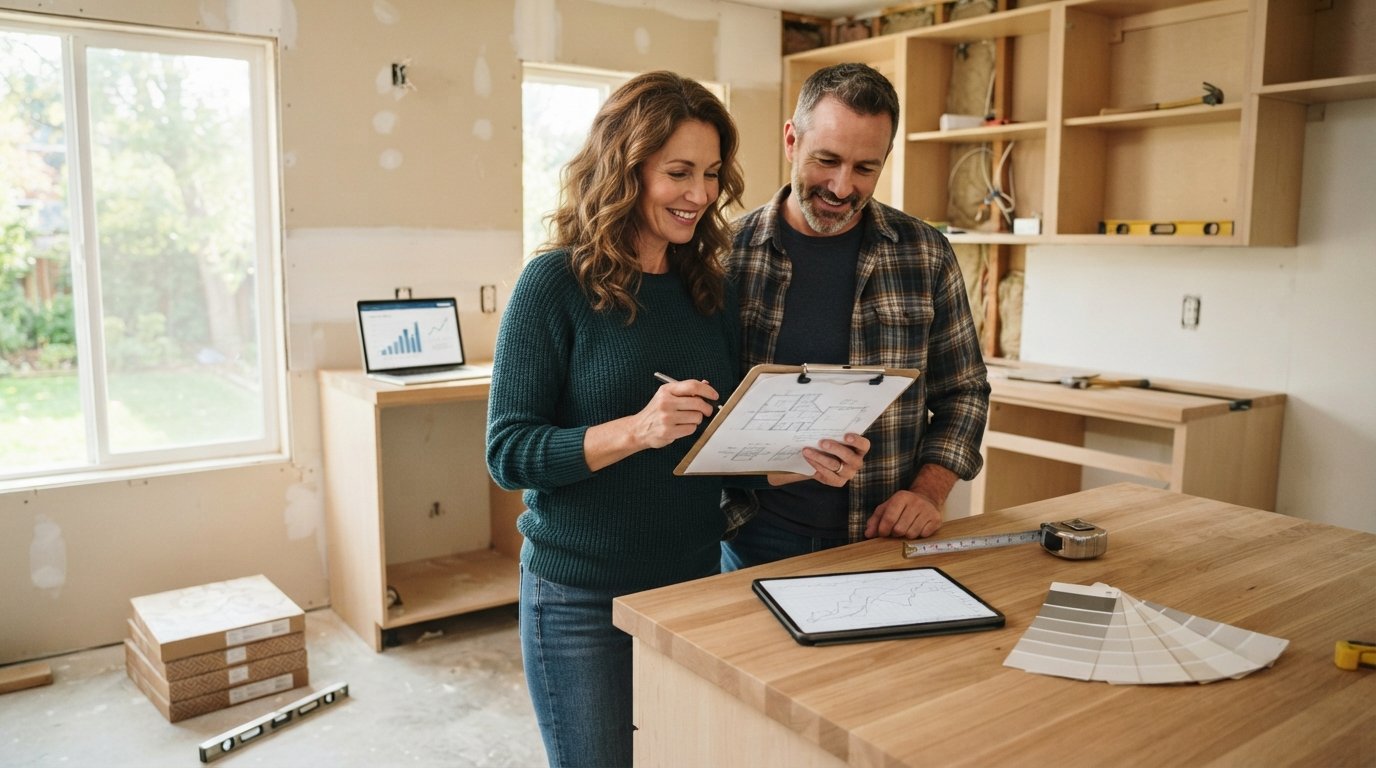
You have been staring at the same outdated kitchen for years, and you have finally decided to do something about it. The problem is that a major renovation can cost tens of thousands of dollars, and paying cash is not realistic for most households. That is where your home itself can become the funding source. Financing home improvements with a HELOC (a home equity line of credit) lets you borrow against the equity you have built up, often at a far lower rate than a credit card or personal loan. But it is not the right move for every project or every homeowner, and understanding the details before you apply can save you thousands.
How a HELOC Works and Why It Fits Renovation Projects
A HELOC is a revolving line of credit secured by your home. During the draw period, which typically lasts 10 years, you can borrow as much or as little as you need, up to your approved limit, and you only pay interest on what you actually use. When the draw period ends, the repayment period begins, and you make payments on both principal and interest, usually over 10 to 20 years.
What makes a HELOC distinct from a one-time home equity loan is its flexibility. Renovations rarely follow a perfect schedule. You may spend $8,000 on demolition and framing in month one, then wait weeks for cabinets to arrive before spending another $12,000. A lump-sum loan starts charging interest on the full amount immediately, while a HELOC only charges interest on the outstanding balance. That difference can add up to real savings on a project that unfolds over several months.
Rates on HELOCs are often variable, tied to the prime rate, though some lenders offer fixed-rate options or the ability to lock a portion of your balance. According to the Consumer Financial Protection Bureau and general market data, HELOC rates have historically been lower than unsecured personal loans and credit cards, though they can rise when the Federal Reserve adjusts rates. Your exact rate depends on your credit score, loan-to-value ratio, and the lender you choose.
Consider a homeowner with $80,000 in equity who wants to remodel a bathroom and add a home office. A contractor quotes $45,000. Instead of draining a savings account, the homeowner opens a HELOC for $50,000, draws $25,000 upfront, and draws the rest as work progresses. Interest accrues only on the drawn amount, and the remaining credit stays available for overruns.
Key Requirements and How to Qualify
Lenders evaluate HELOC applications much like they evaluate first mortgages. The two most important numbers are your credit score and your combined loan-to-value ratio (CLTV), which is the total of all loans secured by your home divided by its appraised value. Most lenders want a CLTV at or below 85%, though some allow up to 90% for well-qualified borrowers.
You will also need to document income, employment, and existing debts. Lenders calculate a debt-to-income ratio to confirm you can handle the new payment alongside your current obligations. A home appraisal or automated valuation is usually required to confirm your property value, and you should expect to pay closing costs that may range from a few hundred to over a thousand dollars, depending on the lender and loan size.
Here are the core requirements most lenders look for:
- Credit score of at least 620, with better rates typically starting around 700 or higher
- At least 15% to 20% equity in your home after the line is opened
- Debt-to-income ratio below 43%, though some lenders allow higher with compensating factors
- Proof of income, such as pay stubs, tax returns, or bank statements
- Homeowners insurance and, if required, flood insurance
If your credit score is borderline, spending a few months paying down balances and disputing errors on your report can improve your terms. If your equity is thin, waiting for home values to rise or making extra mortgage payments can help. The mortgage refinancing benefits guide explains how refinancing can sometimes lower your payments and free up cash flow, which may indirectly strengthen your HELOC application.
HELOC vs. Other Financing Options for Renovations
The renovation financing landscape includes several choices, and a HELOC is not automatically the winner. A cash-out refinance replaces your existing mortgage with a larger one and gives you the difference in cash. That can work well if you can secure a lower rate than your current mortgage, but you lose your original loan terms and pay closing costs similar to a full refinance.
A home equity loan provides a fixed lump sum with a fixed rate and fixed monthly payment. It is predictable and simple, but you start paying interest on the full amount right away. Personal loans and credit cards require no home equity and close quickly, but their interest rates are usually much higher, and large balances can damage your credit utilization ratio.
For a side-by-side comparison, consider these trade-offs:
- HELOC: Flexible draws, interest only on what you use, variable rates, ideal for phased projects
- Home equity loan: Fixed rate and payment, lump sum, better for one-time costs with a known total
- Cash-out refinance: Replaces first mortgage, potentially lower rate on the whole balance, higher closing costs
- Personal loan: No home equity required, fast funding, higher rates, shorter repayment terms
- Credit cards: Convenient for small purchases, very high rates, best avoided for large renovations
A HELOC tends to shine when the project scope is uncertain or when you want to keep your existing mortgage untouched. If you have a low fixed rate on your first mortgage, a cash-out refinance would mean giving that up, which is a significant cost. A HELOC sits in second position and preserves your primary loan.
That said, a HELOC carries risk because your home secures it. If you cannot repay, the lender can foreclose. Treat the line as seriously as your first mortgage, and avoid borrowing more than you can comfortably repay even if rates rise.
Smart Strategies for Using a HELOC on Renovations
How you manage the line matters as much as which product you choose. One of the most effective tactics is to draw funds in stages that match your contractor's payment schedule. Many contractors request a deposit, then payments at milestones. By timing draws to those milestones, you minimize the average outstanding balance and reduce interest charges.
Another strategy is to make interest-only payments during the draw period, but also to pay down principal whenever possible. Even small extra payments reduce the balance on which interest is calculated. If your lender allows, ask about locking a portion of your balance into a fixed-rate sub-account, which protects you from rate hikes on that portion while keeping the rest flexible.
Keep every receipt and invoice related to the renovation. If you later sell the home, those records help establish your cost basis and may reduce capital gains taxes. They also help if you refinance the HELOC into a new first mortgage down the road.
Finally, think about the return on investment. Not every renovation adds value. A minor kitchen remodel or garage door replacement often recoups a high percentage of its cost at resale, while a luxury pool or extensive landscaping may not. Financing home improvements with a HELOC makes the most sense when the project either increases your home's value or improves your quality of life enough to justify the cost. For broader guidance on comparing loan products and running payment scenarios, resources like LoanFinancing offer calculators and educational articles that can help you stress-test your budget before you commit.
Risks, Costs, and Mistakes to Avoid
The biggest risk with a HELOC is that it is secured by your home. If your financial situation changes and you cannot make payments, you could lose the property. Variable rates add another layer of uncertainty: a line that starts at a comfortable payment can become expensive if rates climb. Before you sign, ask your lender for the maximum possible payment based on your credit limit and the highest rate allowed by the agreement.
Closing costs, annual fees, and early closure penalties can erode the benefits of a HELOC. Some lenders waive closing costs but charge a fee if you close the line within two or three years. Read the fine print and compare offers from multiple lenders. Even a small difference in rate or fees can save hundreds over the life of the line.
Common mistakes include borrowing the full limit immediately, using the line for discretionary spending rather than the renovation, and failing to plan for the repayment period when payments jump. A disciplined approach, with a clear budget and a repayment plan, keeps the line manageable.
It also helps to have a contingency fund. Renovations frequently uncover hidden problems, like water damage or outdated wiring. If your HELOC limit is fully drawn and you have no cash reserve, you may be forced to pause the project or use high-interest credit. A buffer of 10% to 20% of the project cost, either in savings or available credit, provides breathing room.
Step-by-Step: How to Get Started
If you have decided a HELOC is the right fit, the process is straightforward but requires preparation. Start by checking your credit report for errors and gathering recent pay stubs, tax returns, and bank statements. Then estimate your home's current value using recent comparable sales or an online tool, and calculate your CLTV.
Next, request quotes from at least three lenders. Compare not just the introductory rate but also the margin, index, caps, fees, and repayment terms. Ask each lender how long the draw period lasts and whether you can convert a portion to a fixed rate. Once you choose a lender, complete the application and schedule the appraisal if required. Underwriting may take a few weeks, after which you close and can begin drawing funds.
Here is a simple checklist to follow:
- Check your credit score and report, and address any issues
- Calculate your available equity and target line amount
- Gather income and asset documentation
- Compare offers from multiple lenders, focusing on total cost
- Complete the application and appraisal
- Close the line and plan your draw schedule around project milestones
Remember that a HELOC is a financial commitment, not free money. The most successful borrowers treat it as a tool for a specific purpose, with a clear plan to repay the balance during the draw period or soon after. Used wisely, financing home improvements with a HELOC can transform your living space without draining your savings or derailing your long-term financial goals.