First Time Homebuyer Mistakes to Avoid During Pre Approval
Avoid common first time homebuyer mistakes to avoid during pre approval, from job changes to new credit, and keep your loan on track to closing day.
By Alice Shaw
You have found the house, imagined the move, and now you are staring at a pre-approval application that feels like a financial stress test. For first time homebuyers, the pre-approval stage is where excitement meets underwriting scrutiny. A single misstep, like opening a new credit card for furniture or switching jobs mid-process, can turn an approved loan into a denied one faster than you can say closing day. The good news: these first time homebuyer mistakes to avoid during pre approval are predictable, and avoiding them is entirely within your control. This guide walks you through the most common pitfalls, why they matter, and how to keep your approval intact from application to closing table.
Why Pre-Approval Is a Snapshot, Not a Guarantee
A pre-approval letter is not a golden ticket. It is a lender's conditional assessment based on the financial information you provided at a specific moment in time. Underwriters verify that information again before final approval, often just days before closing. Between the pre-approval and the final loan commitment, your financial life is under a microscope. Any change that alters your risk profile can force the lender to re-evaluate, delay, or deny your loan.
Many first time buyers treat pre-approval as the finish line when it is really the starting line. They relax, make large purchases, or restructure their finances without realizing that underwriting continues behind the scenes. The result is a last-minute scramble to explain new debts, sudden deposits, or employment changes. Understanding that pre-approval is a moving target, not a permanent status, is the first step toward protecting your loan.
The stakes are real. Sellers take your offer seriously because of that pre-approval letter. If your financing falls apart later, you risk losing the home, your earnest money deposit, and the time spent on inspections and negotiations. Staying disciplined from pre-approval to closing is not just financial prudence; it is a commitment to the purchase itself.
Mistake 1: Changing Jobs or Employment Status Mid-Process
Lenders love stability. During underwriting, your employment history is verified, often right up until closing. Quitting your job, accepting a new position, or transitioning from salaried to self-employed can raise red flags, even if your income increases. A new job may come with a probationary period, and some lenders require a history of consistent income before they will count it toward your loan qualification.
If you are considering a job change during the pre-approval period, talk to your loan officer first. Sometimes a lateral move within the same industry and income level is acceptable, but it still requires documentation and explanation. A complete career change or a move to commission-based pay is riskier. The safest approach is to wait until after closing to make major career moves, unless the change is unavoidable.
Self-employed buyers face additional scrutiny. If you are a freelancer or business owner, lenders want to see two years of tax returns and a stable client base. Taking on a new contract or restructuring your business during the loan process can complicate income verification. Keep your business finances steady and provide documentation promptly when requested. For a deeper dive into how loan programs handle income and eligibility, including options for first time buyers, see this guide on FHA loan requirements for first time homebuyers.
Mistake 2: Opening New Credit Lines or Making Large Purchases
It is tempting to celebrate your pre-approval by financing new furniture, a car, or a major appliance. Resist that urge. Every new credit inquiry, account, or loan increases your debt-to-income ratio and signals to underwriters that you may be overextending yourself. Even a store credit card with a zero balance can lower your credit score temporarily and raise questions about your financial discipline.
Large purchases on existing credit cards are equally problematic. If you charge $5,000 for a new mattress set and do not pay it off immediately, your minimum monthly payment increases, and your debt-to-income ratio climbs. Underwriters recalculate your ratios at closing, and a sudden spike in debt can push you over the allowable threshold for your loan program. This is one of the most common first time homebuyer mistakes to avoid during pre approval, and it is entirely preventable.
What counts as a large purchase? Any financing that adds a monthly payment (auto loans, furniture financing, personal loans) or any credit card balance you cannot pay in full. Even co-signing a loan for a family member can appear on your credit report and affect your ratios. Keep your credit profile exactly as it was when you applied. If you need something for the new home, wait until after closing, when your loan has funded and the keys are in your hand.
Mistake 3: Moving Money Without a Paper Trail
Underwriters are detectives. They want to know where every dollar for your down payment and closing costs came from. Large, unexplained deposits into your bank accounts can trigger requests for documentation or even derail your loan. If you transfer money from a savings account to checking, that is usually fine, but you need to show the trail. If a family member gifts you money, you need a gift letter and proof of the transfer.
Cash deposits are particularly problematic. If you deposit $3,000 in cash from a side job or a personal sale, the lender may ask for a written explanation and supporting documents. Without a clear source, underwriters may exclude that money from your available funds. The same applies to selling personal items, like a car or furniture, during the loan process. Keep receipts and be ready to document the transaction.
Here is a simple framework to keep your funds clean and verifiable:
- Document every deposit over $500: Save receipts, transfer confirmations, or gift letters.
- Avoid cash transactions: Use traceable methods like bank transfers or checks.
- Keep your accounts stable: Do not close accounts or move large sums between institutions without a clear reason.
- Ask before you act: If you need to move money, call your loan officer first to confirm the best way to document it.
These steps may feel tedious, but they prevent last-minute underwriting delays. A well-documented file moves smoothly; a messy one invites scrutiny and stress.
Mistake 4: Ignoring Rate Lock Timing and Home Inspection Decisions
A rate lock protects your interest rate for a set period, typically 30 to 60 days. If your closing is delayed, your lock may expire, and you could end up with a higher rate. Many first time buyers do not realize that their actions can extend the timeline. Choosing a home with complex inspection issues, negotiating repairs, or switching lenders mid-process can all push closing past the lock period.
Home inspections are another timing trap. If the inspection reveals problems, you may need to renegotiate with the seller, which takes time. A delayed closing can cost you money if your rate lock expires. Plan for contingencies and keep your loan officer informed of any inspection-related delays. In some cases, you may need to extend the lock, which could involve a fee.
On the flip side, skipping a home inspection to speed up the process is a dangerous mistake. You could inherit hidden defects that cost thousands to repair, and some loan programs require certain repairs before closing. A thorough inspection protects your investment and helps you avoid surprises. Balance speed with diligence: do not let the race to close push you into a poor decision.
Mistake 5: Disorganized Documentation and Slow Responses
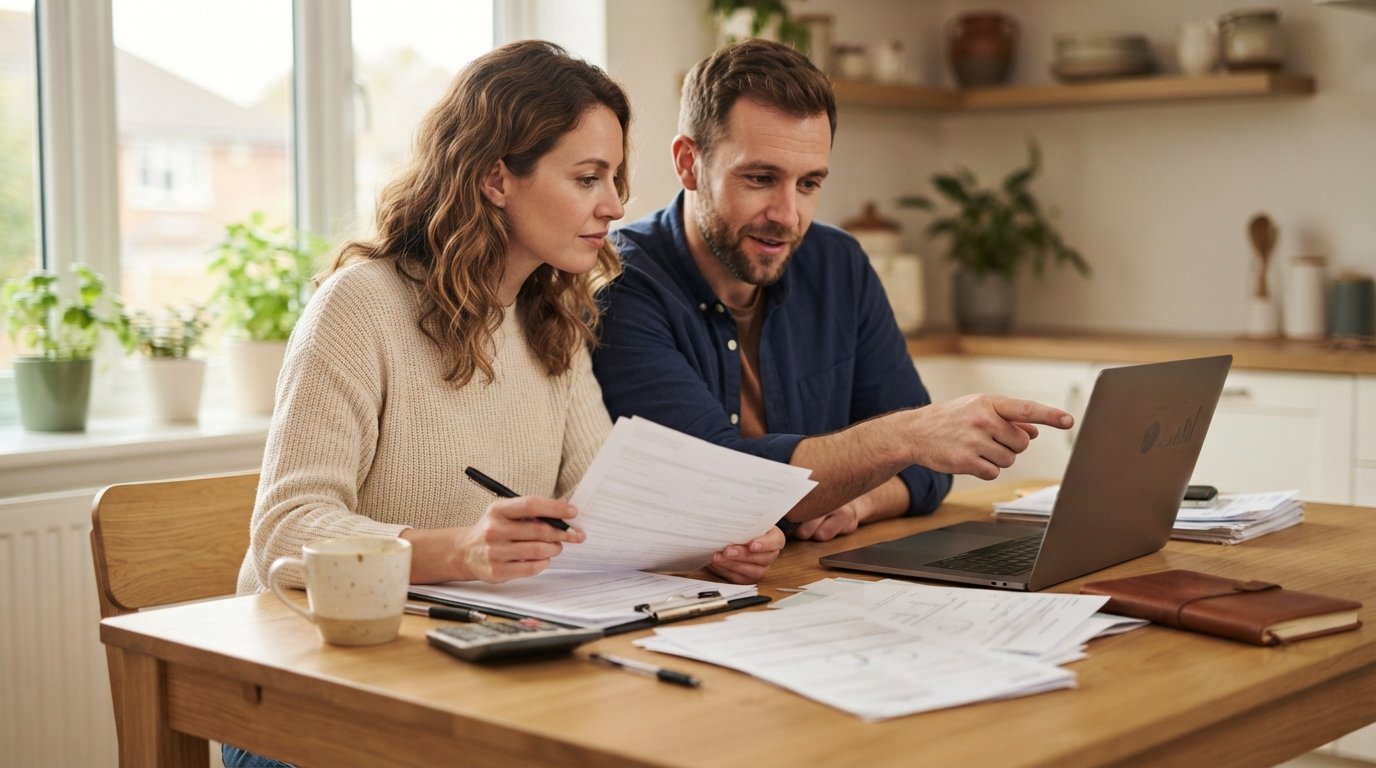
Underwriters ask for a lot: pay stubs, tax returns, bank statements, explanations for credit inquiries, and more. First time buyers often underestimate the volume of paperwork and the importance of responding quickly. A missing document or a vague explanation can stall your loan for days. In a competitive market, delays can cost you the home.
Create a dedicated folder (digital or physical) for your loan documents. When you receive a request, respond within 24 hours if possible. Be precise: if the underwriter asks for a letter explaining a deposit, provide the date, amount, source, and any supporting documents. Do not guess or provide incomplete information. If you are unsure what is needed, ask your loan officer for clarification.
Organization also helps you spot potential issues early. If you notice a discrepancy in your bank statements or a credit report error, address it immediately. Waiting until the last minute can turn a minor issue into a major delay. A proactive, organized approach signals to underwriters that you are a reliable borrower, which can smooth the entire process.
Mistake 6: Forgetting About Closing Costs and Cash Reserves
Your down payment is not the only cash you need. Closing costs, which include lender fees, title insurance, appraisal fees, and prepaid items like property taxes and homeowners insurance, typically run 2% to 5% of the purchase price. First time buyers sometimes stretch their savings to cover the down payment, leaving nothing for closing costs. This can force them to accept a higher-rate loan or scramble for last-minute funds.
Lenders also require cash reserves, typically one to six months of mortgage payments, depending on the loan program. These reserves must be documented and available after closing. If you drain your accounts for the down payment, you may fail the reserves test. Plan your budget to cover the down payment, closing costs, and reserves without depleting your emergency fund.
Understanding these costs upfront helps you avoid surprises. Use a mortgage calculator to estimate your monthly payment, including taxes and insurance, and factor in closing costs when setting your budget. For a comprehensive overview of mortgage products and how they work, including plain-language explanations of rates and terms, visit MortgageDirectory. Their educational resources can help you compare options before you talk with a lender.
Mistake 7: Making Inconsistent Statements or Hiding Information
Underwriters cross-check everything. If your loan application says you plan to occupy the home as your primary residence, but your driver's license, tax returns, or other documents suggest otherwise, you will face questions. Inconsistencies, even innocent ones, can trigger a fraud review and delay your loan. Always be truthful and consistent in your paperwork.
Hiding a debt, a side business, or a previous foreclosure never works. Lenders pull credit reports, verify employment, and review public records. If they discover undisclosed information, they may deny your loan or require a lengthy explanation. Transparency is always the best policy. If you have a blemish on your credit or a complex financial history, disclose it upfront and provide context. Your loan officer can help you navigate the underwriting process if they know the full picture.
Similarly, do not assume that a small oversight will go unnoticed. A forgotten student loan, a collection account, or a recent late payment can affect your approval. Review your credit report before you apply and address any errors. Being upfront saves time and builds trust with your lender.
How to Protect Your Pre-Approval: A Quick Checklist
Staying disciplined during the pre-approval period is easier when you have a clear plan. Use this checklist to keep your loan on track:
- Keep your employment stable: Avoid job changes, especially to a new industry or commission-based role, until after closing.
- Freeze your credit profile: Do not open new credit accounts, finance large purchases, or co-sign loans.
- Document every deposit: Keep paper trails for gifts, transfers, and any unusual deposits.
- Respond to requests promptly: Provide complete documents within 24 hours and ask for clarification when needed.
- Budget for closing costs and reserves: Ensure you have funds beyond the down payment and do not drain your savings.
Following these steps reduces the risk of last-minute surprises and keeps your closing on schedule. Remember that your loan officer and real estate agent are your allies. Communicate openly about any changes in your financial situation, and ask questions before you make decisions that could affect your loan.
The Bottom Line on Avoiding Pre-Approval Pitfalls
First time homebuyers often focus on finding the perfect home, but protecting the financing is just as important. The mistakes outlined here, from job changes to new credit lines to disorganized paperwork, are common but avoidable. By treating pre-approval as an ongoing process and staying financially consistent, you can move from application to closing with confidence.
Your pre-approval is a powerful tool in a competitive market, but it comes with responsibilities. Stay disciplined, document everything, and communicate with your lender. With the right approach, you can avoid the first time homebuyer mistakes to avoid during pre approval and focus on what matters most: making your new house a home.