Home Appraisal vs. Home Inspection: Key Differences
Understand the difference between home appraisal and home inspection, from who orders each report to how findings affect financing and negotiation.
By Grace Parker
You have found the house, negotiated the price, and signed the purchase agreement. Now your lender and your real estate agent start throwing around two terms that sound almost identical: appraisal and inspection. Many buyers assume they are the same thing or that one automatically covers the other. That assumption can cost you thousands of dollars, either in unexpected repairs or in a financing delay that jeopardizes the deal. Understanding the difference between home appraisal and home inspection is one of the most practical pieces of knowledge you can carry into a purchase, and it directly affects how you budget, negotiate, and protect yourself before closing.
What a Home Appraisal Actually Does
A home appraisal is a valuation exercise ordered by the lender, not by you. When you apply for a mortgage, the lender needs an independent opinion of what the property is worth because the house serves as collateral for the loan. The appraiser is a licensed or certified professional who inspects the property, measures square footage, notes condition and upgrades, and then compares the home to recent sales of similar properties in the area. The final report delivers a single number: the appraised value.
That number drives the financing. Lenders typically cap the loan amount at a percentage of the appraised value, so if the appraisal comes in lower than the contract price, the lender will not finance the gap. You would then need to renegotiate the price, bring extra cash to closing, or walk away. This is why the appraisal is fundamentally a risk-management tool for the lender, even though you pay for it as part of your closing costs.
The appraiser is not a home inspector and does not test systems or hunt for defects. An appraisal report might note obvious issues like a damaged roof or peeling paint, but its purpose is value, not condition. A common misconception is that a clean appraisal means the house is in good shape. It does not. It means the lender believes the property is worth the loan amount, which is a completely different question from whether the furnace will survive the winter.
What a Home Inspection Covers That an Appraisal Does Not
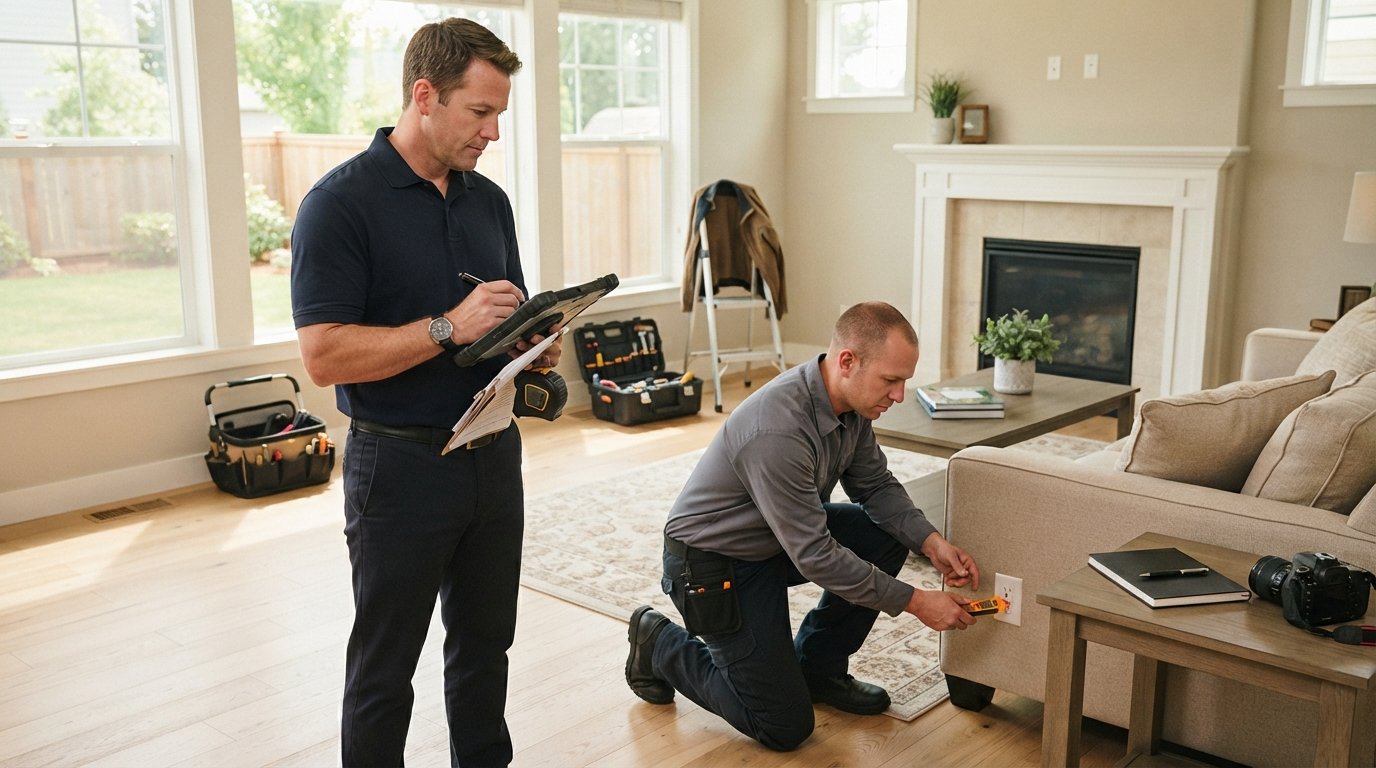
A home inspection is ordered by you, the buyer, and it serves your interests alone. A licensed home inspector performs a visual, non-invasive examination of the property's major systems and components. The inspector is trained to identify defects, safety hazards, and maintenance issues that a typical buyer would miss during a walkthrough. The report gives you a detailed picture of the home's condition so you can decide whether to proceed, renegotiate, or walk away.
Where the appraisal produces a value, the inspection produces a punch list of problems. A good inspector will examine the following areas in detail:
- Roof covering, flashing, and drainage
- Foundation, grading, and structural elements
- Electrical panels, wiring, and outlets
- Plumbing supply lines, drains, and water heater
- HVAC systems, including heating and cooling equipment
- Attic insulation, ventilation, and signs of moisture
The inspector will also look for evidence of water intrusion, pest activity, and unsafe conditions such as missing handrails or improper gas connections. The resulting report is usually delivered within a day or two and includes photos and recommendations. That document becomes your negotiating tool if the findings reveal expensive problems.
Who Orders Each Report and Who Pays
The ordering chain is one of the clearest distinctions between the two. Your lender orders the appraisal, usually through an appraisal management company, and you pay for it as part of your loan costs. The appraiser works for the lender's process, even though you cover the fee. You cannot shop for an appraiser or instruct them on what value to reach. The lender needs an unbiased opinion, and the system is designed to keep it that way.
You order the home inspection yourself, typically through your real estate agent's referral network or your own research. You choose the inspector, you schedule the appointment, and you pay the inspector directly, usually a few hundred dollars depending on the size and age of the home. Because the inspector works for you, you can attend the inspection, ask questions, and request clarification on any finding. This distinction matters because it tells you whose interests each professional is serving. The appraiser protects the lender's collateral. The inspector protects your wallet and your safety.
How Each Report Affects Your Deal
The appraisal and the inspection influence the transaction in completely different ways, and mixing them up can lead to bad decisions. The appraisal affects financing. If the appraised value meets or exceeds the purchase price, your loan proceeds as planned. If it comes in low, the lender will reduce the loan amount, and you must cover the difference or renegotiate. A low appraisal can also derail a deal entirely if the seller refuses to adjust the price. In that scenario, knowing your options is critical, and our guide on what happens if your home appraisal comes in low walks through the renegotiation and cash-cover strategies in detail.
The inspection affects negotiation and your willingness to proceed. Inspection findings do not automatically change the loan terms, but they give you leverage. If the inspector finds a failing roof, outdated electrical panel, or active plumbing leak, you can ask the seller to repair the items, credit you the cost, or lower the purchase price. The seller can agree, counter, or refuse. If you cannot reach an agreement, your inspection contingency typically allows you to cancel the contract and recover your earnest money. That contingency is one of the most valuable protections you have as a buyer.
Skipping the inspection to make your offer more competitive shifts all repair risk onto you. You would have no formal recourse if the water heater fails the week after closing or if the foundation has hidden cracks. Some buyers waive the inspection in hot markets, but they do so with eyes open, often budgeting a reserve for unknown repairs. For most buyers, especially first-time buyers, the inspection fee is a small price for substantial peace of mind.
Timelines and Contingency Periods
Both reports fit inside the contingency windows written into your purchase contract, and the order of operations matters. The inspection usually happens first, often within the first week or two after your offer is accepted. Your inspection contingency gives you a set number of days to complete the inspection and respond to the findings, either by accepting the property as-is, requesting repairs or credits, or canceling. This is your window to gather information and make decisions before you are locked in.
The appraisal typically comes after the inspection period or runs in parallel, depending on the lender and the contract. Your lender orders it once you have a fully executed purchase agreement and have submitted your loan application. The appraisal contingency, if your contract includes one, gives you an exit if the value comes in low. Some contracts combine these protections, while others separate them. Either way, you should know your deadlines cold. Missing an inspection contingency deadline can waive your right to renegotiate, and missing an appraisal deadline can leave you obligated to close even if the financing falls apart.
A practical sequence for most buyers looks like this: schedule the inspection immediately after the offer is accepted, attend the inspection and review the report within the contingency window, submit any repair requests or credits to the seller, and let the lender order the appraisal once the contract is firm. If the appraisal comes in at or above the purchase price, you move toward closing. If it comes in low, you renegotiate or adjust your financing before the closing date.
Why the Confusion Persists and How to Avoid It
The two reports share surface similarities: a professional visits the property, writes a report, and charges a fee. Both happen before closing, and both can influence whether the deal survives. That surface similarity is why so many buyers treat them as interchangeable. But the difference between home appraisal and home inspection lies in purpose, audience, and consequence. One answers "what is this house worth to a lender?" The other answers "what is wrong with this house, and what will it cost to fix?"
Confusing the two can lead to real financial harm. A buyer who assumes the appraisal covered the roof might skip the inspection and inherit a five-figure replacement. A buyer who treats the inspection as a financing step might miss a low appraisal and lose the deal at the last minute. Keeping the roles separate in your mind helps you ask the right questions of the right professionals and use each report for its intended purpose.
For buyers who want to understand how loan terms, rates, and monthly payments interact with the purchase price, resources like MortgageDirectory's educational guides and payment calculator can help you run scenarios before you talk with a lender. Understanding the financing side makes the appraisal conversation easier, because you will already know how a low value would affect your loan-to-value ratio and your monthly payment.
How Express Mortgage Quotes Fits In
Express Mortgage Quotes is an educational and lead-generation platform that helps buyers, refinancing homeowners, and older homeowners research loan options and compare quotes from verified lenders. The site is not a lender, broker, or bank, and it does not originate or approve loans. What it does provide is plain-language guidance on home purchase loans, refinancing, home equity products, and reverse mortgages, along with an interactive mortgage calculator that lets you estimate payments and see how different loan amounts and rates affect your budget.
When you are preparing for a purchase, understanding the appraisal and inspection process is part of being a well-informed borrower. Express Mortgage Quotes publishes guides on closing costs, appraisal outcomes, and loan eligibility so you can walk into the process knowing what to expect. If you are ready to compare offers, the platform connects you with participating lenders through a simple form-based inquiry. Rates and terms vary by lender and are subject to change, so confirming current details directly with a licensed lender is always the right final step.
Quick Comparison at a Glance
The fastest way to lock in the distinction is to see the two reports side by side. The table below summarizes the key differences in purpose, ordering, and impact.
- Purpose: Appraisal establishes value for the lender. Inspection establishes condition for the buyer.
- Ordered by: Appraisal is ordered by the lender. Inspection is ordered by the buyer.
- Who it protects: Appraisal protects the lender's collateral position. Inspection protects the buyer from hidden defects.
- Impact on deal: Appraisal affects financing and loan amount. Inspection affects negotiation and the buyer's decision to proceed.
- Contingency: Appraisal contingency addresses low value. Inspection contingency addresses repair findings.
Keep this comparison in mind as you move through your purchase. The appraisal and the inspection are not competing reports or duplicate expenses. They are two separate safeguards that answer two separate questions, and together they give you a clearer picture of both the value and the condition of the home you are about to buy.
Before you close, make sure you have reviewed both reports, met your contingency deadlines, and confirmed your financing terms with your lender. A few hours spent understanding these documents can save you from surprise bills, stalled financing, or a home that costs more than you bargained for.