How Property Taxes and Homeowners Insurance Affect Monthly Payment
Property taxes and homeowners insurance can add hundreds to your monthly payment and shift over time. See how each one works and how to budget for increases.
By Daniel Smith
When you set out to buy a home, the number that usually grabs your attention first is the list price. Soon after, your focus shifts to the interest rate on your mortgage. Both matter enormously, but they are far from the whole story. The monthly payment you actually write a check for includes several moving parts, and two of the most overlooked are property taxes and homeowners insurance. Together they can add hundreds of dollars to your housing costs every month, and they can change over time in ways your principal and interest payment never will. Understanding how property taxes and homeowners insurance affect monthly payment is one of the most practical pieces of knowledge a buyer or refinancing homeowner can carry into the process.
Lenders do not just care about whether you can afford the loan itself. They care about whether you can afford to keep the home over the long run, which means keeping taxes current and insurance active. That is why both costs are baked into your escrow account and included in the payment you make each month. If either one rises, your payment can rise with it, even when your mortgage rate stays exactly the same. For anyone comparing loan offers or budgeting for a purchase, ignoring these two line items is a recipe for an unpleasant surprise.
What Actually Makes Up Your Monthly Mortgage Payment
Most homeowners have heard the term PITI, even if they do not remember what the letters stand for. PITI stands for principal, interest, taxes, and insurance. Principal is the portion that reduces the balance you owe on the home. Interest is the cost of borrowing the money. Taxes and insurance are the two components that have nothing to do with the loan itself but still appear on your monthly statement because your lender collects them on your behalf. A fifth component, private mortgage insurance, may also appear if your down payment was less than 20 percent of the purchase price.
Here is a simple breakdown of what each piece represents and how it behaves over time:
- Principal: The part of the payment that lowers your loan balance; it grows slowly at first and faster later in the loan term.
- Interest: The lender's charge for financing the home; it is fixed on a fixed-rate loan and can adjust on an adjustable-rate mortgage.
- Property taxes: Assessed by your county or municipality based on the value of your home and land; collected monthly and held in escrow.
- Homeowners insurance: Protects the structure and your liability; required by virtually every lender and also collected through escrow.
- Mortgage insurance: Required on some loans with low down payments; it protects the lender, not you, and can sometimes be removed later.
Because taxes and insurance are collected in escrow, many borrowers treat them as an afterthought until the annual escrow analysis arrives and the payment changes. In reality, these two items often represent 20 to 40 percent of a total monthly housing payment in high-tax or high-insurance areas. That share is large enough that any serious affordability calculation has to account for them from the very beginning.
How Property Taxes Shape Your Monthly Payment
Property taxes are levied by local governments, usually at the county level, and they fund schools, roads, emergency services, parks, and other public needs. The amount you owe is calculated by multiplying your home's assessed value by the local tax rate, often expressed as a millage rate. Because both the assessed value and the rate can change, your tax bill is never truly fixed. It can rise when your area reassesses property values, when voters approve new levies, or when a local government needs additional revenue.
For your monthly payment, the practical effect is straightforward. Your lender estimates the annual tax bill, divides it by twelve, and adds that amount to your payment. If the estimate turns out to be too low, you face an escrow shortage, which means either a higher payment next year, a lump-sum catch-up, or both. If the estimate is too high, you may receive an escrow refund, but your payment could also be adjusted downward. Either way, the tax component is a living number, not a one-time figure locked in at closing.
Geography matters enormously here. Two homes with identical prices can carry wildly different tax burdens depending on the state, county, and even the school district. Some states cap annual assessment increases, which smooths out year-to-year changes, while others reassess more aggressively. If you want a deeper look at how this single line item moves your payment, our guide on the impact of property taxes in mortgage breaks down the mechanics in more detail.
Why Tax Escrow Creates Payment Volatility
Escrow is convenient because it spreads a large annual bill across twelve smaller payments. The tradeoff is that escrow introduces volatility that a fixed-rate mortgage otherwise would not have. Your principal and interest payment may stay identical for thirty years, yet your total payment can still climb because the tax portion increased. Lenders typically require a cushion of a few months of taxes in the escrow account, and they reconcile the account once a year. That reconciliation is when most borrowers discover their payment is about to change.
New construction is a common trap. The first year's tax assessment may be based on undeveloped land rather than the finished home, so the initial escrow estimate is artificially low. When the county reassesses the property with the house on it, the tax bill can jump dramatically, and the monthly payment follows. Buyers who budget only for the first-year figure often find themselves stretched in year two. Asking the county assessor or your real estate agent for an estimate of the post-improvement tax bill is a smart safeguard.
How Homeowners Insurance Fits Into the Equation
Homeowners insurance protects you against losses from fire, storms, theft, and liability claims, and it is almost always required by the lender as a condition of the loan. Like taxes, the annual premium is divided by twelve and collected through escrow. Unlike taxes, the premium is set by an insurance company rather than a government, which means it responds to a different set of forces: construction costs, catastrophe risk, claims history, and the insurer's own appetite for risk in your region.
Insurance premiums have been rising sharply in many parts of the country, particularly in coastal and wildfire-prone areas. A single year of severe storms can push rates up across an entire state. When your premium rises, your escrow analysis will reflect it, and your monthly payment will increase even though nothing about your loan changed. This is one of the clearest examples of how property taxes and homeowners insurance affect monthly payment in ways borrowers cannot control through their loan terms alone.
There are ways to influence the insurance side, though. Shopping the policy at renewal, choosing a higher deductible, bundling auto and home coverage, and maintaining a strong claims history can all reduce premiums. Improving the home's resilience, such as adding storm shutters or a new roof, may also earn discounts. Because the lender only requires enough coverage to protect its collateral, you have room to compare policies and select one that balances protection with cost.
When Insurance Becomes Difficult to Obtain
In some high-risk markets, private insurers have paused writing new policies or withdrawn entirely. When that happens, homeowners may need coverage through a state-backed insurer of last resort, which often costs more and offers narrower protection. Lenders still require coverage, so the premium gets folded into escrow regardless. For buyers considering homes in these areas, getting an insurance quote before making an offer is not optional; it is essential to understanding the true monthly cost.
Putting the Numbers Together: A Practical Example
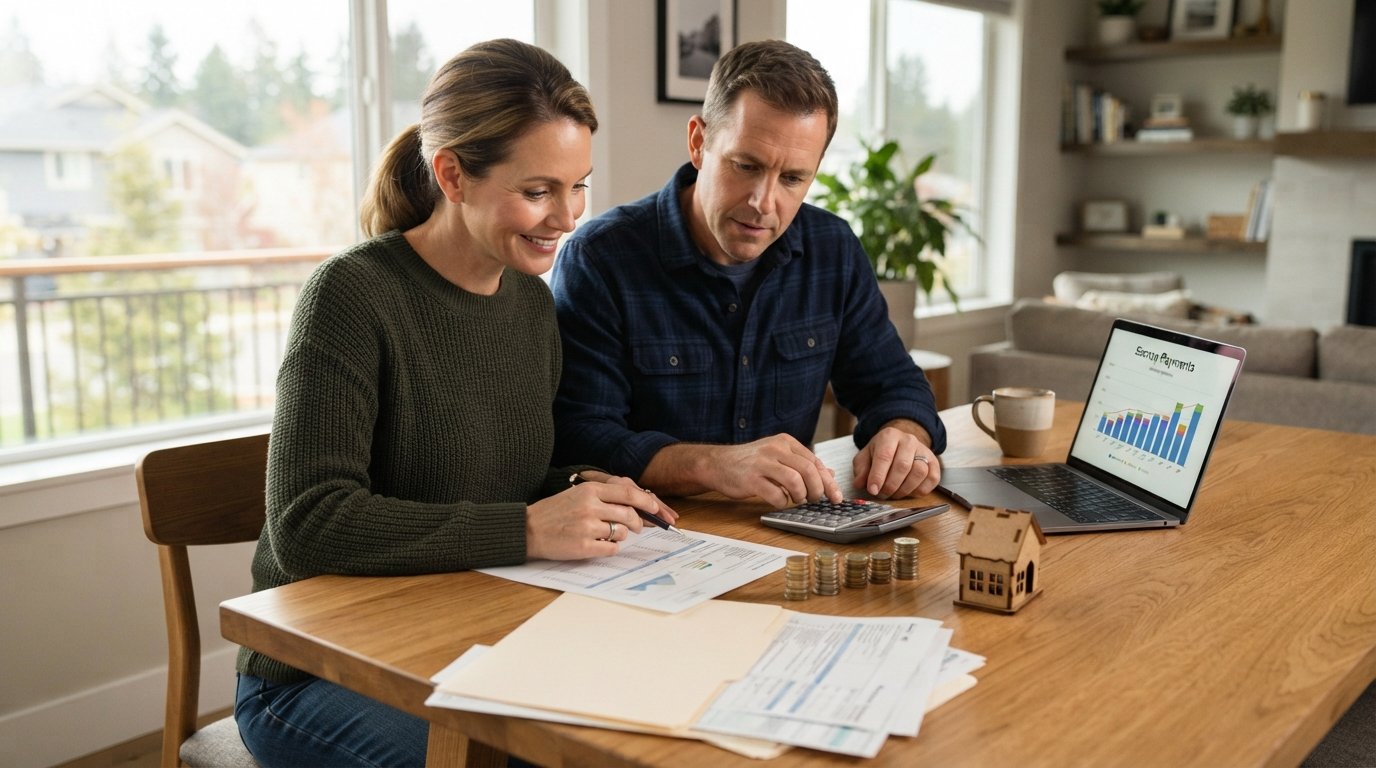
Suppose you buy a home for $400,000 with a 20 percent down payment, leaving a $320,000 loan at a 6.5 percent fixed rate. The principal and interest payment on a thirty-year term would be roughly $2,023 per month. Now add property taxes of $6,000 per year, or $500 per month, and homeowners insurance of $1,800 per year, or $150 per month. The total monthly payment lands near $2,673, about 32 percent higher than the principal and interest figure alone.
If taxes rise 8 percent the following year and insurance rises 12 percent, the combined escrow portion climbs by roughly $58 per month. The loan itself did not change at all, yet the household budget now needs another $700 per year. Multiply that across several years of increases and the gap between the sticker payment and the real payment becomes substantial. This is why comparing loan offers on interest rate alone can be misleading; two lenders quoting the same rate may estimate taxes and insurance differently, producing different monthly figures.
Using an interactive mortgage calculator that lets you input your own tax and insurance estimates gives you a far more realistic picture than a default estimate. It also lets you test scenarios, such as what happens if taxes rise or if you choose a higher insurance deductible, before you commit to a property.
How Taxes and Insurance Affect Refinancing Decisions
Homeowners often refinance to lower their interest rate or change their loan term, expecting the monthly payment to drop. Sometimes it does, but not by as much as anticipated, because taxes and insurance are unaffected by the refinance. If those costs have risen since the original loan, they can offset a meaningful portion of the interest savings. A homeowner who refinances from 7 percent to 6 percent might save $200 on principal and interest but see $120 of that absorbed by higher escrow costs.
That does not mean refinancing is a bad idea. It means the break-even analysis has to include the full payment, not just the loan portion. Lenders will recalculate your escrow based on current tax and insurance figures, so the new payment quote you receive should reflect reality. If you are considering a cash-out refinance to access equity, remember that the larger loan balance increases principal and interest, while taxes and insurance remain the same. The combined effect is what determines whether the new payment fits your budget. Exploring multiple refinance quotes side by side, along with their escrow estimates, is the most reliable way to compare offers fairly.
Strategies to Manage Rising Escrow Costs
You cannot control tax rates or insurance markets, but you can take steps to keep the combined burden from blindsiding you. The goal is to anticipate increases, contest errors, and shop aggressively where competition exists. A few practical moves make a real difference over the life of a loan.
- Review your escrow analysis every year. Check that the tax and insurance figures match the actual bills, and question any discrepancy with your servicer promptly.
- Verify your assessed value. If the county's assessment exceeds your home's realistic market value, file an appeal with supporting evidence such as a recent appraisal.
- Shop insurance at every renewal. Loyalty rarely pays in home insurance; comparing at least three quotes keeps the market honest.
- Consider a higher deductible. Raising it from $500 to $2,500 can cut premiums noticeably, provided you have savings to cover the difference.
- Budget for increases. Set aside a small monthly buffer so an escrow adjustment does not derail your finances.
These steps will not eliminate volatility, but they put you in a position to respond rather than react. A homeowner who reviews escrow annually and shops insurance proactively typically pays less over time than one who simply accepts whatever the servicer bills. For a broader view of current market conditions and rate trends that influence overall affordability, resources such as RateChecker's mortgage rate comparison tools can help you see how loan pricing interacts with these carrying costs.
What Lenders Consider When Setting Your Payment
Lenders estimate taxes and insurance as part of the loan application and disclosure process. The estimates appear on the Loan Estimate and later on the Closing Disclosure, and they must be reasonably accurate. If the actual bills come in higher than disclosed, the escrow account absorbs the difference, and your payment adjusts at the next analysis. This is why two buyers with identical loans can end up with different monthly payments: the underlying tax and insurance costs differ by property, not by loan terms.
Underwriting also considers the full payment when calculating debt-to-income ratios. A borrower whose principal and interest consume 25 percent of income might see the ratio climb to 33 percent once taxes and insurance are included, which can affect approval or the loan amount offered. Keeping the complete picture in view from the start prevents surprises at underwriting and helps you set a realistic price range before you shop.
Planning Ahead With the Full Payment in Mind
The most durable approach to home affordability is to treat taxes and insurance as first-class line items, not footnotes. When you evaluate a property, gather the actual tax bill and an insurance quote before you fall in love with the house. When you compare loan offers, compare the total payment, not just the rate. When you refinance, run the break-even calculation on the full monthly figure. Each of these habits protects you from the gap between what a loan costs and what a home actually costs to own.
Property taxes and homeowners insurance will keep changing for as long as you own the home, and your monthly payment will keep reflecting those changes. The borrowers who handle this best are the ones who understand the structure of their payment, review escrow regularly, and stay ready to shop for insurance or appeal an assessment when it makes sense. That knowledge does not just save money; it turns a confusing statement into a manageable plan.