How to Compare Mortgage Loan Estimates Side by Side
Line up competing Loan Estimates side by side to spot hidden fees, compare APRs, and potentially save thousands over the life of your mortgage.
By Olivia White
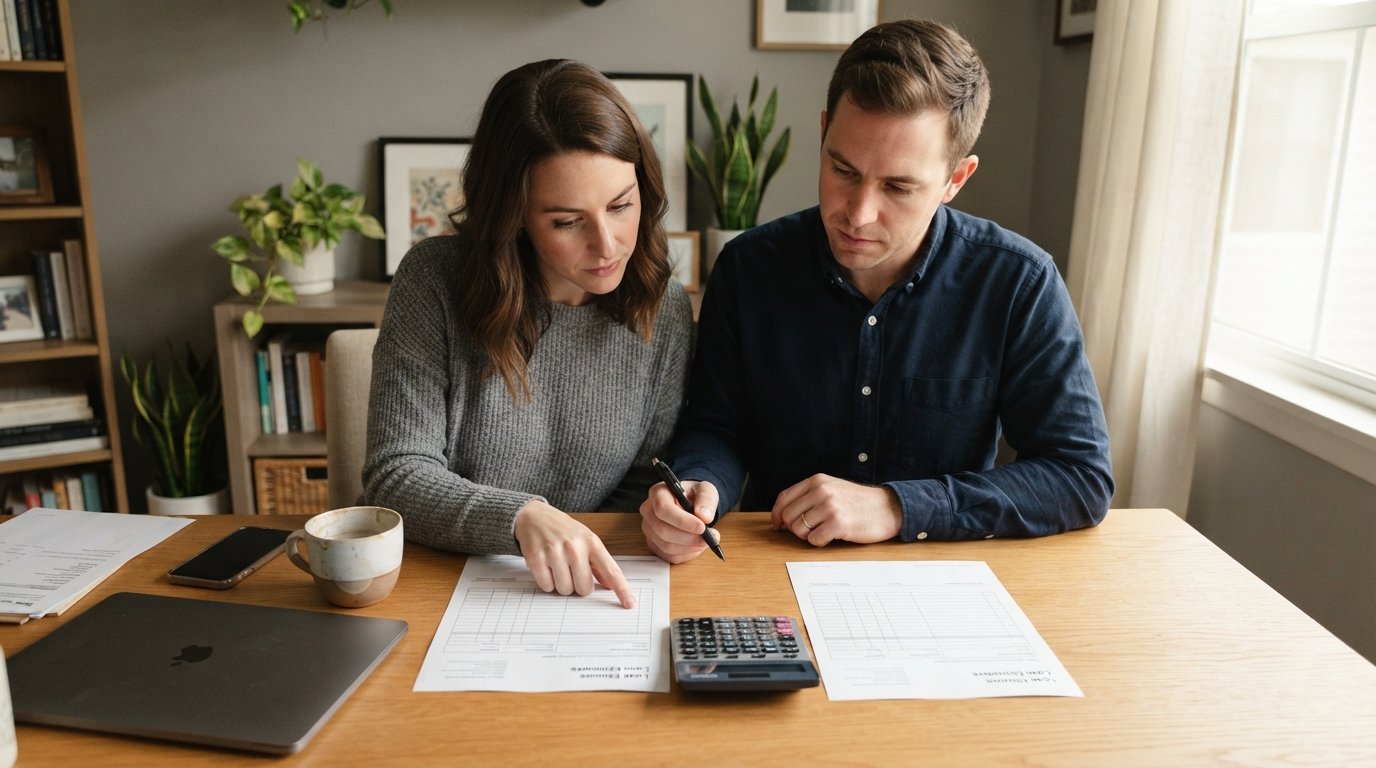
Your mortgage is likely the largest financial commitment you will ever make, and the difference between two seemingly similar loan estimates can add up to tens of thousands of dollars over the life of the loan. Yet many buyers skim the paperwork, glance at the interest rate, and sign without ever lining up competing offers to see what is really being promised. Learning how to compare mortgage loan estimates side by side is one of the most valuable skills you can develop in the home financing process, because it forces every lender to compete on equal footing using the same standardized document.
The Loan Estimate (LE) was designed by the Consumer Financial Protection Bureau to make shopping easier. Every lender must provide it within three business days of your application, and it must follow the same format no matter which company you work with. That consistency is your advantage: it means you can place two, three, or four estimates next to each other and spot the differences that actually matter. This guide walks through the line items, the fine print, and the practical framework that helps you choose the offer that genuinely costs less.
Start with the Page 1 Snapshot: Loan Terms and Projected Payments
Page one of the Loan Estimate gives you the headline numbers, and it is the fastest place to eliminate offers that do not fit your goals. Before you dig into fees, confirm that each estimate describes the same loan. A 30-year fixed loan cannot be fairly compared to a 5/1 adjustable-rate mortgage, and a quote with 20 percent down is not the same product as one with 5 percent down. Line up the basics first: loan amount, interest rate, monthly principal and interest, and whether the rate is fixed or adjustable.
Pay close attention to the "Projected Payments" table, which shows what you will pay in the early years and, for adjustable loans, how payments could change later. Two offers with identical interest rates can produce different monthly totals once you factor in mortgage insurance, escrow items such as property taxes and homeowners insurance, and any homeowner association dues. This is also where you should check whether the lender charges a prepayment penalty or a late payment fee, because those clauses are easy to overlook and expensive to trigger.
One more detail on page one deserves attention: whether the loan includes a balloon payment and when it would come due. If one estimate shows a balloon and another does not, the offers are not comparable at all. Mark that estimate aside until you understand the risk, or ask the lender to quote a fully amortizing alternative. As a general rule, only compare estimates that share the same loan type, term, and rate structure, otherwise you are comparing apples to oranges.
Compare Closing Costs Line by Line, Not Just the Total
Page two is where most of the money hides, and it is the section that rewards careful reading. Section A covers origination charges: points, application fees, and underwriting fees. Section B lists services you cannot shop for, such as the appraisal fee and credit report fee. Section C lists services you can shop for, including title insurance and settlement agent fees. Sections E, F, and G cover taxes, prepaid interest, insurance escrows, and other recording charges. The total in Section J is useful, but the individual line items tell the real story.
Here is a practical approach that keeps the comparison honest. Build a simple spreadsheet with one column per lender and one row for each fee category, then note which charges are lender-controlled versus third-party costs. The list below covers the categories most likely to differ from one estimate to the next:
- Origination charges, points, and underwriting fees (Section A), which are fully controlled by the lender
- Appraisal, credit report, and flood certification fees (Section B), which vary by provider and property
- Title services, settlement agent, and title insurance (Section C), which you may be able to shop for yourself
- Prepaid interest, property taxes, and insurance escrows (Sections F and G), which depend on your closing date and location
- Estimated cash to close (Section J), which shows how much money you need on closing day
Once the numbers are in front of you, look for patterns. A lender with a slightly higher rate but $4,000 less in origination charges may cost less if you plan to sell or refinance within a few years. A lender with a lower rate but higher third-party fees may win over a longer horizon. The break-even point is the number of months it takes for the monthly savings from a lower rate to outweigh the higher upfront cost, and calculating it is one of the most clarifying exercises in the entire process.
It also helps to know which figures are legally allowed to change. Zero percent tolerance applies to lender-controlled fees and cannot increase except in narrow circumstances. Ten percent tolerance applies to recording fees and some third-party services, meaning the total for that group can rise by up to 10 percent. No tolerance means the estimate can change, so treat those numbers as projections rather than guarantees. For a deeper look at how larger loan amounts change these calculations, our guide to jumbo mortgage loans explained breaks down the thresholds and requirements that apply above conforming limits.
Evaluate the Rate, the APR, and the Costs That Do Not Appear
The interest rate is the price of borrowing money, but it is not the full cost of the loan. The Annual Percentage Rate (APR) folds in most closing costs and expresses them as a yearly percentage, which makes it a useful tiebreaker when two offers look similar on the surface. If one lender quotes 6.25 percent with $2,000 in points and another quotes 6.40 percent with no points, the advertised rates alone will mislead you. The APR helps level the field, though it is still imperfect because it assumes you keep the loan for its full term.
Beyond the APR, consider the costs that never show up on the Loan Estimate at all. Mortgage insurance premiums on FHA and conventional loans with low down payments can add hundreds of dollars per month. Homeowner association dues, special assessments, and higher property tax rates in your target neighborhood affect your true housing payment. Closing timelines matter too: a lender that cannot close within your contract window can cost you your earnest money deposit. Weigh these factors alongside the numbers, because a slightly higher rate from a reliable, fast-closing lender is often the better financial decision.
Another variable worth pricing is the rate lock. A longer lock period usually costs more, but it protects you if rates rise before closing. Ask each lender how long the lock lasts, what it costs, and whether a float-down option is available if rates improve. If you are still early in the shopping process, real-time comparison platforms such as RateChecker can help you see how current offers stack up before you commit to a lock.
Ask the Questions That Separate a Good Offer from a Great One
Numbers alone do not tell you whether a lender will deliver. Before you decide, call each loan officer and ask the same set of questions so you can compare answers directly. The responses will reveal how transparent the lender is and how well your file fits their process.
- What is the total cash to close, and which fees are guaranteed not to change?
- Is the rate locked, for how long, and what happens if closing is delayed?
- Will this loan require mortgage insurance, and if so, for how long can it be removed?
- How many days does the lender typically need to close once the appraisal is received?
- Are there any prepayment penalties, balloon payments, or unusual clauses in the terms?
Write down the answers next to each estimate. A lender who hesitates on tolerance rules or cannot explain the mortgage insurance removal timeline is telling you something important about how the process will go. Conversely, a lender who proactively explains the trade-offs between points and rate is likely to be a better partner when underwriting questions arise.
It is also reasonable to ask whether the lender will match a competing offer. Many will reprice a quote if you show them a legitimate Loan Estimate from another company, and the savings can be meaningful. You do not need to be aggressive about it; simply sharing the competing estimate and asking if they can improve their terms is enough. Just remember that the goal is not the lowest headline rate but the lowest total cost for the loan you actually need.
Build a Side-by-Side Scorecard You Can Trust
Once you have gathered two or more Loan Estimates, a simple scorecard turns a pile of paperwork into a clear decision. Set up columns for each lender and rows for the factors that matter most to you: interest rate, APR, total closing costs, monthly payment including escrows, mortgage insurance, rate lock terms, and closing timeline. Assign a weight to each row based on your priorities, then score each offer from one to five.
The weighted approach prevents a common mistake: fixating on a single number. A buyer who plans to stay for 15 years should weight the interest rate and APR heavily, because those costs compound over time. A buyer who expects to move in three years should weight closing costs and the break-even point more heavily, because a low rate will not have time to pay back high upfront fees. Neither approach is wrong, but the scorecard makes your reasoning explicit instead of emotional.
After scoring, revisit the two offers that rank highest and read every page again with fresh eyes. Confirm that the loan amount, term, and rate structure are identical, that the cash to close is realistic given your savings, and that no tolerance category has shifted. If a lender has revised an estimate, ask for an updated version and compare it against the original to see what changed and why. Lenders are required to provide a revised Loan Estimate when certain triggering events occur, such as a rate lock or a change in the loan application.
Finally, remember that the estimate is not the contract. The Closing Disclosure you receive at least three business days before closing is the final word, and it should closely match the Loan Estimate you accepted. If a fee jumps beyond the allowed tolerance, you have the right to ask questions and, in some cases, to delay closing until the discrepancy is resolved. Comparing estimates side by side gives you the leverage and the documentation to hold lenders accountable to the numbers they quoted.
Taking the time to line up your offers is not busywork; it is the single most reliable way to avoid overpaying on a loan you will live with for years. Gather your estimates, build your scorecard, ask the hard questions, and let the numbers guide you to the mortgage that truly fits your financial life.