How to Use a HELOC to Pay for a Home Renovation in 2026
Learn how to use a HELOC to pay for a home renovation, from managing draw periods to budgeting for variable rates and coordinating contractor payments.
By Grace Parker
You have finally decided to turn that dated kitchen into the gathering space you have always wanted, or maybe the bathroom remodel has moved from wish list to must do. The plans are drawn, the contractor is chosen, and then the estimate lands: a number large enough to make you pause. Tapping into your home equity with a home equity line of credit, or HELOC, is one of the most flexible ways to fund a major renovation without draining your savings or putting every expense on a high-interest credit card. But a HELOC is not a magic wand. It is a revolving line of credit secured by your home, and how you use it, from the first draw to the final repayment, determines whether it becomes a smart financial tool or a source of stress. This guide walks you through exactly how to use a HELOC to pay for a home renovation, including the draw period, repayment mechanics, variable rate budgeting, contractor coordination, and when a fixed-rate home equity loan might be the simpler path.
Understanding the HELOC Structure: Draw Period and Repayment Period
A HELOC is different from a standard loan in a fundamental way: it is a line of credit, not a lump sum. During the draw period, which typically lasts 10 years, you can borrow money as you need it, repay some or all of it, and borrow again, up to your credit limit. This is why HELOCs pair so well with renovations, because renovation costs rarely arrive all at once. You might pay a design deposit in month one, framing and demolition in month two, cabinets and countertops in month three, and final labor and fixtures in month four. A HELOC lets you draw funds in stages and only pay interest on what you actually use, not on the entire approved limit.
During the draw period, many HELOCs require interest-only payments. That means your monthly payment could be relatively small at first, which feels comfortable. But here is the critical point: interest-only payments do not reduce your principal balance. When the draw period ends, the loan enters the repayment period, typically 10 to 20 years, during which you must repay both principal and interest. Your monthly payment can jump significantly at that transition. Homeowners who use a HELOC for a renovation must plan for that payment increase from day one, not treat the interest-only phase as a permanent arrangement.
Think of the draw period as a construction phase and the repayment period as the long-term ownership phase. During construction, you are managing cash flow. During repayment, you are managing debt service. A renovation funded by a HELOC should be budgeted across both phases, not just the exciting part when the work is happening. If your renovation takes six months, you have roughly nine and a half years of draw period left before repayment begins, and that is your window to pay down principal aggressively if you want to soften the payment shock later.
How Variable Rates Affect Your Renovation Budget
Most HELOCs come with variable interest rates, which means the rate can rise or fall over time based on an index such as the prime rate. When the Federal Reserve changes rates, your HELOC rate often follows, and your monthly payment changes with it. For a renovation budget, this introduces uncertainty. You might qualify for a HELOC at an attractive introductory rate, only to see the rate climb during the project or shortly after. That does not mean a HELOC is a bad choice, but it does mean you need a buffer.
A practical approach is to budget your renovation as if the rate were one or two percentage points higher than your current quoted rate. If the project estimate is $80,000 and your current rate is 8 percent, calculate what the interest cost would be at 9 or 10 percent. If the higher figure still fits comfortably within your monthly cash flow, you have a realistic plan. If it does not, consider reducing the scope of the renovation, increasing your cash contribution, or choosing a fixed-rate home equity loan instead. You can also ask your lender whether a rate cap or conversion feature is available, which would let you lock in a fixed rate on all or part of your balance.
Variable rates are not inherently dangerous, but they require active management. Set a calendar reminder to review your HELOC statement each month and note the current rate. If rates trend upward for several consecutive months, adjust your discretionary spending or accelerate principal payments to keep the overall cost of the renovation in check. The homeowners who get into trouble with HELOCs are usually the ones who ignore the rate changes until the payment becomes unmanageable.
Coordinating Contractor Draws and Permits with Lender Requirements
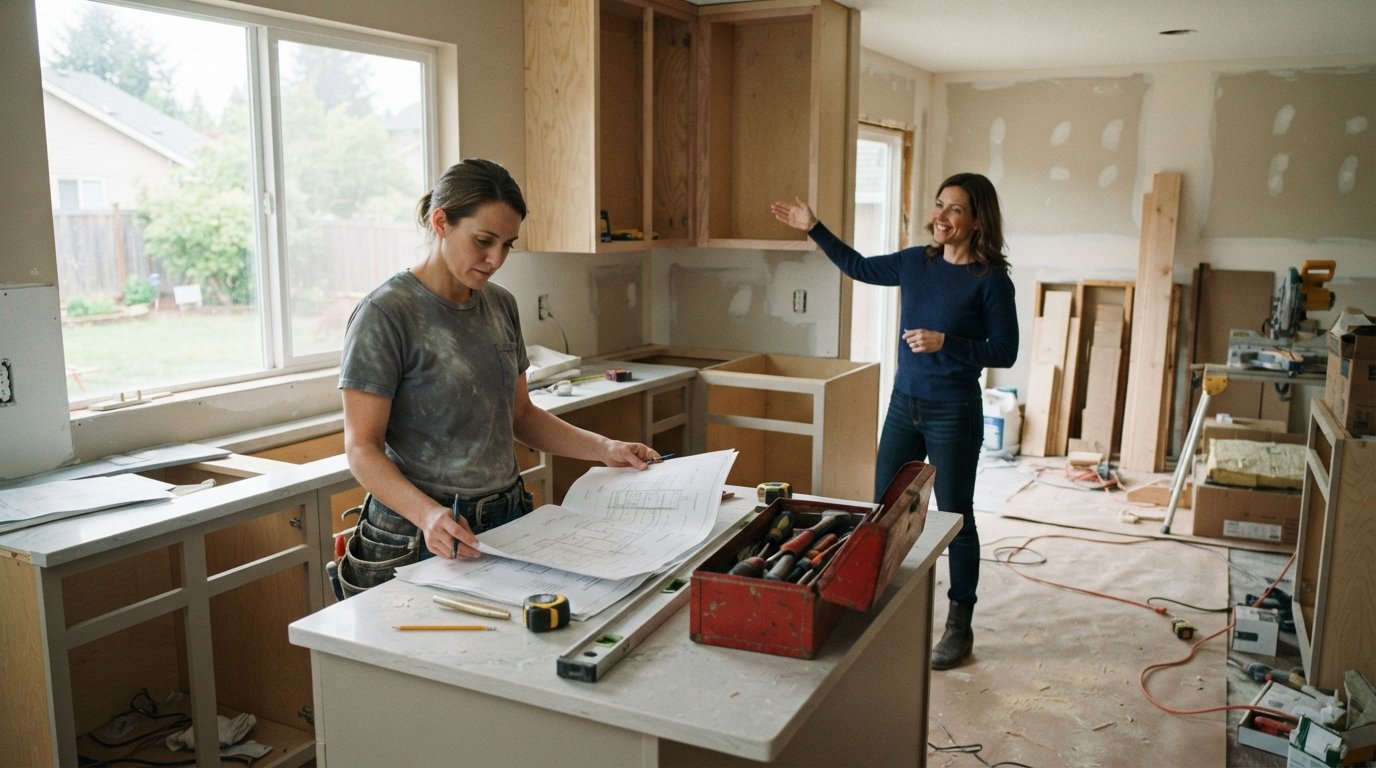
One of the most practical aspects of how to use a HELOC to pay for a home renovation is coordinating the flow of money with the flow of work. Contractors typically require payments at specific milestones, such as a deposit at signing, a payment when materials are delivered, and progress payments as phases are completed. Your lender, meanwhile, may have its own requirements for how funds are disbursed, especially if the HELOC is being used for a large project. Some lenders allow you to draw funds directly, while others may require documentation of the work completed before releasing larger amounts.
Before the first hammer swings, have a clear conversation with your contractor about the payment schedule and share it with your lender if needed. A typical draw schedule for a renovation might look like this:
- Deposit at contract signing: 10 to 20 percent of the project cost
- Rough-in and framing completion: 20 to 30 percent
- Mid-project progress payment: 20 to 30 percent
- Final completion and walkthrough: the remaining balance, minus any holdback
Permits are another coordination point. Structural changes, electrical work, plumbing modifications, and additions almost always require permits, and the inspection process can affect the timeline. If your contractor needs to pull permits before starting, make sure the HELOC funds are available for the permit fees and any associated design or engineering costs. Delays in permit approval can stretch the project timeline, which means you may be paying interest on drawn funds for longer than expected. Build a contingency of 10 to 15 percent into your renovation budget to cover permit delays, change orders, and material price fluctuations.
Keep detailed records of every draw and every payment to your contractor. This protects you if there is a dispute and helps you track how much of your HELOC limit remains available. If your lender requires inspections or lien waivers before releasing funds, stay in close contact with your contractor to ensure those documents are ready when needed. The smoother your documentation, the faster your draws are processed.
When a Fixed-Rate Home Equity Loan Is the Simpler Choice
A HELOC is flexible, but flexibility is not always what you need. If your renovation has a fixed, well-defined cost and a clear timeline, a fixed-rate home equity loan may be the simpler and more predictable option. With a home equity loan, you receive a lump sum at closing, and you repay it over a set term at a fixed interest rate. Your monthly payment never changes, which makes budgeting straightforward. You do not have to manage draws, track variable rates, or worry about a payment reset when the draw period ends.
Consider a fixed-rate home equity loan if you are renovating a single room with a firm bid, if you are uncomfortable with variable rates, or if you plan to complete the project quickly and want the certainty of a fixed repayment schedule. A HELOC remains the better choice if your project is phased, if you are unsure of the final cost, or if you want the ability to borrow, repay, and borrow again during the draw period. Some homeowners use a hybrid approach: a fixed-rate home equity loan for the known core costs and a small HELOC as a contingency reserve for surprises. That combination can give you both stability and flexibility.
If you are comparing these options, it helps to understand how different loan products fit together. For instance, if you have VA loan benefits, our guide on VA loan reuse and multiple uses explains how eligibility works when you already have a VA mortgage, which can affect your overall borrowing strategy. And for a broader educational look at how home equity products fit into the mortgage landscape, you can explore the plain-language resources at MortgageDirectory, which explains loan terms, costs, and repayment structures without quoting rates or taking applications.
Step-by-Step: Using Your HELOC for a Renovation
Now that you understand the structure, here is a practical sequence for putting a HELOC to work on your renovation. Following these steps helps you avoid common mistakes and keeps your project financially organized from start to finish.
- Confirm your available equity. Most lenders allow you to borrow up to 80 or 85 percent of your home's appraised value minus your existing mortgage balance. Get a current appraisal or use your lender's estimate to know your true ceiling.
- Get quotes and set a realistic budget. Obtain at least three contractor bids, add a 10 to 15 percent contingency, and compare that total to your HELOC limit. Do not borrow the full limit just because it is available.
- Apply and close on the HELOC. The application typically requires income verification, a credit check, and an appraisal. Closing costs may be minimal, but ask about annual fees, early closure penalties, and draw period terms.
- Create a draw schedule with your contractor. Align each draw with a completed milestone and share the schedule with your lender if required. Keep receipts and invoices for every draw.
- Monitor your rate and payment. Review your statement monthly, note rate changes, and make principal payments when possible during the draw period to reduce the repayment shock later.
After the renovation is complete, take a moment to reassess your HELOC balance and your repayment plan. If the project came in under budget, you may have unused funds available, which you can leave untouched or use for a future project. If the project went over budget, identify which costs exceeded expectations and adjust your repayment timeline accordingly. The goal is to exit the draw period with a balance you can comfortably repay, not to carry the maximum debt for the full term.
Key Risks and How to Manage Them
A HELOC is secured by your home, which means the lender can foreclose if you fail to repay. That is the most serious risk, and it is why responsible borrowing matters. Beyond foreclosure, there are other risks to manage. Variable rates can increase your payment. Interest-only payments can create a false sense of affordability. And using a HELOC for renovations that do not add value can leave you underwater on your home equity. Not every renovation returns its cost at resale, so prioritize projects that improve functionality, energy efficiency, or structural integrity over purely cosmetic upgrades if you are concerned about resale value.
Another risk is over-borrowing. It is tempting to borrow the full approved limit and upgrade finishes, add features, or expand the scope. But every dollar you draw is a dollar you must repay with interest. A disciplined approach is to set a hard budget before you apply, stick to it, and treat the HELOC limit as a maximum, not a target. If you are unsure how much you can comfortably afford, use an online mortgage calculator to estimate monthly payments at different rates and balances. Express Mortgage Quotes offers educational tools and a quote comparison service that can help you see how HELOC terms and payments vary among lenders, so you can make an informed decision before you commit.
Finally, communicate with your lender if your financial situation changes. If you lose income or face an unexpected expense during the renovation, contact your lender early to discuss options. Many lenders offer hardship programs or payment modifications, but those options are far more accessible before you miss a payment than after. A HELOC is a financial tool, and like any tool, it works best when used with intention and foresight.
Using a HELOC to pay for a home renovation can be a smart way to improve your home while preserving your savings and maintaining liquidity. The key is to understand the draw and repayment periods, budget for variable rate changes, coordinate contractor draws carefully, and know when a fixed-rate home equity loan might serve you better. With a clear plan and disciplined execution, your renovation can add both comfort and value to your home without creating financial strain.