Jumbo Loan Refinancing Requirements for High Value Homes
Jumbo loan refinancing requirements for high value homes demand strong credit, low DTI, and ample reserves. Learn how to qualify and save on your mortgage.
By Olivia White
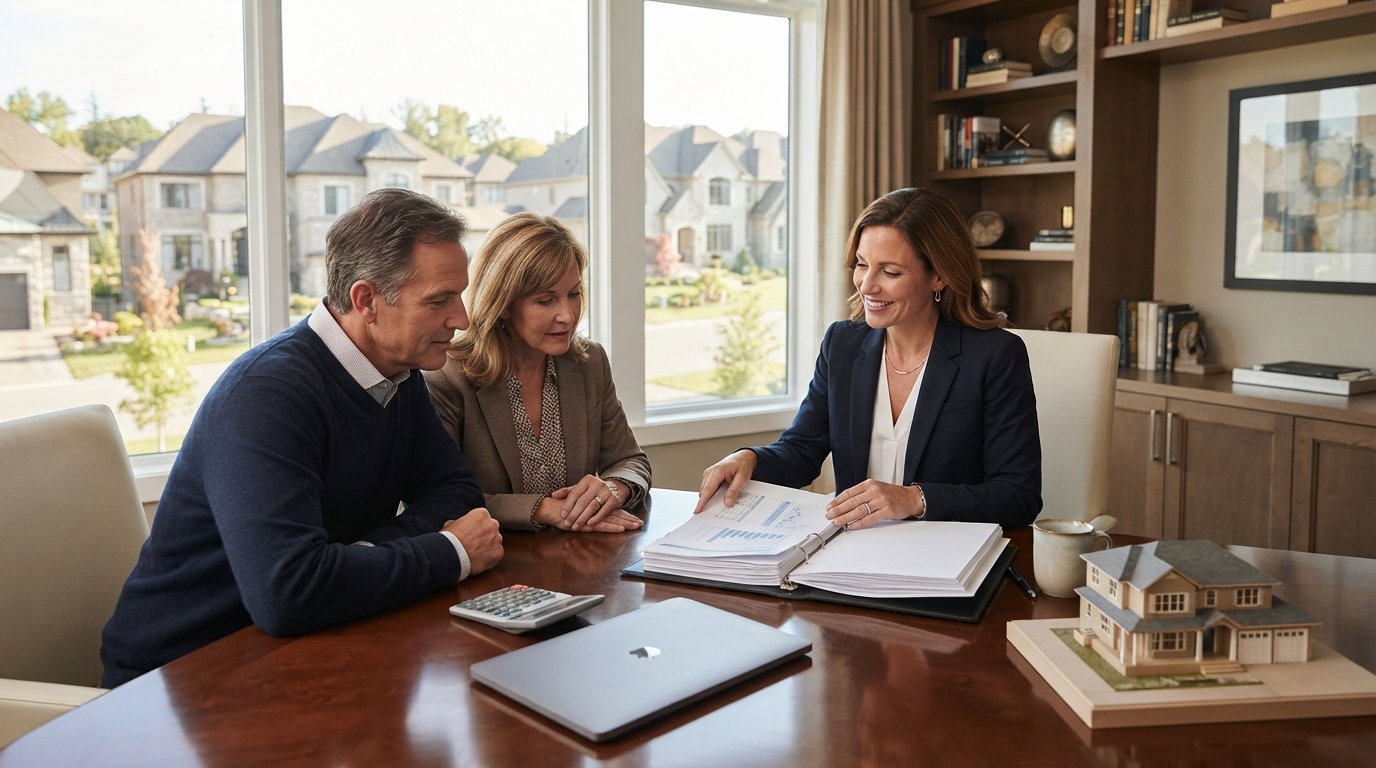
Refinancing a high value home comes with a distinct set of rules, and the stakes are higher when the loan amount climbs above the conforming limit. If you own a property worth well over a million dollars, or you are carrying a mortgage that exceeds the standard loan caps set by Fannie Mae and Freddie Mac, you are likely dealing with a jumbo loan. Understanding the jumbo loan refinancing requirements for high value homes is the first step toward lowering your rate, shortening your term, or tapping into equity without derailing your financial plan. This article breaks down how lenders evaluate these larger loans, what documentation you will need, and how to position yourself as a strong candidate in a competitive market.
What Makes a Jumbo Loan Different From a Conforming Loan
A jumbo loan is any mortgage that exceeds the conforming loan limits established each year by the Federal Housing Finance Agency. For 2026, the baseline conforming limit for a single-family home in most U.S. counties is $806,500, though high-cost areas like San Francisco, New York, and parts of Colorado have limits that stretch above $1.2 million. Anything above that threshold is considered jumbo, and that classification changes nearly everything about how a lender evaluates your refinance application.
The biggest difference is that jumbo loans are not backed by Fannie Mae or Freddie Mac. That means lenders carry the risk on their own books, so they compensate by demanding stronger credit, larger reserves, and more thorough documentation. You will not find the same streamlined processes that exist for conforming refinances, and you will not qualify for government-backed programs like FHA or VA refinancing on a jumbo amount (though some VA jumbo options exist, they come with their own strict rules).
Another key distinction is the appraisal process. High value homes often have unique features, larger lots, or custom construction that make valuation more complex. Lenders typically require a full appraisal, and in some cases a second appraisal or a desk review, before they will approve a jumbo refinance. This adds time and cost to the process, but it also protects you from overpaying on interest based on an inflated property value.
Core Jumbo Loan Refinancing Requirements for High Value Homes
When you apply to refinance a jumbo loan, lenders look at a combination of credit, income, assets, and property characteristics. The exact thresholds vary by lender, but most follow a similar framework. Meeting these requirements does not guarantee approval, but falling short in any one area will almost certainly trigger a denial or a higher interest rate.
Here are the primary requirements you should expect to satisfy:
- Credit score: Most jumbo lenders require a minimum FICO score of 700, with the best rates reserved for borrowers at 740 or higher. Some portfolio lenders will go down to 680, but you will pay a premium.
- Debt-to-income ratio (DTI): Lenders typically want your total monthly debt payments, including the new mortgage, to stay below 43% of your gross monthly income. Some allow up to 45% or even 50% if you have substantial reserves.
- Loan-to-value ratio (LTV): For a rate-and-term refinance, you can often borrow up to 80% of your home's appraised value. Cash-out refinances usually cap at 70% or 75% for jumbo loans.
- Cash reserves: You will likely need to show six to twelve months of mortgage payments in liquid assets after closing. The exact amount depends on your loan size and the lender's risk tolerance.
- Documentation: Full income verification, including W-2s, tax returns, and recent pay stubs, is standard. Self-employed borrowers may need two years of returns and a profit-and-loss statement.
Beyond these baseline numbers, lenders will scrutinize the property itself. High value homes in declining markets, areas prone to natural disasters, or with non-conforming features (like a commercial vineyard or an unpermitted addition) can complicate the refinance. It helps to work with a lender who regularly handles jumbo loans in your specific market, because they will know how to navigate local appraisal quirks and underwriting overlays.
How to Prepare Your Financial Profile Before You Apply
Preparation is where most jumbo refinance applications either succeed or stall. Because the loan amounts are large, lenders have little tolerance for ambiguity. A missing document or an unexplained deposit can push your file into a lengthy review queue. Start gathering your paperwork at least 60 days before you plan to apply.
Your first task is to pull your credit reports from all three major bureaus and dispute any errors. Even a small collection account or a late payment from years ago can drag your score below a lender's threshold. Pay down revolving balances to lower your credit utilization ratio, and avoid opening new credit lines or financing a car during the refinance process. Lenders will re-pull your credit just before closing, and a new inquiry can change your pricing.
Next, organize your income and asset documentation. You will need recent pay stubs covering at least 30 days, W-2 forms for the past two years, and personal and business tax returns if you own more than 25% of a company. For assets, gather statements for checking, savings, brokerage, and retirement accounts. If you are using gift funds for closing costs or reserves, you will need a gift letter and proof of transfer.
Finally, consider the timing of your refinance relative to your broader financial goals. If you are also planning a major home renovation or a career change, it may be wiser to wait until your income and debt profile are stable. A jumbo refinance is a significant transaction, and lenders want to see consistency. If you are comparing lenders, a resource like Home Loan Comparison Online: A Smarter Way to Save can help you understand how different offers stack up before you commit.
Appraisal and Property Requirements for High Value Homes
The appraisal is often the most unpredictable part of a jumbo refinance. Unlike conforming loans, where automated valuation models can sometimes replace a full appraisal, jumbo lenders almost always require a physical inspection by a licensed appraiser. For high value homes, that appraiser needs experience with luxury properties, because standard comparable sales may not reflect unique features like guest houses, tennis courts, or waterfront access.
Lenders will also look at the property's condition and marketability. A home that is over-improved for its neighborhood, meaning it is significantly more expensive than surrounding properties, can be harder to finance. The same applies to homes with mixed-use elements, such as a residential property with a commercial storefront on the ground floor. In these cases, you may need to seek out a portfolio lender who holds loans on their own books and can apply more flexible underwriting standards.
If your home is in a high-risk area for wildfires, floods, or hurricanes, the lender will require proof of adequate insurance, including flood insurance if the property is in a designated flood zone. In some coastal markets, lenders may also require a windstorm policy or an earthquake endorsement. These costs add up, so factor them into your closing cost estimate before you lock your rate.
Cash-Out Refinancing vs. Rate-and-Term Refinancing for Jumbo Loans
Jumbo borrowers typically refinance for one of two reasons: to lower their interest rate and monthly payment (rate-and-term), or to access equity for other financial goals (cash-out). Each path has different requirements and trade-offs.
A rate-and-term refinance is the simpler option. You replace your existing mortgage with a new one at a lower rate or a different term, and you do not take any cash out. Lenders generally allow LTVs up to 80% for this type of loan, and the documentation is more straightforward. If your goal is to reduce your monthly payment or pay off your loan faster, this is usually the best route.
A cash-out refinance lets you borrow more than your current mortgage balance and pocket the difference in cash. For jumbo loans, cash-out LTV limits are stricter, often capped at 70% or 75%. You will also pay a higher interest rate than you would on a rate-and-term refinance, because the lender is taking on more risk. Use a cash-out refinance only if you have a clear plan for the funds, such as consolidating high-interest debt, funding a home improvement project, or covering a major expense. It is not a good idea to cash out equity simply to have extra spending money.
If you are exploring cash-out options, it helps to compare offers from multiple lenders. You can use a platform like RateChecker to see real-time mortgage rate comparisons and understand how different loan products might affect your payment. Just remember that any rate you see is illustrative and subject to change, so confirm current terms directly with a licensed lender.
Common Pitfalls That Delay or Derail a Jumbo Refinance
Even well-qualified borrowers run into problems during a jumbo refinance. One of the most common is a low appraisal. If the appraised value comes in below what you expected, your LTV ratio rises, and you may no longer qualify for the rate or loan amount you wanted. You can sometimes challenge a low appraisal with additional comparable sales, but the process takes time and is not guaranteed to succeed.
Another pitfall is a change in income or employment. Lenders verify your employment again just before closing. If you switch jobs, take a pay cut, or become self-employed during the process, your loan could be denied. If you are planning a career change, wait until after your refinance closes.
Finally, do not overlook the cost of closing. Jumbo refinances often come with higher origination fees, appraisal costs, and title insurance premiums because the loan amount is larger. Ask your lender for a Loan Estimate within three business days of applying, and compare that estimate to the Closing Disclosure you receive before closing. If the numbers do not match, ask questions. Being proactive about costs can save you thousands of dollars over the life of the loan.
Frequently Asked Questions About Jumbo Refinancing
Can I refinance a jumbo loan with less than 20% equity?
It is possible, but you will face stricter requirements. Some lenders allow jumbo rate-and-term refinances up to 90% LTV, but you will pay a higher rate and likely need a larger cash reserve. Cash-out refinances above 75% LTV are rare in the jumbo market.
How long does a jumbo refinance take?
Expect 45 to 60 days from application to closing, though complex appraisals or additional underwriting reviews can extend that timeline. Having your documentation ready upfront can help speed things along.
Do I need to pay mortgage insurance on a jumbo loan?
Most jumbo loans do not require private mortgage insurance, even if your down payment or equity is less than 20%. Instead, lenders may charge a higher interest rate or require additional reserves.
Can I refinance a jumbo loan into a conforming loan?
Yes, if your loan balance has fallen below the conforming limit for your county, or if you pay down the balance to bring it under the limit. This can help you access more competitive rates and streamlined programs.
Refinancing a high value home is not a one-size-fits-all process. The requirements are stricter, the paperwork is more extensive, and the margin for error is smaller. But with careful preparation and a clear understanding of what lenders expect, you can secure a refinance that lowers your costs and aligns with your long-term financial goals. Start by reviewing your credit and income documentation, then compare offers from multiple lenders to find the best fit for your situation.