Mortgage Closing Table: Step by Step Walkthrough
Understand what happens at a mortgage closing table step by step, from reviewing the Closing Disclosure to signing and funding, so you can avoid surprises and get your keys faster.
By Astoria Contributor
You have survived the house hunt, the inspection, the appraisal, and the underwriting maze. Now comes the moment of truth: sitting at the closing table. For many buyers, this final step feels like a black box. What actually happens when you sign all those papers? Who will be in the room? How long will it take, and when do you finally get the keys? Understanding what happens at a mortgage closing table step by step removes the mystery and helps you spot potential problems before they delay your move. This guide walks you through the closing day sequence in plain English, from the documents you will review to the moment the home officially becomes yours.
Before You Sit Down: The Closing Disclosure Review
Your closing table experience really begins three business days before the meeting. Federal law requires your lender to provide a Closing Disclosure, a five-page form that itemizes every cost, loan term, and party involved in the transaction. You should compare it line by line with the Loan Estimate you received when you applied. Look for changes in your interest rate, origination charges, and any new fees that were not disclosed earlier. If something looks off, call your loan officer immediately. Catching errors now is far easier than trying to fix them while a notary waits for your signature.
Pay special attention to the sections that affect your bottom line: the loan terms, projected payments, and the cash to close figure. The cash to close is the amount you must bring to the table, usually via wire transfer or a cashier's check. Confirm with your settlement agent how and when they need the funds. Many closing delays happen because the wire transfer did not arrive on time. For a broader overview of the entire closing process, including what happens before and after the table, see our guide on the mortgage closing process in 7 clear steps.
Who Attends the Closing and What They Do
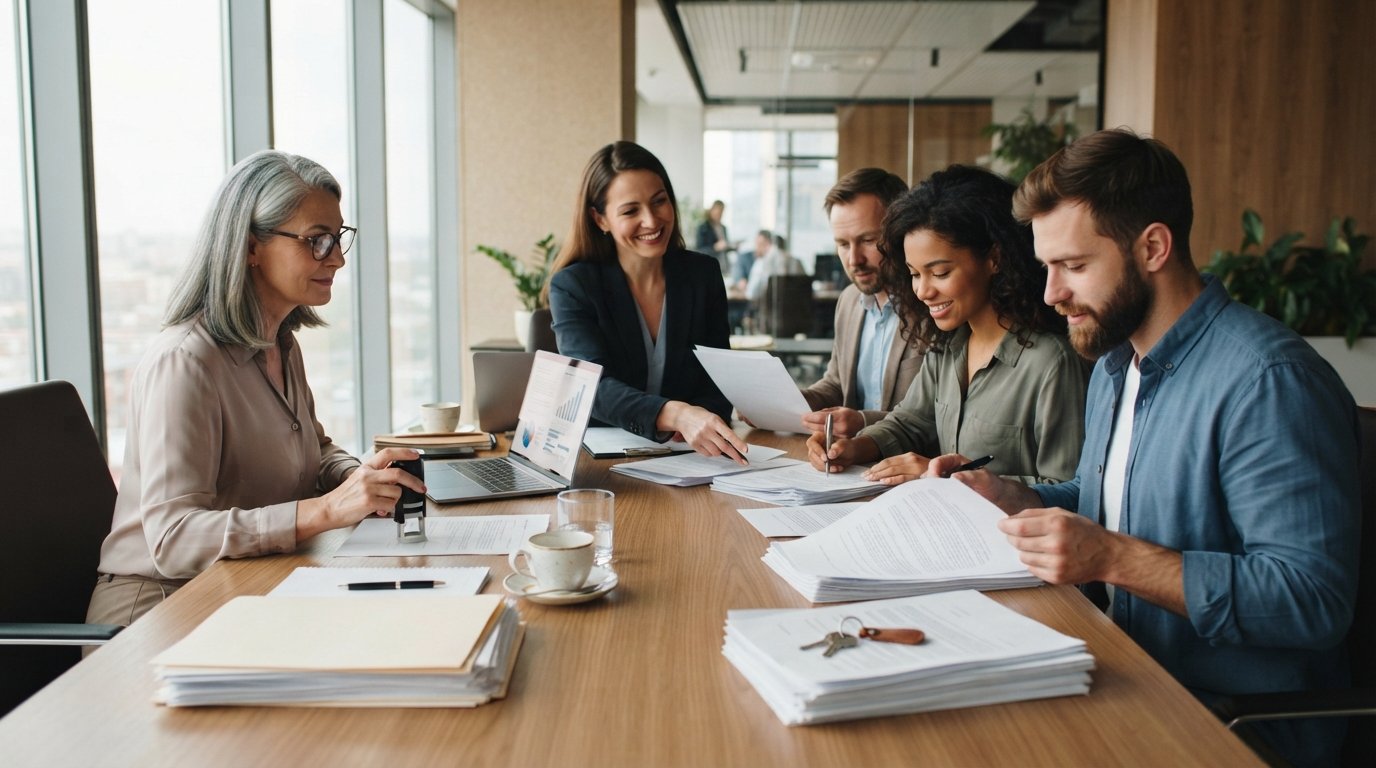
The cast of characters at a typical closing varies by state and lender, but you can expect a few key players. The settlement agent or closing attorney runs the meeting and handles the paperwork. Your real estate agent may be present to answer questions and ensure everything moves smoothly. The seller and their agent often attend a separate closing or join via remote signing. A title company representative verifies that the property is free of liens and that ownership transfers cleanly. Finally, a notary public witnesses your signatures and stamps the documents.
In some states, an attorney is required to conduct the closing; in others, an escrow officer or title agent handles it. Your lender will not usually attend in person, but they may send a representative or be available by phone. The atmosphere is businesslike but not intimidating. Everyone in the room has one goal: to transfer ownership and fund the loan. Knowing who does what helps you ask the right questions if something seems unclear.
The Signing Sequence: What Gets Signed and How Long It Takes
Once everyone is seated, the settlement agent will walk you through the documents in a specific order. The signing typically starts with the Closing Disclosure, which you will sign to acknowledge receipt. Next comes the promissory note, the legal promise to repay the loan. Then you will sign the mortgage or deed of trust, which gives the lender a security interest in the property. After that, you will sign the deed, transferring ownership from the seller to you. Additional documents include the initial escrow statement, the title affidavit, and various disclosures required by federal and state law.
How long does it take? A straightforward closing with no surprises usually lasts 45 to 90 minutes. If you are buying with a VA loan, there may be a few extra documents, such as the Certificate of Eligibility and the VA Loan Summary. If you are a first-time buyer, expect the agent to explain each page carefully, which can extend the meeting. Sellers often sign their portion separately or earlier in the day, so you may not need to wait for them. The notary will ensure every signature is properly witnessed and dated.
Funding Timelines and When You Get the Keys
Signing is not the same as funding. After all documents are executed, the settlement agent returns them to the lender for a final review. The lender then disburses the loan funds, usually via wire, to the settlement agent. This funding step can happen the same day or the next business day, depending on the lender and the time of day. Once the funds are received and the deed is recorded with the county, the transaction is complete. Only then does the seller release the keys.
In practice, many buyers receive keys at the closing table if the lender has pre-funded the loan or if the settlement agent is authorized to disburse immediately. However, it is common to wait a few hours or until the next day. Your closing agent will tell you exactly when to expect the keys. Plan your move accordingly, and do not schedule movers on the same day unless you have confirmed that funding will occur before they arrive. If you are refinancing rather than purchasing, there are no keys to exchange; the process concludes when the loan funds and the old mortgage is paid off.
For a deeper look at loan options and to compare rates from multiple lenders, you can use resources like LoanFinancing, which offers educational tools and calculators to help you estimate payments and understand financing choices.
Common Last-Minute Issues and How They Are Resolved
Even the most prepared buyers can encounter hiccups at the closing table. The most frequent issue is a discrepancy in the Closing Disclosure, such as an unexpected fee or a change in the loan amount. The settlement agent can often resolve this by contacting the lender for a corrected disclosure, but it may delay signing. Another common problem is missing documentation, like a proof of insurance or a cleared cashier's check. Reviewing your closing checklist the day before can prevent these snags.
Wire fraud is a growing concern. Scammers sometimes send fake wiring instructions that look legitimate. Always verify wiring details by calling your settlement agent at a known phone number, never by using contact information from an email. If you suspect fraud, stop the transfer immediately and notify your bank. Title issues, such as an undisclosed lien or a missing signature from a previous owner, can also surface. The title company will work to resolve them, but it may require a delay of a few hours or days. Knowing these possibilities helps you stay calm and focused on the finish line.
Finally, remember that closing costs can vary. It is wise to request a final Closing Disclosure at least three days before closing and to ask questions about anything that seems unfamiliar. For personalized quotes and to connect with verified lenders, consider using the tools at Express Mortgage Quotes. They provide educational articles, a mortgage calculator, and a quote comparison service to help you make informed decisions.
Closing day does not have to be stressful. By understanding the sequence of events, reviewing your documents in advance, and knowing who to ask when something seems off, you can sit down at the table with confidence. Whether you are buying your first home or refinancing an existing loan, the closing table is simply the final step in a process you have already mastered.