Mortgage Payment Breakdown: Principal, Interest, Taxes, Insurance
See exactly what your monthly payment covers, from principal and interest to escrow for taxes and insurance, so you can budget with confidence.
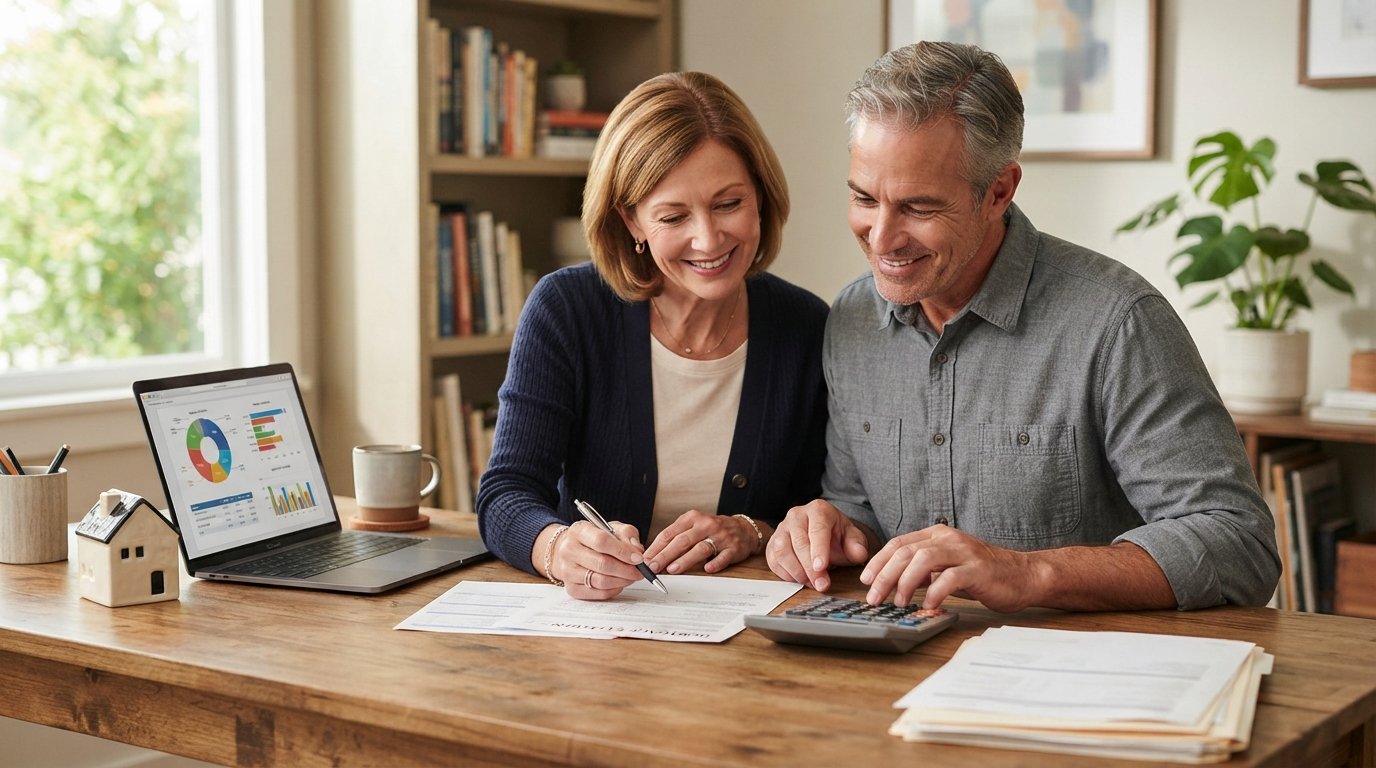
Your monthly mortgage payment is rarely just a payment on the loan itself. For most homeowners, that single check also covers property taxes and homeowners insurance, and understanding how those pieces fit together is the key to budgeting without surprises. Lenders call this combined payment PITI, and once you know what each letter represents, you can predict how your payment might shift over time, why escrow accounts sometimes run short, and how to compare loan offers with confidence. Whether you are buying your first home or refinancing an existing loan, a clear mortgage payment breakdown of principal, interest, taxes, and insurance turns a confusing number into a plan you can manage.
What PITI Means and Why It Matters
PITI stands for principal, interest, taxes, and insurance. It is the standard way lenders estimate the true monthly cost of owning a home, and it often appears on Loan Estimates and closing disclosures. Principal and interest go to repaying the mortgage loan itself, while taxes and insurance are collected to cover obligations tied to the property. Lenders look at the full PITI figure when they calculate your debt-to-income ratio, so the taxes and insurance portions matter just as much as the loan payment when you apply for financing.
Understanding PITI also helps you compare offers fairly. Two loans with the same interest rate can produce different monthly payments if one lender estimates taxes or insurance differently, or if one requires mortgage insurance. Knowing how each component works lets you ask better questions and spot estimates that seem too low to be realistic.
Principal: Building Equity One Payment at a Time
The principal portion of your payment reduces the outstanding balance on your loan. In the early years of a fixed-rate mortgage, principal is the smallest slice of the payment because interest is calculated on a larger balance. As the loan matures, more of each payment goes toward principal and less toward interest. This is why your loan balance falls slowly at first and then more quickly over time.
Extra payments toward principal can shorten your loan term and reduce total interest paid. Even small additional amounts, applied consistently, can make a meaningful difference over the life of the loan. If you want to see how accelerated payments change your amortization schedule, our guide on how biweekly mortgage payments save interest walks through the mechanics and the math.
Interest: The Cost of Borrowing and Why Rates Matter
Interest is the lender's charge for lending you money, expressed as a percentage of the outstanding balance. On a fixed-rate mortgage, the interest rate stays the same for the life of the loan, so the interest portion of each payment declines gradually as the balance falls. On an adjustable-rate mortgage, the rate can change after an initial fixed period, which means the interest portion, and therefore your total payment, can rise or fall.
Even a small difference in interest rate can change your monthly payment significantly over a 30-year term. That is why comparing quotes from multiple lenders is worthwhile. An interactive mortgage calculator can show you how different rates translate into monthly payments and total interest, giving you a concrete basis for comparison before you speak with a lender.
Taxes: The Variable That Escrow Handles
Property taxes are assessed by local governments and fund services such as schools, roads, and public safety. The amount depends on your home's assessed value and your local tax rate, and it can change when the property is reassessed or when the tax rate is adjusted. Because taxes are not paid to the lender, they are typically collected monthly in an escrow account and disbursed to the tax authority when bills come due.
Escrow simplifies budgeting because you are not hit with a large tax bill once or twice a year. However, escrow estimates are based on prior tax records, and they can be inaccurate if the home was recently purchased or reassessed. If your escrow account runs short, your servicer may adjust your monthly payment or request a lump sum to cover the difference.
Insurance: Protecting the Home and the Lender's Interest
Homeowners insurance covers damage from events such as fire, storms, and certain liability claims. Lenders require it because the property serves as collateral for the loan. Like taxes, insurance premiums are often collected monthly in escrow and paid annually. Premiums can change at renewal based on claims history, construction costs, and the insurer's pricing, which means the insurance portion of your payment is not fixed forever.
If your down payment is less than 20 percent on a conventional loan, you may also pay private mortgage insurance (PMI), which protects the lender if you default. PMI is another variable component that can drop off once you build sufficient equity. FHA loans carry mortgage insurance premiums with different rules, and VA loans have their own funding fee structure. Each of these affects the total monthly payment in ways that a simple principal-and-interest calculation does not capture.
Fixed Versus Variable: Which Parts of Your Payment Change
Of the four components, principal and interest are the most predictable on a fixed-rate loan. The payment amount stays the same, though the internal split between principal and interest shifts over time. Taxes and insurance are the variable pieces: they can change at escrow analysis, at tax reassessment, or at insurance renewal. On an adjustable-rate mortgage, the interest portion joins the variable group after the initial fixed period.
Here is a simple way to think about which parts of your payment are stable and which require monitoring:
- Principal: Fixed payment on a fixed-rate loan; declines as a share of the payment over time.
- Interest: Fixed on a fixed-rate loan; can change on an adjustable-rate loan after the introductory period.
- Taxes: Variable; changes with reassessment and local tax rates, collected through escrow.
- Insurance: Variable; changes at renewal and if mortgage insurance applies, also collected through escrow.
Budgeting for the variable components is easier when you review your escrow statement each year and set aside a small cushion for increases. Many servicers require a minimum escrow balance, and shortages are typically spread over twelve months rather than collected all at once.
How Escrow Works and Why Payments Change After Analysis
An escrow account is a holding account your servicer uses to pay property taxes and insurance on your behalf. Each month, a portion of your payment goes into escrow. When tax bills and insurance premiums come due, the servicer pays them from the account. Once a year, the servicer performs an escrow analysis, comparing the projected costs with the actual bills and the account balance.
If the analysis shows a shortage, your monthly payment may increase to rebuild the balance. If it shows a surplus, you may receive a refund or a lower payment. Tax reassessments and insurance rate increases are the most common reasons payments change, and they can happen even when your loan terms have not changed at all. Reading the escrow analysis statement carefully helps you understand exactly why the number moved and what you can do about it.
Using a Mortgage Calculator to Model Payment Scenarios
A mortgage calculator is the fastest way to see how principal, interest, taxes, and insurance combine into a monthly payment. You can adjust the home price, down payment, interest rate, loan term, and estimated taxes and insurance to see how each variable affects the total. This is especially useful when you are deciding between loan types or comparing offers from different lenders.
For a more precise picture, consider modeling a few scenarios side by side. For example, compare a 30-year fixed loan with a 15-year fixed loan at the same rate, or compare a conventional loan with a low down payment against an FHA loan with mortgage insurance. The calculator will not replace a Loan Estimate, but it gives you a realistic range and helps you ask informed questions. You can also use a payment calculator from MortgageDirectory to cross-check your numbers and better understand how rates, costs, and loan terms interact before you talk with a lender.
Comparing Loan Offers With PITI in Mind
When you compare loan offers, look beyond the interest rate. Ask each lender for a Loan Estimate that shows the full PITI breakdown, including estimated taxes, insurance, and any mortgage insurance. A lower rate with higher fees or mandatory mortgage insurance may cost more over time than a slightly higher rate with lower upfront costs. The Consumer Financial Protection Bureau recommends comparing at least three offers, and the PITI breakdown is the best single number for an apples-to-apples comparison.
Remember that taxes and insurance estimates can vary between lenders for the same property. If one estimate seems unusually low, ask how it was calculated. A realistic estimate now prevents a payment shock later when escrow analysis catches up with actual costs.
Frequently Asked Questions About Mortgage Payment Breakdowns
Is PITI the same as my total monthly payment?
PITI covers principal, interest, taxes, and insurance, but it may not include homeowners association dues, mortgage insurance, or other escrow items. Review your Loan Estimate for the complete picture, including any optional add-ons.
Why did my payment go up even though my rate is fixed?
A fixed rate locks the interest portion, but taxes and insurance can change. An escrow analysis that shows a shortage, a property tax reassessment, or an insurance premium increase can raise your monthly payment even on a fixed-rate loan.
Can I pay taxes and insurance myself?
Some lenders allow you to waive escrow, usually for a fee or a slightly higher rate. If you choose this option, you are responsible for saving for and paying tax and insurance bills on time. Weigh the convenience of escrow against the discipline required to self-manage those expenses.
How does mortgage insurance fit into the breakdown?
Mortgage insurance protects the lender, not you, and it is added to your payment when required. On conventional loans, PMI can often be removed once you reach 20 percent equity. FHA and VA loans have different rules, so ask your lender how mortgage insurance applies to your specific loan.
Understanding the four pieces of your mortgage payment, principal, interest, taxes, and insurance, gives you control over your budget and confidence in your financing decisions. Review your escrow statements each year, use a mortgage calculator to model scenarios before you apply, and compare Loan Estimates carefully. When you are ready to explore options, Express Mortgage Quotes can connect you with verified lenders and help you compare quotes so you can choose the loan that fits your goals.