Mortgage Prequalification vs Preapproval: Key Differences
Learn how mortgage prequalification vs preapproval key differences affect your offer, budget, and timeline so you can shop with confidence.
By Alice Shaw
You have found the right neighborhood, your down payment is saved, and you are ready to make an offer. Then your real estate agent asks whether you have a prequalification or a preapproval letter. If you are not sure how to answer, you are not alone. These two terms sound similar, but they carry very different weight with sellers, agents, and lenders. Understanding mortgage prequalification vs preapproval key differences can mean the difference between a seller taking your offer seriously and your dream home slipping away.
This guide breaks down exactly what each step involves, how long each status lasts, and how to use them strategically to set a realistic home search budget. Whether you are a first-time buyer or returning to the market, knowing the distinction helps you move through the process with confidence and avoid costly surprises.
What Is Mortgage Prequalification?
Prequalification is an early, informal conversation with a lender. You provide basic financial information such as your income, assets, debts, and estimated credit score, and the lender gives you a rough estimate of how much you might be able to borrow. It usually does not require a hard credit pull, and many lenders offer it online in minutes at no cost. Because it is quick and light on documentation, prequalification is best seen as a starting point, not a green light.
The main value of prequalification is direction. It helps you understand your approximate price range before you start touring homes, which prevents wasted weekends looking at properties outside your budget. It also gives you a chance to spot obvious issues, such as a debt-to-income ratio that is higher than you expected, so you can address them early. For a deeper walkthrough of this step, see our guide on what mortgage prequalification involves and how to use it wisely.
However, prequalification is not a commitment from the lender, and it is not a promise of financing. The estimate is based on unverified information, so the final loan amount could change once documents are reviewed. Sellers and agents generally view a prequalification letter as a sign that you are exploring the market, not as proof that you can close.
What Is Mortgage Preapproval?
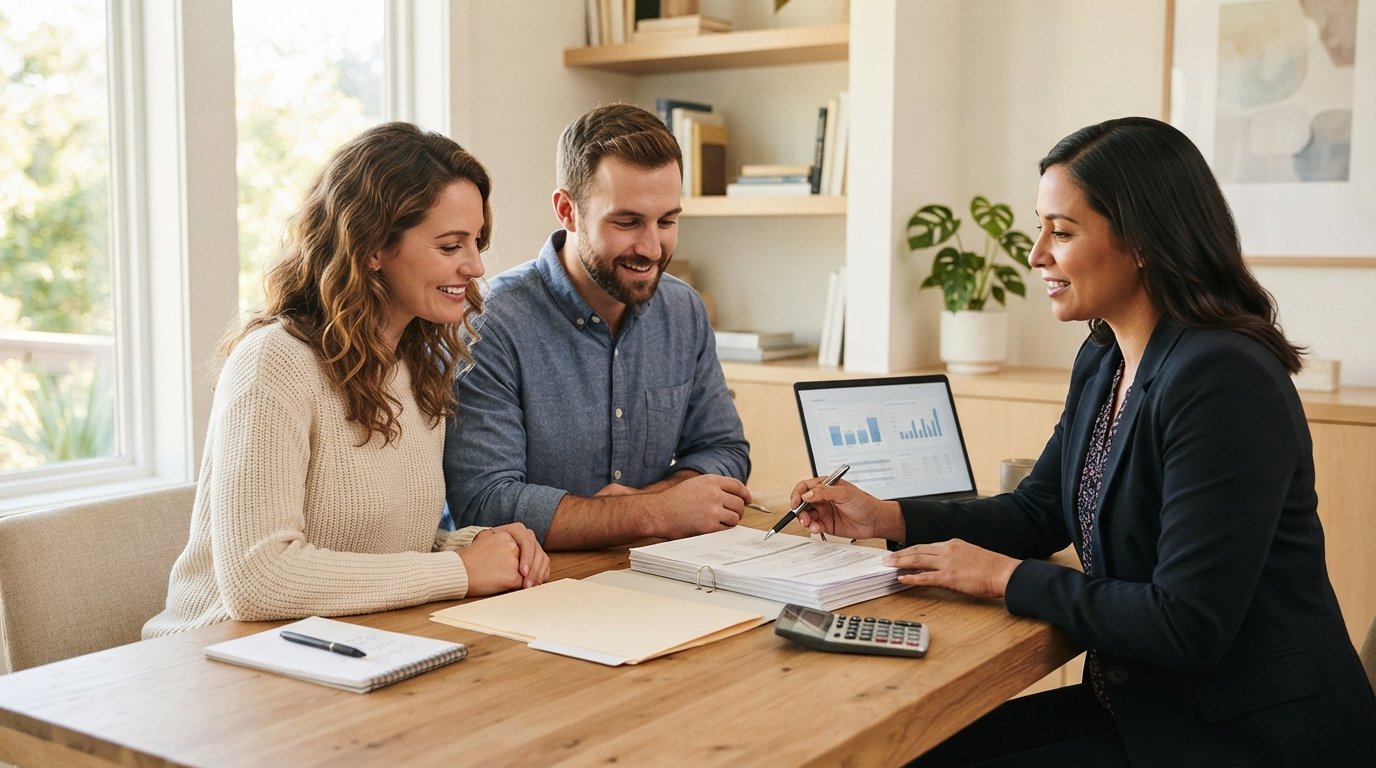
Preapproval is a much deeper review. You submit documented proof of income (pay stubs, W-2s, tax returns), bank statements, and identification, and the lender pulls your credit report. An underwriter then evaluates your full financial picture and issues a conditional commitment to lend up to a specific amount, subject to a satisfactory appraisal and clear title. This process can take several days to a couple of weeks, but the resulting letter carries real weight.
For sellers, a preapproval letter signals that a lender has already verified your finances. In competitive markets, listing agents often require one before they will even present an offer. A preapproval also helps you shop with precision: you know your maximum loan amount and can calculate your monthly payment with confidence. You can use an interactive mortgage calculator to translate that loan amount into a realistic housing budget that includes taxes, insurance, and other costs.
It is important to understand that preapproval is not a final approval. The lender still needs to verify the property and confirm that nothing has changed in your financial situation. But it is far stronger than prequalification, and it tells everyone involved that you are a serious, prepared buyer.
Key Differences at a Glance
To make the distinction concrete, here is a side-by-side comparison of the two steps:
- Credit check: Prequalification often uses a soft credit inquiry or none at all; preapproval involves a hard credit pull that can temporarily affect your score.
- Documentation: Prequalification relies on self-reported figures; preapproval requires pay stubs, tax returns, bank statements, and more.
- Verification level: Prequalification is an estimate; preapproval is an underwriter-reviewed conditional commitment.
- Weight with sellers: Prequalification is a nice-to-have; preapproval is often expected and can make or break an offer.
- Time and cost: Prequalification is quick and usually free; preapproval takes longer and may involve an application fee.
These differences matter most when you are competing for a home. A seller who sees a preapproval letter knows the buyer has already cleared a major hurdle. A prequalification letter, by contrast, leaves room for doubt, and in a multiple-offer situation, that doubt can cost you the house.
How Sellers and Real Estate Agents Treat Each
Real estate agents advise sellers to weigh offers partly on financing strength. An offer accompanied by a preapproval letter is generally treated as more credible because the buyer has documented income, assets, and creditworthiness. Some agents will call the lender to confirm the letter is current and legitimate. In hot markets, sellers may reject offers that come with only a prequalification, viewing them as less likely to close.
That does not mean prequalification is useless. It is a sensible first step, especially if you are months away from buying or still improving your credit. But once you are ready to make offers, most agents will strongly recommend upgrading to preapproval. If you are working with a buyer's agent, ask what they prefer to see before submitting an offer; their answer will tell you exactly what sellers in your market expect.
For buyers who want to move quickly, a preapproval also speeds up the closing timeline. The lender has already reviewed your file, so the remaining work is mostly property-related. That can make your offer more attractive on terms beyond price, such as a shorter closing period.
How Long Each Status Lasts and When to Refresh
Prequalification letters are typically valid for 30 to 90 days, though some lenders may extend them informally. Because they are based on unverified information, they carry less weight over time. If your financial situation changes (a new job, a raise, a large purchase), you should update your prequalification before relying on it.
Preapproval letters usually last 60 to 90 days, and many lenders allow a renewal with a fresh credit check and updated documents. The clock matters: if your preapproval expires while you are still shopping, you will need to refresh it before making an offer. Sellers and agents may ask for a letter dated within the last 30 to 60 days, so keep an eye on the calendar.
Here is a simple rule of thumb: refresh your preapproval whenever you are about to make an offer, after any major financial change, or if more than 60 days have passed since it was issued. Staying current prevents last-minute delays and signals to sellers that you are organized and ready to close.
How to Use Preapproval to Set a Realistic Home Search Budget
The maximum loan amount on your preapproval is not the same as a comfortable budget. Lenders calculate what you can borrow based on debt-to-income ratios and credit history, but they do not account for your lifestyle, savings goals, or tolerance for a higher monthly payment. Use the preapproval as a ceiling, then work backward to a number that feels sustainable.
Start by listing your monthly obligations: existing debts, child care, transportation, utilities, and savings. Subtract those from your take-home pay, then see what remains for a mortgage payment. A mortgage calculator can help you model different loan amounts and terms, including taxes and insurance. Aim for a payment that leaves room for maintenance, emergencies, and the rest of your life.
It also helps to get quotes from multiple lenders before you commit. Rates and fees vary, and a small difference in rate can change your monthly payment significantly over 30 years. Platforms like LoanFinancing offer educational resources and calculators that can help you compare scenarios and understand your options. The goal is not just to qualify for the largest loan possible, but to choose a payment you can live with comfortably.
Common Mistakes to Avoid
One frequent mistake is assuming prequalification is enough. It is a helpful first step, but it will not satisfy most sellers once you are ready to make an offer. Another is shopping for a home before either step, which can lead to disappointment when financing falls through. Get at least prequalified early, and upgrade to preapproval before you start serious house hunting.
Another pitfall is making big financial changes during the process. Opening new credit cards, changing jobs, or making large purchases can derail a preapproval. Lenders verify your finances again before closing, so keep your financial profile stable. If something changes, tell your lender immediately rather than hoping it goes unnoticed.
Finally, do not treat the preapproval amount as a spending target. Just because a lender says you can borrow a certain amount does not mean you should. A home is a long-term commitment, and a payment that stretches you thin can turn a dream into a burden. Choose a budget that supports your broader financial goals.
Frequently Asked Questions
Does prequalification hurt my credit?
Usually not. Many lenders use a soft inquiry for prequalification, which does not affect your score. Preapproval, however, involves a hard inquiry, which can cause a small, temporary dip. Multiple mortgage inquiries within a short window are typically treated as a single inquiry by scoring models, so it pays to shop rates within a few weeks.
Can I get preapproved without being prequalified?
Yes. Some lenders allow you to go straight to preapproval, especially if you have your documents ready. Prequalification is optional, though it can be a useful warm-up. If you are confident in your finances, you can skip it and apply for preapproval directly.
Which one should I get first?
Start with prequalification if you are early in the process or want a quick estimate. Move to preapproval when you are ready to make offers. Many buyers do both: prequalify to set a range, then preapprove to strengthen their offer.
Understanding the differences between prequalification and preapproval puts you in control of your home search. Prequalification gives you a starting point; preapproval gives you credibility and clarity. Use both strategically, keep your finances stable, and choose a budget that fits your life, not just the lender's maximum. With the right preparation, you can shop with confidence and make an offer that stands out for all the right reasons.