Mortgage Rate Lock Extension Cost and Timing Explained
Understand mortgage rate lock extension cost and timing so you can avoid surprise fees and keep your closing on track.
By Daniel Smith
The clock starts ticking the moment you lock your mortgage rate, and if closing day slips past that deadline, the cost can catch you off guard. Understanding how mortgage rate lock extension cost and timing work together is one of the most practical skills a borrower can develop during the home stretch of a purchase or refinance. A rate lock protects your interest rate for a set period, but it is not an indefinite promise. When delays happen (and they often do), you need to know what an extension costs, when it applies, and how to avoid paying for one at all.
How the Rate Lock Clock Starts and What Stalls Closing
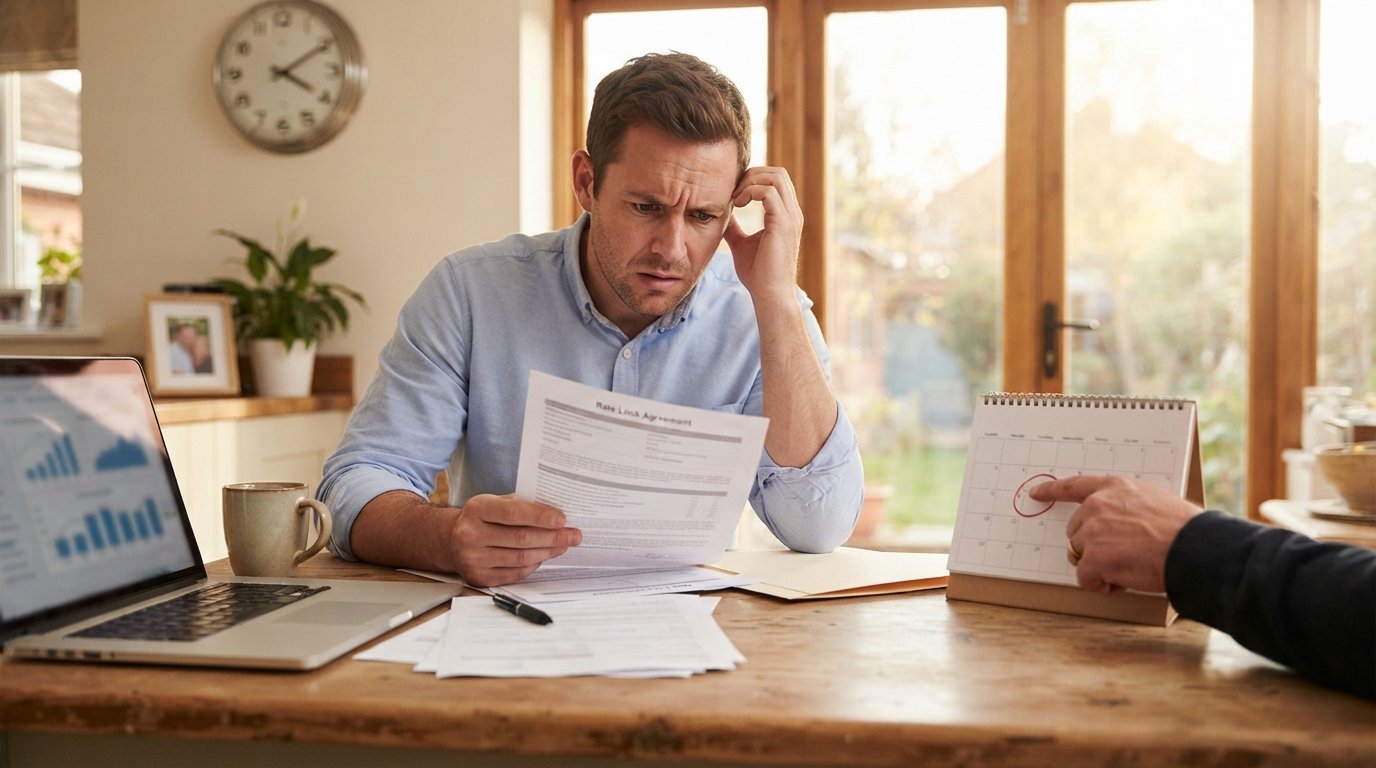
Your rate lock typically begins on the day your lender confirms the lock in writing, not the day you first applied. That distinction matters because the lock period, usually 30, 45, or 60 days, is measured from the confirmation date. Most lenders start the clock once all initial disclosures are signed and the loan is registered with the lock desk. If you are still shopping and comparing quotes, the lock date may not align with your application date, so always ask the lender to state the exact start and expiration date on the lock agreement.
Several common events can push closing past the lock expiration. Appraisal delays are among the most frequent culprits, especially in busy markets where appraisers are backed up. Missing or slow-to-arrive documents from the borrower, such as bank statements, tax returns, or letters of explanation, can also stall underwriting. Title issues, including unresolved liens, missing signatures, or survey problems, add days or weeks. Even a last-minute change to your loan terms or a switch in loan programs can reset the timeline. Understanding these bottlenecks helps you plan ahead and communicate with your loan officer before the deadline creeps up.
If you are still early in the process and want to understand how your rate fits into the bigger picture, our guide on low interest mortgage rates explains how qualification and timing interact. The key takeaway is that a rate lock is a contractual window, and every delay has a cost if it pushes you past that window.
How Extension Costs Are Published and Why They Vary by Lender
Mortgage rate lock extension costs are not standardized across the industry. Each lender publishes its own fee schedule, usually as a percentage of your loan amount or as a flat fee per day or per week. Some lenders charge a simple flat fee, for example $250 for a 15-day extension, while others charge 0.125% to 0.25% of the loan balance for a similar period. On a $300,000 loan, 0.125% equals $375, so the difference between lenders can be significant. These costs may be paid upfront, deducted from the loan proceeds, or added to your closing costs, depending on the lender's policy.
Lenders also differ in how they handle extensions when the delay is outside your control. Some offer a one-time courtesy extension at no charge if the delay is due to appraisal or title issues, while others charge regardless of fault. The fee structure can also change based on how close you are to the expiration date. Extending a lock that has already expired may cost more than extending it a few days before expiration. Always ask for the fee schedule in writing and confirm whether the extension cost can be rolled into the loan or must be paid out of pocket.
Because pricing and policies vary so widely, it pays to compare offers from multiple lenders. Express Mortgage Quotes connects you with verified lenders so you can compare rate lock terms side by side. You can also use the platform's mortgage calculator to estimate how an extension fee might affect your overall closing costs. For a broader look at financing tools and calculators, LoanFinancing offers educational resources that complement your lender research.
Common Reasons for Lock Expirations: Appraisal, Document, and Title Delays
Appraisal delays are the single most common reason locks expire. In a hot market, appraisers may be booked out two to three weeks, and if the appraisal comes in low or requires a second look, the timeline stretches further. Document delays are equally frustrating. Underwriters often request additional items after the initial review, such as updated pay stubs, gift letters, or explanations for large deposits. Each round of requests adds days. Title delays can be the most unpredictable, especially if the property has a complex ownership history, outstanding liens, or requires a survey or HOA certification.
Here are the most frequent culprits that push closings past the lock date:
- Appraisal scheduling backlogs or reconsideration of value requests
- Missing borrower documents or slow responses to underwriting conditions
- Title search issues, including liens, easements, or missing signatures
- Last-minute changes to loan terms or program switches
- HOA or condo document delays in condominium purchases
Understanding these risks allows you to take proactive steps. For example, you can order the appraisal early, gather documents in advance, and choose a lock period that matches the realistic closing timeline. If you are buying a condo, request HOA documents immediately. If you are refinancing, ensure your current lender responds quickly to payoff requests. The more you front-load these tasks, the less likely you are to face an extension fee.
Why You Must Confirm Extension Fees in Writing With Your Lender
Verbal promises about extension fees are not enforceable. Lenders are required to disclose loan terms in writing, and the rate lock agreement should specify the lock period, the extension fee schedule, and any conditions that could trigger a fee. Ask for the extension policy in writing before you lock, not after you are facing a deadline. The written agreement should state the cost per day or per week, the maximum extension period allowed, and whether the fee is refundable if the delay is the lender's fault. Keep a copy of this document with your closing paperwork.
If you are working with a mortgage broker or a lead-generation platform like Express Mortgage Quotes, confirm that the lender's written lock policy is part of your quote comparison. A reputable lender will provide a loan estimate and a separate lock agreement that clearly outlines the extension costs. If a lender hesitates to put the fee schedule in writing, consider that a red flag. Transparency is a key indicator of a trustworthy lending partner.
Finally, remember that an extension fee is not always the end of the world. In some cases, paying a small extension fee is cheaper than losing the rate and facing a higher interest rate for the life of the loan. Run the numbers: compare the extension fee to the increased monthly payment if rates rise. A $300 extension fee may be far less expensive than a 0.25% increase in your rate over 30 years. Use the mortgage calculator on Express Mortgage Quotes to model different scenarios and make an informed decision.
Strategies to Avoid or Minimize Extension Costs
The best way to avoid an extension fee is to choose a lock period that matches your realistic closing timeline. If you are buying a home and the seller needs a 60-day closing, do not lock for 30 days. If you are refinancing, ask your loan officer how long underwriting typically takes for your loan type. Build in a buffer of at least 10 to 15 days. You can also ask about float-down options, which allow you to get a lower rate if rates drop during the lock period, though these often come with their own fees.
Another strategy is to lock as late as possible while still protecting your rate. Some lenders allow you to lock after the appraisal is ordered or even after conditional approval, which shortens the lock period needed. However, this approach carries the risk that rates could rise before you lock. Weigh the trade-off carefully. If you are working with a lender that offers a free extension for appraisal delays, confirm the conditions in writing and document your communication.
If you are comparing lenders, ask each one about their extension policy and fee schedule as part of your quote comparison. Express Mortgage Quotes simplifies this by connecting you with multiple verified lenders who can provide written lock agreements. By understanding mortgage rate lock extension cost and timing, you can protect your budget and close with confidence. The key is to plan ahead, communicate openly with your lender, and get every fee commitment in writing.