Reverse Mortgage and Heirs: What Families Must Know
Reverse mortgage and heirs what family needs to know: learn how non-recourse rules protect heirs from inherited debt and how to keep or sell the home.
By Olivia White
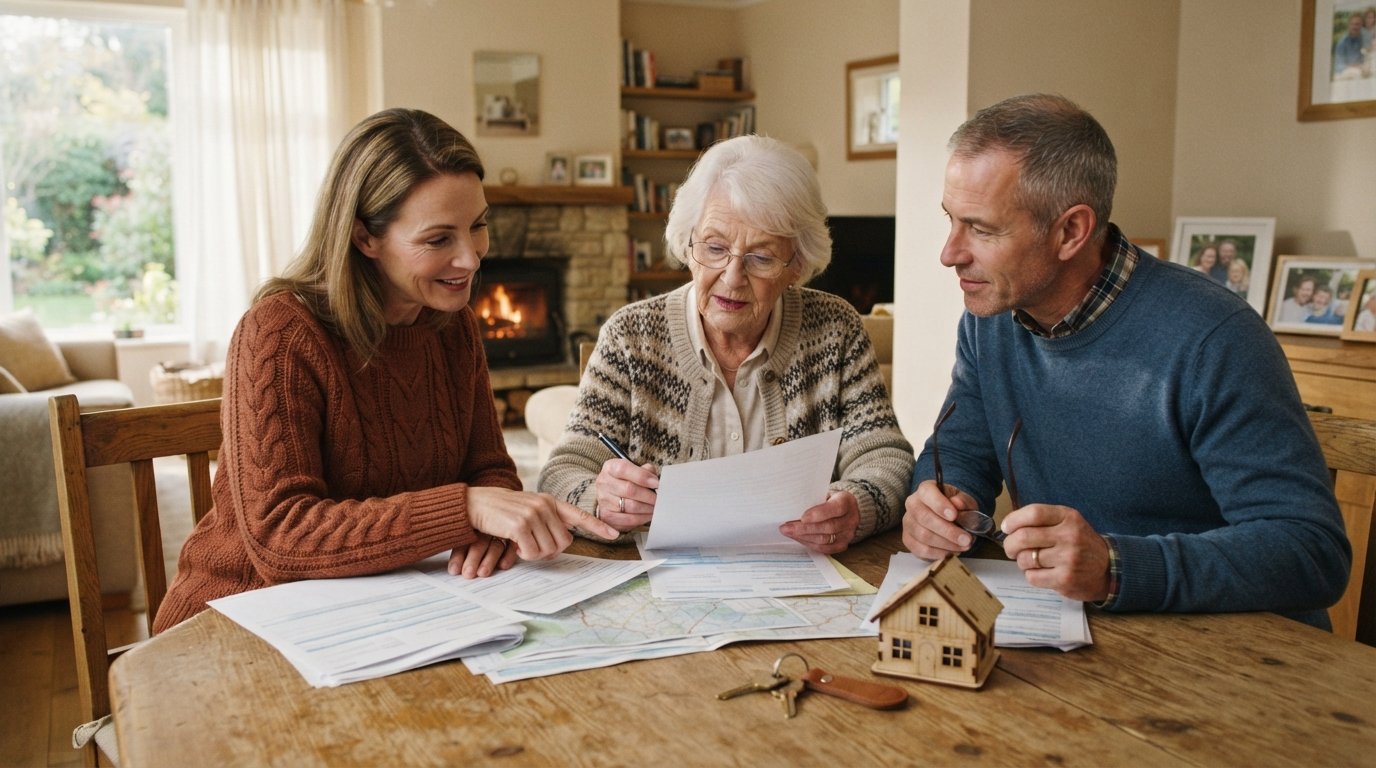
When a parent or grandparent takes out a reverse mortgage, the family often has more questions than answers. Will the bank take the house? Will there be a surprise bill? Can the heirs keep the home, or must they sell? These concerns are understandable, and the answers depend on a handful of rules that every family should understand before the loan closes, not after. This guide walks through how reverse mortgages affect heirs, what happens when the last borrower passes away or moves out, and the practical steps families can take to protect their options and their inheritance.
How a Reverse Mortgage Works and Why It Matters to Heirs
A reverse mortgage, most commonly a Home Equity Conversion Mortgage (HECM) insured by the FHA, allows homeowners aged 62 and older to convert part of their home equity into cash. Unlike a traditional mortgage, the borrower does not make monthly loan payments. Instead, the loan balance grows over time as interest and fees accrue, and the loan becomes due when the last borrower dies, sells the home, or permanently moves out.
That trigger event is where heirs enter the picture. Because the loan is tied to the borrower, not the family, the death of the last surviving borrower sets a deadline. Heirs typically have a set period, often six months with possible extensions, to resolve the loan. They can sell the home, pay off the loan, or in some cases refinance it into a new mortgage in their own name. Understanding this timeline early prevents panic later.
One reassuring feature for families is that HECM loans are generally non-recourse. That means the lender can only look to the home for repayment, not to the heirs' other assets. If the home sells for less than the loan balance, FHA insurance typically covers the shortfall, and heirs are not personally liable. This protection is one of the most important facts a family can learn, because it removes the fear of inheriting debt.
For families weighing whether a reverse mortgage makes sense in the first place, it helps to understand how these loans are priced. Our guide on reverse mortgage rates explained breaks down how interest rates, origination fees, and mortgage insurance premiums affect the long-term balance that heirs will eventually see.
What Happens When the Last Borrower Dies or Moves Out
The most common scenario families face is the death of the last surviving borrower. At that point, the loan becomes due and payable. The lender will send a notice to the estate or the heirs, and the clock starts ticking. Heirs are not required to make monthly payments during this period, but they do need to act within the allowed timeframe.
If the last borrower moves into assisted living, a nursing home, or another residence for more than 12 months, the same rule applies. The home is no longer the primary residence, so the loan becomes due. This catches some families off guard, especially when a parent enters care temporarily and then stays longer than expected. Planning ahead for this possibility can save stress during an already difficult time.
Heirs have several paths forward once the loan is due. The right choice depends on the home's value, the loan balance, and the family's goals. Here are the main options:
- Sell the home and repay the loan: If the sale price exceeds the loan balance, the remaining equity goes to the heirs or the estate.
- Pay off the loan and keep the home: Heirs can use their own funds, a new mortgage, or a refinance to pay the reverse mortgage balance and retain ownership.
- Walk away and let the lender sell: If the loan balance exceeds the home's value, heirs can typically sign a deed-in-lieu of foreclosure and owe nothing further.
- Request an extension: Lenders may grant additional time, often up to 90 days, for heirs who need more time to sell or secure financing.
Each option has tax and financial implications, so consulting a qualified advisor or attorney is wise. The key point is that heirs usually have choices, and the non-recourse feature means they are not stuck with a bill they cannot pay.
Can Heirs Keep the Home? Refinancing and Payoff Strategies
Many families want to keep the home in the family, especially if it has been passed down for generations or holds sentimental value. Keeping the home is possible, but it requires paying off the reverse mortgage balance. That balance includes the original loan amount plus accrued interest, mortgage insurance premiums, and any financed closing costs.
Heirs can pay off the balance in several ways. They might use savings, take out a conventional mortgage in their own name, or use a home equity loan if they already own property. The new loan is based on the heirs' credit and income, not the deceased borrower's. If the home's appraised value is high enough and the heirs qualify, refinancing can be a clean solution.
Timing matters here. Lenders typically require the loan to be paid off within six months of the borrower's death, though extensions are common. Starting the refinance process early, ideally within the first few weeks, gives heirs the best chance of meeting deadlines without penalties or foreclosure proceedings. Communication with the loan servicer is essential, because they can clarify the exact payoff amount and the deadline for the specific loan.
It also helps to compare mortgage rates before committing to a refinance. Platforms like RateChecker allow heirs to see real-time rate comparisons and explore loan options, which can make the payoff process faster and more transparent. Having a clear picture of available rates helps families decide whether keeping the home is financially realistic or whether selling is the smarter path.
The Non-Recourse Protection: What It Means for Inherited Debt
One of the biggest misconceptions about reverse mortgages is that heirs inherit the debt. In reality, HECM loans are structured as non-recourse, meaning the lender's claim is limited to the home itself. If the home is worth less than the loan balance, the FHA insurance fund covers the difference, and neither the estate nor the heirs are personally responsible for the shortfall.
This protection does not apply to every situation, however. If heirs choose to keep the home and refinance, they take on a new loan that is fully recourse. If they fail to maintain the property, pay taxes, or keep insurance current, the lender could foreclose. And if the home is sold for more than the loan balance, the excess equity belongs to the heirs or the estate, not the lender.
Families should also be aware that reverse mortgage proceeds are generally treated as loan advances, not taxable income. However, heirs should consult a tax professional about their specific situation, because estate tax rules and inheritance laws vary by state. The non-recourse rule is a strong safety net, but it does not eliminate the need for careful planning.
Steps Families Should Take Before and After a Reverse Mortgage
The best time to plan for heirs is before the reverse mortgage is taken out. Families who understand the loan terms, the payoff timeline, and the options available are far better prepared when the loan becomes due. Here are practical steps that can make the process smoother:
- Review the loan documents together: Make sure at least one trusted family member understands the terms, including the interest rate, fees, and payoff conditions.
- Keep records accessible: Store the loan servicer's contact information, account numbers, and a copy of the loan agreement in a place heirs can find.
- Discuss the plan early: Talk about whether the family intends to sell, keep, or refinance the home, and who will be responsible for managing the process.
- Consult professionals: An elder law attorney or financial advisor can help heirs navigate deadlines, taxes, and estate considerations.
- Act quickly when the loan becomes due: Contact the servicer as soon as possible to confirm the payoff amount and request any extensions if needed.
After the borrower passes away, heirs should notify the loan servicer promptly and request a payoff statement in writing. This document shows the exact amount needed to satisfy the loan and the deadline for repayment. From there, heirs can decide whether to sell, refinance, or pay off the balance. Staying in close contact with the servicer and documenting every conversation helps avoid misunderstandings.
It is also important to maintain the property during the settlement period. The home must be kept in good condition, with taxes and insurance paid, until the loan is resolved. Neglecting these responsibilities can trigger foreclosure, which limits the family's options. Simple steps like lawn care, routine maintenance, and keeping utilities on can prevent problems.
Common Myths About Reverse Mortgages and Heirs
Misinformation about reverse mortgages can cause unnecessary fear. One common myth is that the bank takes the home as soon as the borrower dies. In reality, heirs have time to decide what to do, and the lender cannot simply seize the property without following legal procedures. Another myth is that heirs must sell the home immediately. While the loan becomes due, heirs can often refinance or pay it off if they want to keep the property.
A third myth is that heirs inherit the loan balance as personal debt. As noted, HECM loans are non-recourse, so heirs are not personally liable if the home is worth less than the loan. Finally, some families believe that a reverse mortgage eliminates all inheritance value. That is not true either. If the home appreciates or the loan balance is lower than the home's value, heirs can still receive the remaining equity.
Understanding these facts helps families make informed decisions and reduces anxiety during an emotional time. Reverse mortgages are complex, but they are designed with consumer protections that benefit heirs as well as borrowers.
For families who want to explore whether a reverse mortgage is the right choice for their situation, Express Mortgage Quotes offers educational resources and a quote comparison service that connects homeowners with verified lenders. While the platform is not a lender or broker, it provides tools and information that help families weigh their options and plan for the future.
Frequently Asked Questions About Reverse Mortgages and Heirs
Do heirs have to pay back a reverse mortgage?
Heirs are not personally responsible for the loan balance if the home is worth less than what is owed. The loan is non-recourse, so the lender can only seek repayment from the home's value. If the home sells for more than the balance, the remaining equity goes to the heirs. If it sells for less, FHA insurance covers the difference.
How long do heirs have to settle a reverse mortgage?
Typically, heirs have six months from the borrower's death to repay the loan or sell the home. Lenders may grant extensions of up to 90 days, and in some cases more time is allowed for good cause. It is important to contact the servicer early to confirm the exact timeline.
Can heirs keep the home after a reverse mortgage?
Yes, heirs can keep the home if they pay off the reverse mortgage balance. They can use their own funds, take out a new mortgage, or refinance. The new loan is based on the heirs' financial qualifications, not the original borrower's.
What happens if the home is worth less than the loan balance?
If the home is worth less than the loan balance, heirs can typically sign a deed-in-lieu of foreclosure and walk away without owing anything. The FHA insurance fund covers the lender's loss. Heirs are not required to pay the difference out of pocket.
Are reverse mortgage proceeds taxable to heirs?
Reverse mortgage proceeds are loan advances, not income, so they are generally not taxable. However, heirs should consult a tax professional about their specific situation, especially regarding estate taxes and the sale of the home.
Planning ahead and understanding the rules can turn a potentially confusing process into a manageable one. Families who educate themselves about reverse mortgages and heirs what family needs to know are better equipped to protect their loved one's legacy and make sound financial decisions together.