ADU Financing Options for Homeowners Adding a Rental Unit
Compare ADU financing options for homeowners adding a rental unit, from cash-out refinance to construction loans, and learn how lenders treat rental income.
By Aaron Nguyen
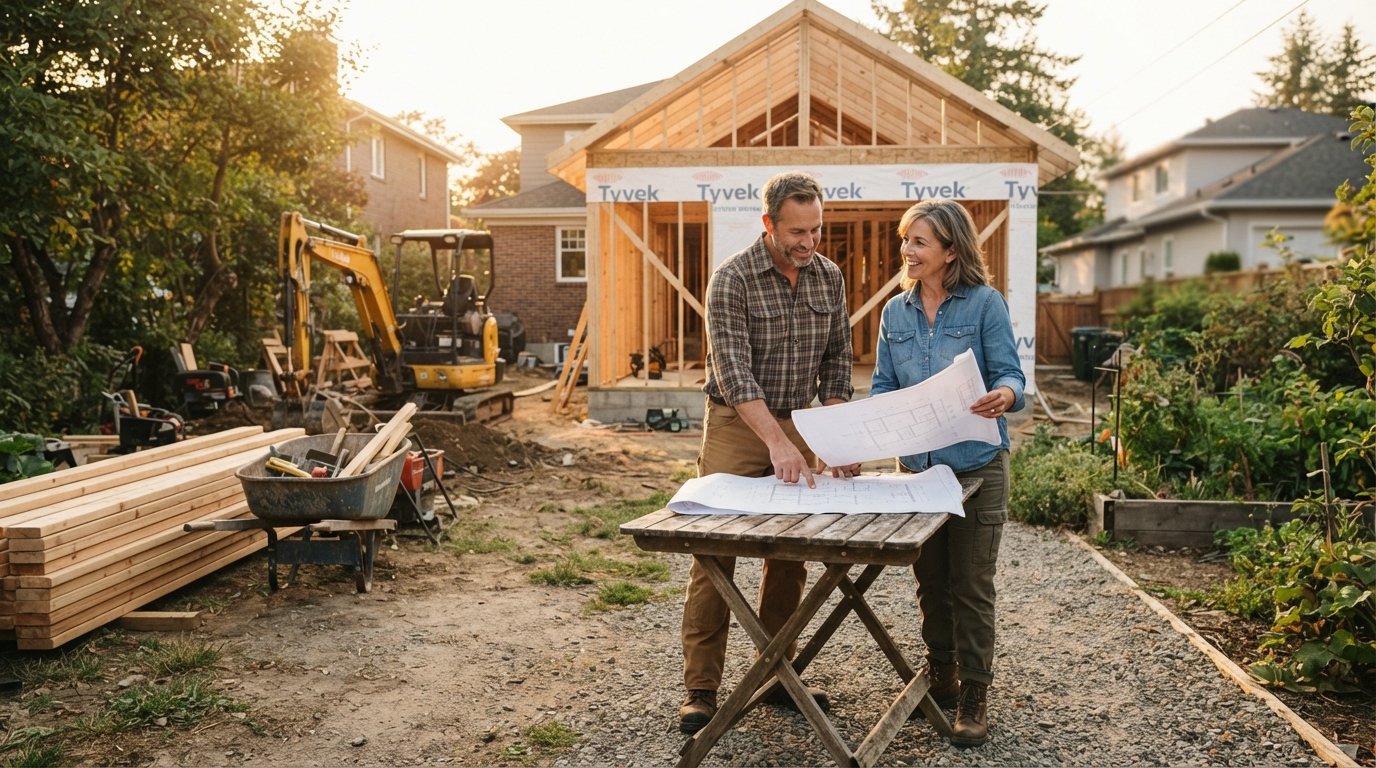
Building an accessory dwelling unit (ADU) is one of the most effective ways to add value to your property and generate rental income. Whether you are planning a garage conversion, a basement apartment, or a detached cottage, the cost can range from $50,000 to over $200,000 depending on your location and design. For most homeowners, paying cash is not realistic, so finding the right financing is the first critical step. The good news is that several lending paths exist, each with distinct advantages and requirements. This guide breaks down the ADU financing options for homeowners adding a rental unit, explains how lenders evaluate rental income, and highlights the local rules that can affect your loan approval.
Cash-Out Refinance: Tap Your Home Equity
A cash-out refinance replaces your existing mortgage with a new, larger loan and gives you the difference in cash. You can use those funds to build your ADU. This option often appeals to homeowners who can secure a lower interest rate than their current mortgage, effectively refinancing and funding the project at the same time. For example, if you owe $200,000 on a home worth $500,000, you might refinance for $300,000, take $100,000 in cash for the ADU, and still have a comfortable loan-to-value ratio.
Lenders typically allow cash-out refinances up to 80% of your home's appraised value, though some programs go higher. The interest rate is usually fixed, and you have a single monthly payment to manage. However, closing costs can be substantial (often 2% to 5% of the loan amount), and you are restarting your mortgage term. If you already have a low rate, a cash-out refinance may not be cost-effective. Still, it remains one of the most straightforward ADU financing options for homeowners adding a rental unit, especially for those with significant equity.
Home Equity Loans and HELOCs: Borrow Without Refinancing
If you want to keep your existing first mortgage intact, a home equity loan or a home equity line of credit (HELOC) can provide the funds for your ADU. A home equity loan gives you a lump sum with a fixed rate and fixed repayment schedule, which is ideal for covering predictable construction costs. A HELOC, on the other hand, works like a credit card: you draw funds as needed during the build, and you pay interest only on what you use. This flexibility can be valuable if your project has uncertain timing or costs.
Both options are secured by your home, so your property serves as collateral. Lenders generally allow combined loan-to-value ratios up to 85% or sometimes 90%, depending on the lender and your credit profile. Rates on home equity loans and HELOCs are often slightly higher than cash-out refinance rates, but you avoid the closing costs and disruption of refinancing your primary mortgage. For many homeowners, a HELOC is the preferred choice because it lets you manage cash flow during construction and only borrow what you need.
Construction Loans and Renovation Lending
If you are building an ADU from the ground up or doing a major renovation, a construction loan or renovation mortgage might be a better fit. A construction loan is a short-term, higher-interest loan that covers the cost of building. Funds are disbursed in draws as work progresses, and the loan is typically paid off or converted to a permanent mortgage once the ADU is complete. These loans require detailed plans, a licensed contractor, and a realistic budget.
Renovation lending programs, such as FHA 203(k) or Fannie Mae HomeStyle, allow you to finance the purchase or refinance of a home plus renovation costs in a single loan. If you already own your home, you can use a renovation mortgage to refinance and include the ADU construction costs. These programs are more paperwork-intensive and require lender-approved contractors, but they can be a smart way to fund a large project without depleting your savings. For a broader comparison of renovation financing, see our guide on home renovation financing options compared.
How Lenders View ADU Rental Income
One of the biggest questions homeowners have is whether lenders will count the future rental income from the ADU. The answer depends on the loan program and the lender's guidelines. In general, lenders are more willing to consider rental income if the ADU is already built and generating documented income. For a new ADU, some lenders will allow you to use projected rental income, but they typically require a signed lease or a professional appraisal that supports the income estimate. FHA and conventional guidelines have specific rules: for example, Fannie Mae allows rental income from an ADU to be counted if it is legally permitted and the borrower can document a history of receipt or a current lease.
To strengthen your application, gather evidence: a rental market analysis, a copy of the proposed lease, and proof that the ADU will be a legal, separate unit. Lenders also consider your debt-to-income ratio, so even if they count rental income, you need to show that you can repay the loan from your primary income if the unit sits vacant. Being conservative in your income projections can help you avoid over-leveraging and improve your chances of approval.
Local Rules and Permits That Affect Lending
ADU regulations vary widely by state, county, and city. Some jurisdictions have embraced ADUs with streamlined permitting, while others impose strict size, parking, and owner-occupancy requirements. Lenders will want to see that your ADU will be legally permitted and built to code. If you build without permits, you may not be able to count the rental income, and the lender could consider the property non-conforming, which affects refinancing and resale.
Before you apply for financing, check with your local planning department. Obtain a copy of the ADU ordinance, confirm zoning allowances, and understand the inspection process. Some lenders offer specific ADU loans that require proof of permits before disbursing funds. You may also need to provide a survey or site plan. Being proactive about permits not only smooths the lending process but also protects your investment and ensures the ADU is insurable and financeable in the future.
Choosing the Right Financing for Your ADU Project
There is no one-size-fits-all answer. The best choice depends on your equity, credit, existing mortgage rate, project timeline, and local regulations. To decide, consider these key factors:
- Amount needed: Small projects may fit a HELOC; larger builds may require a construction loan or cash-out refinance.
- Existing mortgage rate: If your current rate is low, avoid refinancing the entire balance; a home equity loan or HELOC preserves your first mortgage.
- Timeline: HELOCs offer flexibility for phased draws; construction loans are structured for defined build schedules.
- Rental income treatment: Some lenders are more generous about counting future ADU income; ask upfront.
It is wise to get quotes from multiple lenders. Comparing offers can reveal differences in rates, fees, and income-counting policies. You can start by using an online rate comparison tool to see illustrative rates for cash-out refinance, home equity loans, and construction financing. Remember that rates change daily, so confirm current terms directly with a licensed lender.
Finally, think about the long-term. An ADU can generate steady rental income, increase your property value, and provide flexible living space for family. But the financing should align with your overall financial plan. Avoid taking on more debt than you can comfortably repay, and consider how the ADU income will be taxed and insured. With careful planning and the right loan, your ADU project can become a rewarding investment.