Home Renovation Financing Options Compared for Homeowners
Compare cash-out refinance, home equity loans, HELOCs, and personal loans side by side to fund your renovation without straining your budget.
By Grace Parker
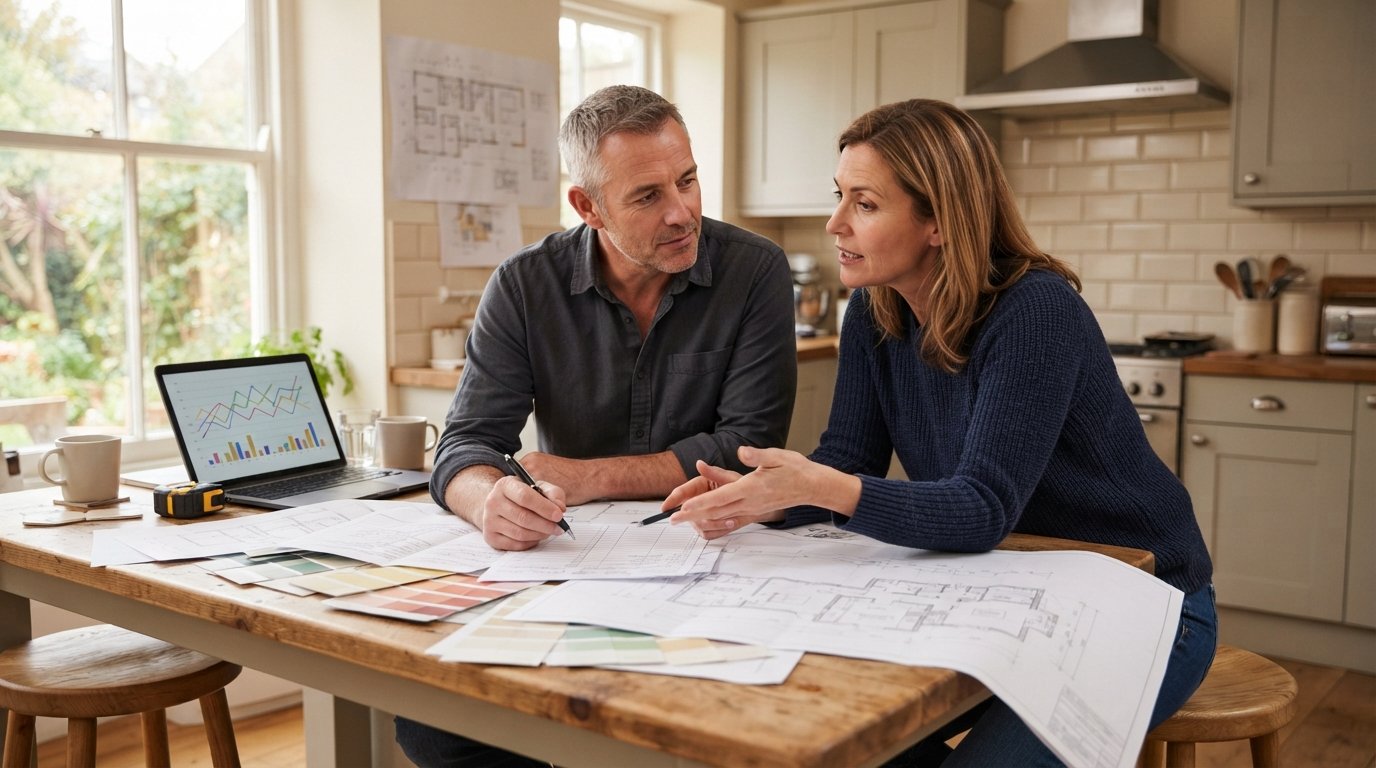
You have finally decided to remodel the kitchen, add that primary suite, or finish the basement. The plans are drawn, the contractor is booked, and then the estimate arrives. For most homeowners, the question is not whether the project is worth doing, but how to pay for it without wrecking their monthly budget. Home renovation financing options compared for homeowners have become a central part of project planning, because the funding method you choose can affect your mortgage, your credit, and your long-term financial flexibility.
The good news is that you are not limited to a single path. Cash-out refinancing, home equity loans, home equity lines of credit, and personal loans each solve a different problem. The right choice depends on how much you need, how quickly you need it, whether your costs will arrive in one lump sum or in stages, and how comfortable you are with changing your existing mortgage. This guide breaks down the main options side by side, explains how each one interacts with your current home loan, and helps you match the financing to the project in front of you.
Why the Financing Decision Matters as Much as the Renovation
A renovation is a financial event, not just a construction event. The way you fund it determines your interest rate, your repayment timeline, and the amount of risk you carry if your income changes or the project runs over budget. It also affects your mortgage itself. Some options replace your existing home loan, while others sit alongside it as a second lien. That distinction changes your monthly obligations, your closing costs, and even your ability to refinance again later.
Homeowners often default to whichever option their bank mentions first, or they reach for a credit card because it feels simple. That shortcut can be expensive. A credit card used for a $40,000 remodel at a typical double-digit rate can cost far more than a secured home equity product, even after accounting for closing costs. On the other hand, pulling cash out of your home for a cosmetic upgrade can put your property at risk if the market shifts. The goal is not to find the cheapest headline rate, but to find the option that fits the size, timeline, and structure of your project.
It also helps to think about how lenders view renovation spending. They care about your loan-to-value ratio, your credit profile, and your ability to repay. A well-planned renovation can increase your home's value, but lenders do not count future value until the work is complete and appraised. That is why the financing conversation usually starts with what you can qualify for today, not what your home will be worth tomorrow.
The Main Home Renovation Financing Options at a Glance
Before diving into the details, it helps to see the four most common options in one frame. Each product has a distinct structure, and that structure drives everything else: how you receive the money, how you repay it, and what it does to your existing mortgage.
- Cash-out refinance: Replaces your current mortgage with a larger one and gives you the difference in cash. Best for homeowners who want a new rate or term and can cover closing costs.
- Home equity loan: A fixed-rate second mortgage paid out in one lump sum. Best for projects with a known, stable budget.
- HELOC: A revolving line of credit with a variable rate, drawn as needed during the draw period. Best for phased projects or uncertain costs.
- Personal loan: An unsecured installment loan with no home collateral. Best for smaller projects or homeowners who cannot or will not use home equity.
These four options are not interchangeable. A cash-out refinance changes your primary mortgage, while a home equity loan or HELOC leaves it untouched. A personal loan protects your home from foreclosure risk but usually carries a higher rate. Understanding these trade-offs is the foundation for comparing home renovation financing options for homeowners in a way that actually reflects your situation.
Cash-Out Refinance: A New Mortgage With Cash Back
A cash-out refinance replaces your existing mortgage with a new, larger loan. You receive the difference between the new loan amount and what you owe on the old one, minus closing costs. For example, if you owe $200,000 on a home worth $400,000 and you refinance into a $260,000 loan, you would receive roughly $60,000 before fees, subject to lender limits and your loan-to-value ratio.
The appeal is straightforward: you can potentially lower your interest rate, change your loan term, and access renovation funds in one transaction. If rates have fallen since you bought your home, a cash-out refinance can be a efficient way to fund a major remodel. It also consolidates your renovation debt into a single mortgage payment, which can simplify your budget.
The drawbacks deserve equal attention. You are restarting your mortgage, which can extend your repayment timeline and increase the total interest you pay over the life of the loan. Closing costs on a refinance typically run 2% to 5% of the loan amount, so a $300,000 refinance could cost $6,000 to $15,000 upfront. You also need enough equity to satisfy the lender's loan-to-value requirement, which is often 80% but can vary. Finally, because the loan is secured by your home, a cash-out refinance puts your property on the line if you fall behind.
This option tends to fit best when the renovation is large, when you plan to stay in the home long enough to recoup closing costs, and when the new mortgage rate is competitive with your current one. If you are mainly chasing cash and your existing rate is already low, a second lien may be the smarter path. For a broader look at how refinancing fits into your overall mortgage strategy, the guide on comparing mortgage options for home buyers walks through the trade-offs between loan structures.
Home Equity Loan: Fixed Rates and a Single Lump Sum
A home equity loan is a second mortgage that pays out a fixed amount at closing. You repay it in equal monthly installments over a set term, usually five to thirty years. Because the rate is fixed, your payment does not change, which makes budgeting straightforward. You keep your existing first mortgage exactly as it is, including its rate and remaining term.
This structure works well for renovations with a defined scope and a stable budget. If your contractor has given you a fixed bid and the work will be completed in one continuous phase, a home equity loan gives you the money upfront and a predictable repayment plan. It also avoids the closing costs and paperwork of refinancing your primary mortgage, which can be a meaningful savings if your first loan already has a low rate.
The trade-offs are equally clear. You pay interest on the full loan amount from day one, even if you do not spend it all immediately. Closing costs on a home equity loan are typically lower than on a refinance but still exist, often 2% to 5% of the loan amount. The loan is secured by your home, so default risk remains. And because it is a second lien, your total monthly housing debt increases, which lenders will factor in if you apply for other credit later.
Home equity loans are also subject to lender limits on combined loan-to-value, which is the total of all liens divided by the home's appraised value. Many lenders cap this at 80% to 85%, though some allow higher. If you have substantial equity, a home equity loan can be a clean, fixed-rate solution for a mid-sized to large renovation.
HELOC: A Revolving Line for Phased Projects
A home equity line of credit, or HELOC, works more like a credit card secured by your home. You are approved for a maximum limit, and you can draw funds as needed during a draw period that typically lasts five to ten years. During that time, you usually pay interest only on the amount you have drawn. After the draw period ends, you enter repayment, where the principal and interest are amortized over a set term.
The flexibility is the main advantage. Renovations rarely go exactly as planned. A phased kitchen remodel, an addition with multiple stages, or a project where you are managing subcontractors yourself can benefit from a line you can tap incrementally. You only pay interest on what you actually use, which can save money compared with a lump-sum loan. HELOCs are also useful for unexpected overages, because you can draw additional funds without applying for a new loan.
The risks are important to understand. Most HELOCs carry variable rates, so your payment can rise if benchmark rates increase. Interest-only payments during the draw period can mask the true cost of the debt, and homeowners sometimes underestimate how much their payments will jump when repayment begins. Some HELOCs also include fees, annual charges, or early-closure penalties. As with any home-secured product, default can lead to foreclosure.
A HELOC tends to fit projects with uncertain timing or cost, or homeowners who want a financial cushion alongside the renovation budget. It is less ideal for a project where you know the exact amount and want the certainty of a fixed rate. If you are comparing this option with a fixed home equity loan, ask yourself whether you value predictability or flexibility more.
Personal Loans: No Home Collateral, Higher Rates
A personal loan is an unsecured installment loan. You borrow a fixed amount, repay it over a set term, and the loan is not tied to your home. That last point is significant: if you fall behind on a personal loan, your home is not at risk of foreclosure. For homeowners who are uncomfortable using their property as collateral, or who do not have enough equity for a secured product, a personal loan can be a practical option.
Personal loans are generally faster to obtain than home equity products. Approval can happen in days, and funds may arrive quickly, which helps if your contractor needs a deposit or you are facing a sudden repair. They also avoid appraisal costs and the closing costs associated with home-secured loans.
The trade-off is cost. Because the loan is unsecured, lenders charge higher interest rates to compensate for the risk. Rates vary widely based on credit score, income, and lender, and illustrative ranges can run from the high single digits to well into double digits. Loan amounts are also often capped lower than home equity products, which makes personal loans better suited to smaller projects such as a bathroom refresh, flooring, or a minor repair rather than a full addition.
Personal loans can also affect your debt-to-income ratio, which matters if you plan to apply for a mortgage or refinance in the near future. A large personal loan payment can reduce your borrowing capacity. If your project is small and your timeline is tight, a personal loan may be worth the higher rate. If your project is large, the cost gap usually favors a home-secured option.
How Each Option Affects Your Existing Mortgage and Monthly Obligations
The interaction with your current mortgage is where these options diverge most sharply. A cash-out refinance replaces your first mortgage entirely. Your old loan is paid off, and you have a new loan with new terms. That means your monthly payment changes, your remaining term changes, and your total interest cost over time changes. If the new rate is lower, you may save money; if it is higher, you may pay more even though you gained cash.
A home equity loan or HELOC leaves your first mortgage untouched. You keep your existing rate and term, and you add a second payment. That can be advantageous if your first mortgage has a low rate you do not want to give up. It also means your total monthly housing obligation increases by the amount of the second lien payment. Lenders will evaluate that combined payment when you apply for future credit.
A personal loan does not touch your mortgage at all, but it still adds a monthly obligation. Because it is unsecured, it may carry a higher payment relative to the amount borrowed. The key question is whether the added payment fits comfortably within your budget alongside your mortgage, taxes, insurance, and other obligations.
It also helps to consider how each option affects your credit profile. A cash-out refinance pays off your old mortgage and opens a new account, which can temporarily affect your credit score. A home equity loan or HELOC adds a new account and increases your total debt. A personal loan adds an installment account. None of these are inherently bad, but they matter if you plan to apply for other financing soon.
Matching the Option to Project Size, Timeline, and Draw Needs
The most useful way to compare home renovation financing options for homeowners is to start with the project itself. Project size, timeline, and how you need to draw funds will narrow the field quickly.
For small projects under roughly $15,000, such as a bathroom update, new flooring, or a minor repair, a personal loan or a modest HELOC draw may be sufficient. The closing costs on a refinance or home equity loan can be hard to justify at that scale. For mid-sized projects between $15,000 and $75,000, a home equity loan offers fixed-rate predictability, while a HELOC offers flexibility if the scope may change. For large projects above $75,000, such as an addition or a full gut renovation, a cash-out refinance or a large home equity loan often makes more sense, provided you have the equity and can absorb the closing costs.
Timeline matters too. If you need funds in a matter of days, a personal loan or a HELOC with a fast approval process may be the only realistic path. If you have weeks or months, a cash-out refinance or home equity loan becomes more viable. And if your project will be paid out in stages, a HELOC's draw structure aligns better than a lump-sum product.
Draw needs are the third variable. A single lump sum suits a fixed bid with one contractor. A revolving line suits a project where you are hiring separate trades, buying materials over time, or keeping a contingency reserve. Matching the draw structure to the actual cash flow of the renovation prevents you from paying interest on money you have not yet spent.
Illustrative Rate Ranges and the Need to Confirm Current Terms
Any rate you see in an article, including this one, is illustrative only. Mortgage and home equity rates change daily based on market conditions, Federal Reserve policy, lender pricing, and your personal credit profile. The same homeowner might be quoted different rates by different lenders on the same day. That is why the numbers below should be treated as context, not as quotes.
As a general reference point, cash-out refinance rates tend to track close to standard mortgage rates, though lenders often add a pricing adjustment for cash-out loans. Home equity loan rates are typically somewhat higher than first mortgage rates because the lender holds a second lien. HELOC rates are usually variable and can start lower than fixed home equity loans during promotional periods, then adjust. Personal loan rates are generally the highest of the group because the loan is unsecured, with the widest spread based on creditworthiness.
Before you commit, confirm current rates and terms directly with licensed lenders. Ask for the annual percentage rate, not just the interest rate, so you can see the total cost including fees. Ask about closing costs, prepayment penalties, variable-rate caps, and draw-period terms. And ask how the lender reports the account to credit bureaus, since that affects your credit profile. For a plain-language explanation of how home purchase loans, refinances, home equity products, and reverse mortgages work, MortgageDirectory publishes educational guides and a payment calculator that can help you understand rates, costs, and loan terms before you talk with a lender.
Practical Steps to Compare Your Options
Comparing financing options is easier when you follow a consistent process. Start by defining the project budget, including a contingency of 10% to 20% for overages. Then gather your financial documents, including recent pay stubs, tax returns, bank statements, and your current mortgage statement. Check your credit score and your home's estimated value so you know your approximate loan-to-value ratio.
Next, request quotes from multiple lenders for each option you are considering. Compare the APR, closing costs, monthly payment, and total interest over the life of the loan. Do not compare a 10-year home equity loan with a 30-year cash-out refinance on monthly payment alone, because the terms are different. Use a mortgage calculator to model different scenarios and see how the payments fit your budget.
Finally, consider your long-term plans. If you plan to sell within a few years, the closing costs of a refinance may not be worth it. If you plan to stay for a decade or more, a lower-rate refinance can pay off. If your income is variable or you expect changes, a fixed-rate product may offer more stability than a variable HELOC. The right answer is the one that fits your project and your financial life, not the one with the lowest advertised rate.
Frequently Asked Questions
Can I use a renovation loan backed by the government?
Yes, some government-backed programs allow you to finance a purchase or refinance plus renovation costs in a single loan. These programs have specific eligibility rules, contractor requirements, and inspection processes. They can be useful for buyers purchasing a fixer-upper, but they are not the same as the home equity products discussed here. If you are considering one, compare its terms carefully with a cash-out refinance or home equity loan.
Is it better to finance a renovation or pay cash?
Paying cash avoids interest and closing costs, which is ideal if you have the funds and want to preserve your borrowing capacity. Financing makes sense when you want to keep your cash reserves for emergencies or when the return on the renovation exceeds the cost of borrowing. There is no universal answer, but a good rule is to keep at least three to six months of expenses in reserve before committing cash to a renovation.
Will a home equity loan or HELOC affect my ability to refinance later?
It can. A second lien increases your total debt and affects your combined loan-to-value ratio, which lenders consider when you apply for a refinance. Some lenders require you to pay off or subordinate the second lien during a refinance. If you plan to refinance soon, discuss the timing with your lender before opening a second lien.
How much equity do I need to qualify?
Requirements vary by lender and product. Many lenders cap combined loan-to-value at 80% to 85% for home equity products, while cash-out refinances often require at least 20% equity remaining after the cash out. Personal loans do not require equity but do require sufficient income and credit. Check with individual lenders for their specific guidelines.
Home renovation financing is not a one-size-fits-all decision. A cash-out refinance can be powerful for large projects and rate-sensitive homeowners, a home equity loan offers fixed-rate certainty, a HELOC provides flexible draws for phased work, and a personal loan protects your home from collateral risk at the cost of a higher rate. Compare the options against your project size, timeline, and budget, confirm current terms with licensed lenders, and choose the path that keeps your renovation and your finances on solid ground.