Energy Efficient Mortgage and Specialized Government Loan Programs
An energy efficient mortgage and specialized government loan programs can cut costs and finance upgrades. Learn how to qualify and avoid common pitfalls.
By Hannah Carter
Most home buyers know about FHA, VA, and USDA loans. Far fewer understand that the mortgage industry offers a parallel set of options designed to reward energy efficiency and to reach borrowers whom standard loans leave behind. An energy efficient mortgage and specialized government loan programs can reduce your monthly costs, finance improvements that pay you back, and open doors in situations where a conventional lender might say no. The catch is that these programs come with eligibility quirks, property rules, and regional variations that trip up even experienced buyers. This guide walks through how these loans work, where they fit, and the questions to ask before you assume a standard mortgage is your only path.
How Energy Efficient Mortgages Fold Improvement Costs Into the Loan
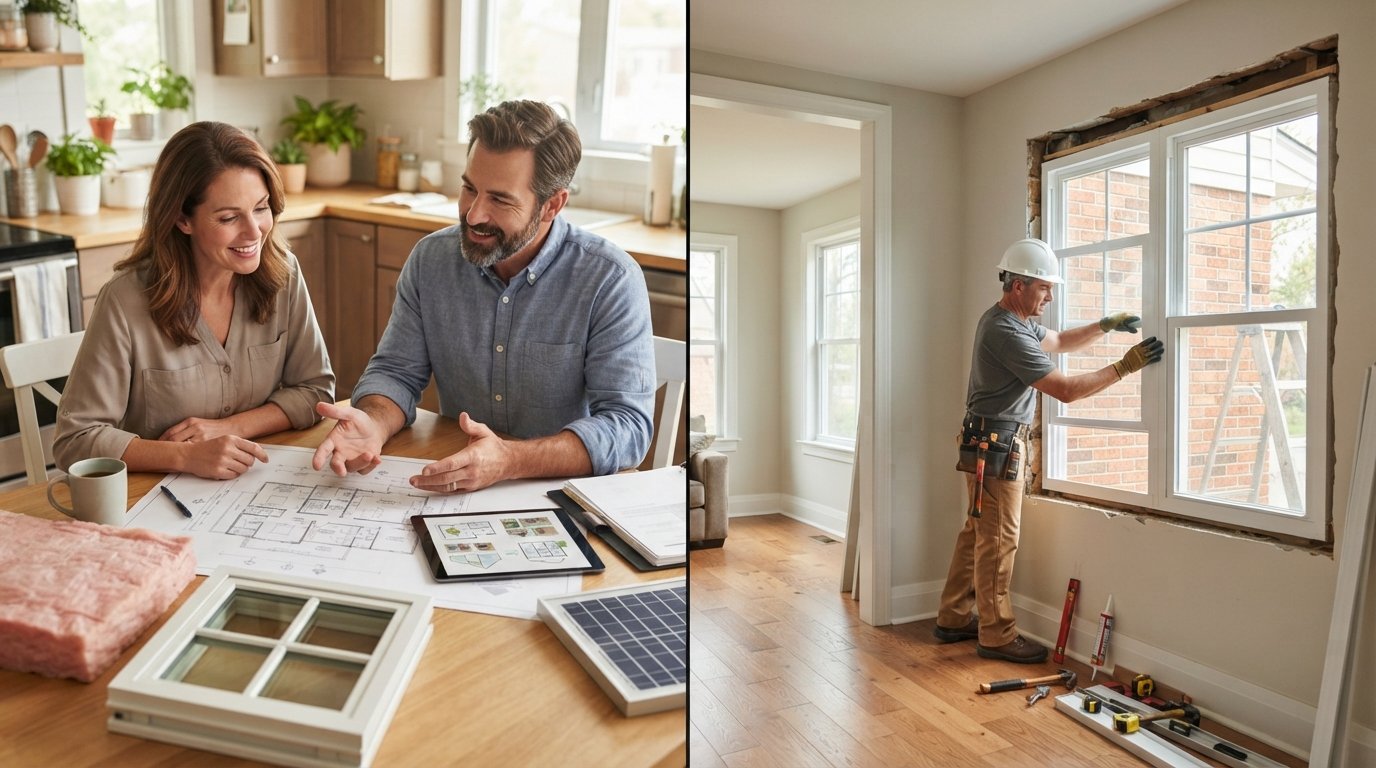
An energy efficient mortgage, often called an EEM, is not a separate loan product in the way a VA or FHA loan is. It is a feature that can be attached to an existing government-backed or conventional mortgage, allowing the borrower to finance energy-saving improvements as part of the same loan. Instead of taking out a second mortgage or a high-interest personal loan to pay for insulation, windows, or a new HVAC system, you roll those costs into the first mortgage. The lender underwrites the improvement costs alongside the home purchase or refinance, and in many cases the borrower can qualify for a larger loan amount than the standard limits would allow because the improvements are expected to lower utility bills.
The logic behind the program is simple: a more efficient home costs less to operate, so the borrower has more disposable income each month. Lenders recognize this and may stretch debt-to-income ratios or loan limits to accommodate the added cost. The improvements must be cost-effective, meaning the projected energy savings over the life of the loan should exceed the cost of the improvements. An approved energy report, often called a Home Energy Rating System report or HERS report, is typically required to document the expected savings. The report is prepared by a qualified energy rater who inspects the property and models its performance.
Here is how the process generally unfolds for a buyer using an EEM:
- Get pre-approved for the base loan. The lender reviews your income, assets, and credit to establish how much you can borrow for the home itself.
- Order an energy assessment. A certified rater evaluates the property and produces a report listing recommended improvements and their projected savings.
- Choose cost-effective improvements. You and the lender select items from the report that meet the program's cost-effectiveness test, such as attic insulation, duct sealing, or high-efficiency water heating.
- Finance the improvements in the loan. The lender adds the improvement costs to the mortgage amount, subject to program caps, and the work is completed after closing or held in escrow.
- Complete a post-installation inspection. A final inspection confirms the work was done, which protects both the borrower and the lender.
The result is a single monthly payment that covers both the home and the upgrades, often with little or no increase in out-of-pocket cost because the energy savings offset the higher loan amount. For homeowners who are refinancing rather than buying, the same structure applies: the EEM feature can be added to a rate-and-term or cash-out refinance, allowing you to tap equity for efficiency upgrades without a separate application. Buyers exploring affordable mortgage options for first-time buyers in 2026 should ask specifically whether an EEM feature is available on the loan they are considering, because it is often overlooked in standard pre-approval conversations.
Specialized Government Loan Programs and the Eligibility Quirks That Trip People Up
Beyond the well-known FHA, VA, and USDA programs, several specialized government loan programs target specific borrowers, property types, or regions. These programs often carry names that sound similar to one another, and their eligibility rules can be counterintuitive. For example, some programs are administered by state housing finance agencies rather than by a federal agency, so the rules change depending on where you live. Others are tied to specific professions or income thresholds that are not obvious from the program name. Understanding these quirks before you apply can save weeks of processing time and prevent a denial that could have been avoided.
One common source of confusion is the distinction between a program's eligibility rules and its property standards. Many specialized programs are designed for rural or underserved areas, and they may require the property to meet specific condition standards or be located within a defined geographic boundary. A borrower who qualifies on income may still be denied because the property sits just outside the eligible area. Similarly, some programs require the borrower to complete a homebuyer education course, and the course must be completed before closing, not after. These details are rarely highlighted in marketing materials, but they appear in the program guidelines and can derail an application if overlooked.
Here are some of the specialized programs and features worth knowing about, along with the quirks that commonly cause problems:
- Section 203(k) rehabilitation loans: These FHA-backed loans finance both the purchase and the rehabilitation of a home in a single mortgage. The quirk is that the borrower must use an approved consultant for certain projects, and the repair costs are held in escrow and released in draws, which can slow down the renovation timeline.
- Good Neighbor Next Door: This program offers significant discounts to teachers, law enforcement officers, firefighters, and emergency medical technicians who buy homes in revitalization areas. The quirk is that the borrower must commit to living in the home for a set period, and the program is only available in designated areas that change over time.
- State and local housing finance agency loans: Many states offer below-market-rate loans and down payment assistance to first-time buyers and moderate-income households. The quirk is that these programs often have recapture provisions, meaning a portion of the benefit must be repaid if you sell or refinance within a certain number of years.
- USDA Section 502 direct loans: Unlike the guaranteed USDA loan most buyers know, the direct loan program is for very-low-income households and is administered directly by the USDA. The quirk is that the application process is separate from the guaranteed loan process, and funding is limited, so timing matters.
The common thread is that these programs reward preparation. Borrowers who read the fine print and confirm their eligibility with the administering agency before applying tend to have smoother experiences. It also helps to work with a lender who regularly handles the specific program, because the documentation requirements vary widely. For borrowers comparing options, MortgageDirectory publishes plain-language guides on how home purchase loans, refinances, and related products work, which can help you frame the right questions before you talk with a lender.
Which Property Types and Regions These Programs Serve
Specialized government loan programs are not evenly distributed across the country or across property types. Some are designed for single-family primary residences, while others extend to duplexes, manufactured homes, or properties in specific rural areas. The property type matters because lenders must confirm that the home meets the program's standards, and a mismatch can lead to a denial even when the borrower qualifies on income and credit. For example, a program intended for rural areas may exclude properties that are within city limits, even if the surrounding area feels rural. A program designed for first-time buyers may exclude properties that have been previously owned by the borrower, regardless of how long ago that was.
Regions also play a role in program availability. Many state housing finance agencies offer their own loan programs with income limits and purchase price limits that vary by county. These limits are updated annually and can change the calculus for a buyer who is near the threshold. In high-cost areas, the limits may be higher, but the competition for limited funds can also be greater. In rural areas, USDA programs may be the primary option, but the property must be in an eligible area, and the borrower must meet income limits that are set relative to the area median income. Buyers who assume a standard loan is their only option often miss out on programs that would have saved them thousands of dollars over the life of the loan.
The practical takeaway is to verify three things before you fall in love with a property: whether the property type is eligible, whether the location falls within the program's boundaries, and whether your income falls within the program's limits. These checks take only a few minutes with the right resources, but they can prevent a costly misstep. If you are unsure, ask a lender who specializes in the program to run the address through the eligibility tool before you make an offer.
Questions to Ask Before Assuming a Standard Loan Is Your Only Path
Many buyers default to a conventional or FHA loan because those are the products most lenders advertise. That default can be expensive. Before you commit, ask a short set of questions that can reveal whether you qualify for a better option. The answers may point you toward an energy efficient mortgage, a state housing program, or a specialized federal program that reduces your down payment, lowers your interest rate, or finances improvements you would otherwise pay for out of pocket.
Start with your lender. Ask whether the loan you are considering allows an energy efficient mortgage feature, and if so, what the caps and documentation requirements are. Ask whether the lender participates in any state or local housing programs, and whether your income and the property's location make you eligible. Ask about the total cost of the loan, including any recapture provisions or repayment obligations that come with down payment assistance. Finally, ask what happens if you sell or refinance within the first few years, because some programs impose penalties or require repayment of benefits.
Here is a short list of questions to bring to your next lender conversation:
- Does this loan allow an energy efficient mortgage feature, and what improvements qualify?
- Are there state or local programs I might qualify for based on my income or profession?
- What are the income and purchase price limits for those programs in my county?
- Does the program include down payment assistance, and is any of it repayable?
- What documentation will I need to provide, and how long does the process typically take?
These questions do not require you to become a mortgage expert. They simply prompt the lender to look beyond the default product and consider whether a specialized option fits. A good lender will appreciate the questions, because they lead to a better-matched loan and a smoother closing. If a lender cannot answer them, that is a signal to seek a second opinion from a lender who works with government-backed and energy efficient products.
An energy efficient mortgage and specialized government loan programs are not niche curiosities. They are practical tools that can lower your monthly costs, finance improvements that pay for themselves, and reach borrowers whom standard loans overlook. The key is to ask the right questions early, verify eligibility before you make an offer, and work with a lender who knows the programs well. Whether you are buying your first home, refinancing to upgrade efficiency, or exploring options in a rural or underserved area, these programs deserve a place on your shortlist. Start by comparing quotes from lenders who understand these options, and you may find that the best loan for your situation is one you had not considered.