Reverse Mortgage Counseling Requirement: What to Expect in 2026
The reverse mortgage counseling requirement is mandatory for HECM loans. Here is what happens in the session, what it costs, and how to prepare before you apply.
By Aaron Nguyen
The reverse mortgage counseling requirement is not a bureaucratic hurdle to clear before you get to the real conversation. It is the real conversation, a mandatory, independent education session that exists to protect you, the homeowner aged 62 or older, from making a decision that could jeopardize your home and your financial future. If you are exploring a Home Equity Conversion Mortgage (HECM), the federally insured reverse mortgage backed by the FHA, you cannot proceed to application without completing this step first. Understanding what happens during counseling, what it costs, how long it takes, and what questions you should ask will turn a confusing obligation into one of the most valuable hours you spend in the entire loan process.
Why Counseling Is Mandatory for Reverse Mortgages
Congress created the counseling requirement in the late 1980s when reverse mortgages were emerging as a new financial product and reports of misleading sales practices began surfacing. The goal was straightforward: ensure that older homeowners receive unbiased, third-party education before converting home equity into loan proceeds. That requirement has survived every subsequent round of HECM reform, including the major changes in 2014 and the ongoing updates administered by the Department of Housing and Urban Development (HUD).
The logic behind mandatory counseling is that a reverse mortgage is fundamentally different from a traditional forward mortgage. You are not making monthly payments to pay down a loan. Instead, the loan balance grows over time, your equity decreases, and the loan becomes due when you permanently leave the home, sell it, or pass away. Those mechanics are easy to misunderstand, and misunderstandings in this product category can be financially devastating. Counseling ensures a neutral party walks you through the tradeoffs before you sign anything.
It is also worth noting that counseling is required for proprietary reverse mortgages (jumbo reverse mortgages offered by private lenders) in many states, though the specific rules vary. For HECM loans, the requirement is universal. If a lender or broker tells you counseling can be waived, that is a red flag. It cannot be waived for a federally insured reverse mortgage.
Who Provides the Counseling and How to Find a Counselor
HUD does not deliver counseling directly. Instead, it approves independent counseling agencies, typically nonprofit organizations and community development groups, to deliver reverse mortgage counseling. These agencies must follow HUD guidelines and employ counselors who hold specific certifications. You can find the official list through HUD's counseling directory, and your lender is required to provide you with a list of approved agencies in your area.
Because the counseling must be independent, the counselor cannot be employed by the lender, the broker, or any party with a financial stake in your loan. That separation is intentional. The counselor's job is to educate you, not to sell you a loan, and a good counselor will encourage you to consider alternatives such as selling your home, downsizing, using a home equity loan or line of credit, or exploring local property tax deferral programs.
When you contact an approved agency, expect to provide basic information about your situation, including your age, the property address, and your reason for considering a reverse mortgage. Some agencies conduct sessions in person, while many now offer telephone or video counseling. HUD allows all three formats, though some lenders or states may have preferences. If you are working with a platform like Express Mortgage Quotes to research reverse mortgage options, you can still choose any HUD-approved counselor you prefer, and your lender cannot steer you to a specific agency.
What Happens During the Counseling Session
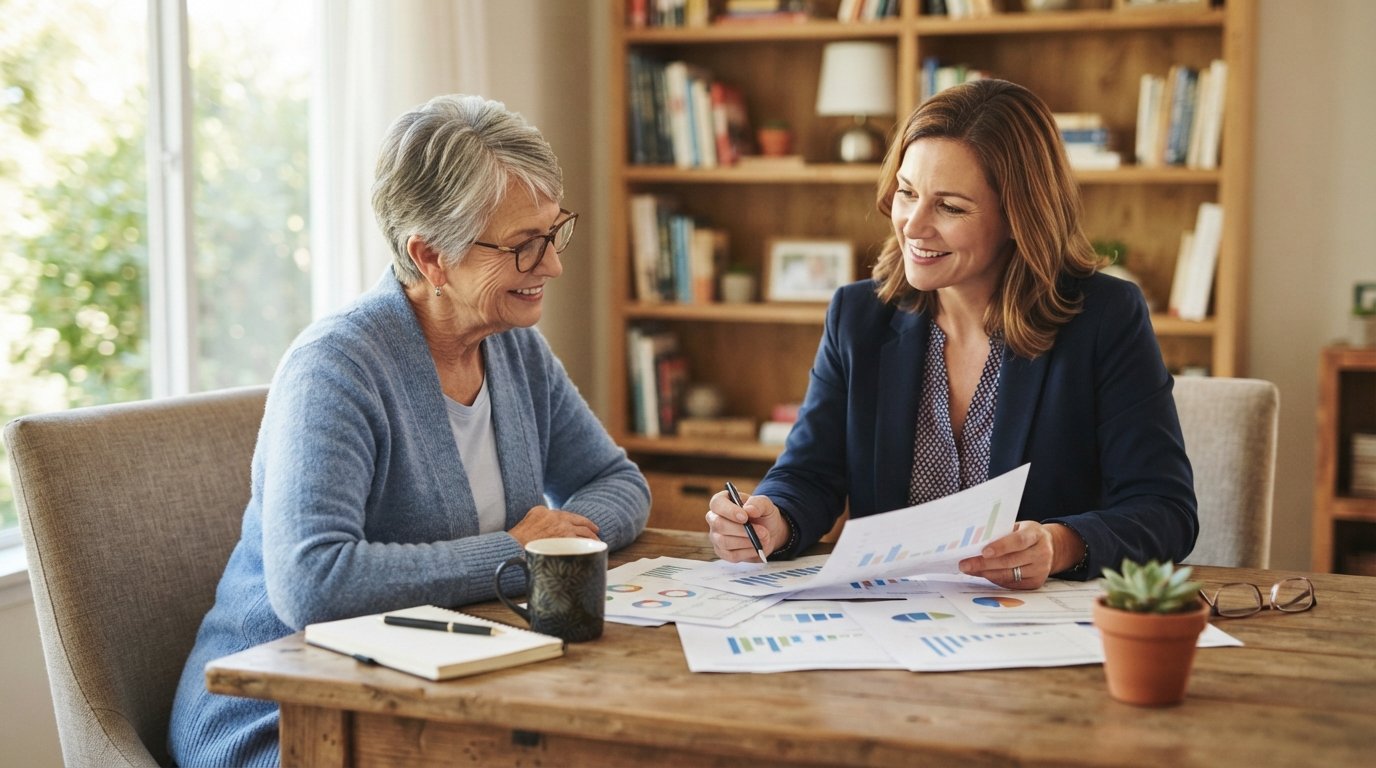
A typical reverse mortgage counseling session lasts between 60 and 90 minutes, though it can run longer if you have many questions or a complicated financial situation. The counselor will walk you through the following topics, and you should expect to discuss each one in detail rather than skim past it.
- How a reverse mortgage works: The counselor explains that you retain the title, you must continue paying property taxes, homeowners insurance, and maintenance costs, and the loan balance grows over time because interest and fees are added to the principal.
- Your payout options: You can receive proceeds as a lump sum, a monthly installment (for a fixed term or for life), a line of credit, or a combination. Each option has different implications for your long-term finances and your ability to access funds later.
- Costs and fees: The counselor reviews the upfront costs, including the initial mortgage insurance premium, origination fee, closing costs, and the ongoing mortgage insurance premium and servicing fee. These costs are higher than those of a traditional mortgage, and you need to understand why.
- Alternatives to a reverse mortgage: The counselor will discuss other ways to access equity or reduce expenses, including selling and downsizing, a traditional home equity loan or HELOC, refinancing, or assistance programs for seniors.
- Your responsibilities: You must live in the home as your primary residence, keep current on property taxes and insurance, and maintain the property in reasonable condition. Failing to meet these obligations can trigger default and foreclosure.
- Impact on your estate and heirs: The counselor explains that your heirs can repay the loan and keep the home, sell the home to repay the loan, or allow the lender to sell the home. Non-recourse protections mean your heirs will never owe more than the home is worth, but the estate will not receive the remaining equity if the loan balance equals or exceeds the home value.
Beyond these core topics, the counselor is required to discuss your financial circumstances and your reasons for seeking a reverse mortgage. This is not a test, but an honest conversation about whether the product fits your needs. If you are considering a reverse mortgage to cover a short-term expense, for example, the counselor may point out that the high upfront costs make it an expensive way to borrow a small amount. If you are looking for long-term income stability, the conversation may focus on payout options that preserve a line of credit for future needs.
What You Need to Prepare Before Counseling
You will get much more out of the session if you prepare. HUD requires counselors to collect certain information before or during the session, and having it ready reduces the likelihood that you will need a follow-up appointment. Many agencies will send you a packet or a checklist in advance, and completing it thoroughly is in your interest.
At a minimum, gather the following documents and information:
- Photo identification and proof of age for all borrowers on the loan
- Your Social Security number and contact information
- The property address and an estimate of its current market value
- Your estimated mortgage balance and any other liens on the home
- Your monthly income sources, including Social Security, pensions, and investment income
- Your monthly expenses, including property taxes, insurance, and regular bills
- Any questions you have about the loan or your financial situation
You should also decide in advance whether you want a trusted family member, friend, or advisor to join the session. HUD allows (and often encourages) a third party to participate, and many counselors will ask if you want someone else on the line. Having a son, daughter, or financial advisor listen in can help you remember details later and can reduce the risk of misunderstanding. If you want a family member to participate, let the counseling agency know when you schedule the appointment so they can accommodate the request.
Cost and Timing of Reverse Mortgage Counseling
Counseling is not free, but it is not expensive either. The cost typically ranges from about $125 to $200, depending on the agency and the format of the session. Some agencies charge on a sliding scale based on income, and some waive the fee for low-income homeowners. In certain cases, the lender may cover the cost of counseling, but you should confirm that arrangement in writing before you assume it applies. The fee is separate from the loan closing costs, and you typically pay it directly to the counseling agency.
Timing matters because you cannot apply for a reverse mortgage until you have completed counseling and received your certificate. Most agencies can schedule a session within one to two weeks, though demand can push that timeline out during busy periods. The certificate itself does not expire in most cases, but some lenders require that counseling be completed within a certain window before the loan application, often 180 days. If your loan process takes longer than expected, you may need to repeat the counseling session or obtain an updated certificate. Always ask your lender about its specific timing requirements.
After the session, the counselor will issue a certificate of completion, sometimes called a counseling certificate. This document is your proof that you satisfied the HUD requirement, and you must provide it to your lender before the loan can proceed. If you lose it, you can request a replacement from the counseling agency, though some agencies charge a small fee for reissuing it.
Common Mistakes and What to Watch For
The most common mistake homeowners make is treating counseling as a formality to rush through. Some borrowers schedule the session on a busy afternoon, answer questions with one-word responses, and hang up without asking anything. That approach defeats the purpose and can leave you unprepared for the financial commitment you are about to make. Instead, treat the session as a consultation with a free expert who has no incentive to sell you anything.
Another common mistake is failing to disclose your full financial picture. The counselor is not there to judge you, and withholding information about your income, expenses, or debts only limits the quality of the guidance you receive. If you have a history of missed property tax payments, for example, the counselor needs to know so they can discuss how a reverse mortgage might interact with that issue and whether you are at risk of default.
You should also be cautious if a lender or broker attempts to influence which counselor you use or pressures you to complete counseling with a specific agency. That is a violation of HUD rules, and it undermines the independence that makes counseling valuable. You have the right to choose any HUD-approved agency, and you can report any pressure to HUD's Office of Inspector General.
Finally, do not ignore the follow-up. Some counselors offer a second session or a check-in call after you have had time to think. If you are offered that opportunity, take it. A second conversation can clarify details you missed the first time and give you a chance to ask questions that occurred to you later. For a broader look at how rates and loan structures affect your costs, you can review our guide on reverse mortgage rates in 2026 to see how the numbers fit into the counseling conversation.
How Counseling Fits Into the Broader Reverse Mortgage Process
Counseling is the first formal step in the reverse mortgage journey, but it is not the only one. After you receive your certificate, you can complete a loan application with a lender. The lender will then order an appraisal, verify your financial information, and underwrite the loan. You will also need to complete any required financial assessment, which HUD introduced to ensure borrowers have the capacity and willingness to meet their obligations for property taxes and insurance.
If you are still comparing lenders and loan options, a resource like RateChecker can help you see how rates and terms vary across the market before you commit. The counseling session is also a good time to ask about how different payout options might affect your long-term costs, since the counselor can explain the tradeoffs without steering you toward a particular lender or product.
Once the loan closes, your obligations continue. You must live in the home as your primary residence, pay property taxes and insurance on time, and keep the home in good repair. If you fail to meet those obligations, the lender can declare the loan due and payable. Counseling should prepare you for that reality, and a good counselor will make sure you understand that a reverse mortgage is not a free source of money but a loan secured by your home.
For homeowners who want to explore whether a reverse mortgage is the right fit, starting with education and comparison is the smartest approach. Express Mortgage Quotes provides resources and a quote comparison service that connects you with verified lenders, so you can see what is available before you commit to counseling or an application. The counseling requirement exists to protect you, and when you approach it with preparation and an open mind, it becomes one of the most useful steps in the entire process.