VA Mortgage Loans: Zero Down for Veterans in 2026
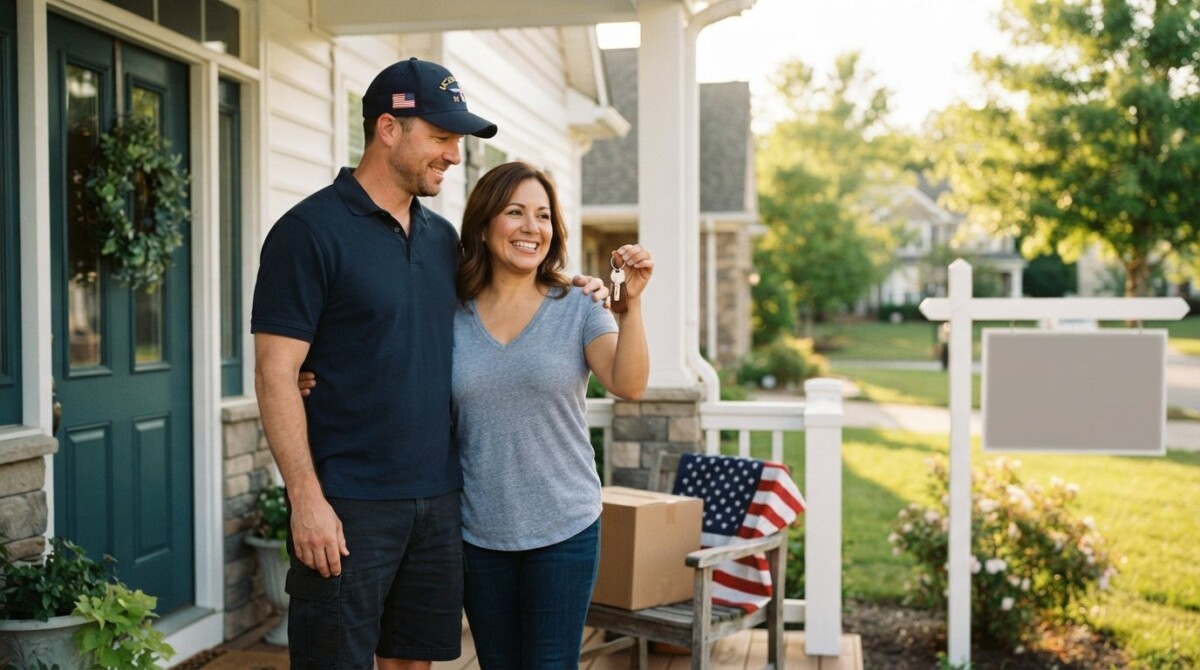
For millions of veterans, active-duty service members, and surviving spouses, a VA mortgage loan is one of the most powerful home financing tools available. Backed by the U.S. Department of Veterans Affairs, these loans routinely deliver the lowest effective costs of any major mortgage program: no down payment, no monthly mortgage insurance, and some of the most forgiving credit guidelines in the industry. Yet many eligible borrowers never use their benefit, often because they assume the process is complicated or believe they will not qualify. The reality is far simpler, and the savings can reach tens of thousands of dollars over the life of a loan.
This guide explains how VA mortgage loans work in 2026, who qualifies, what they cost, and how to compare offers from verified lenders. Whether you are buying your first home near a military base or refinancing an existing loan, understanding the program’s rules helps you capture every dollar your service has earned.
What Is a VA Mortgage Loan and How Does It Work?
A VA mortgage loan is a home loan partially guaranteed by the Department of Veterans Affairs. The VA itself does not lend money. Instead, it promises to reimburse the lender for a portion of the loss if a borrower defaults. That guarantee removes much of the risk lenders normally carry, which is why they can offer VA borrowers terms that are far more generous than those found on conventional or FHA products.
Because the government stands behind a share of the loan, lenders typically require no down payment and no private mortgage insurance (PMI). PMI alone can cost conventional borrowers 0.5% to 1.5% of the loan amount every year, which on a $400,000 loan adds up to $2,000 to $6,000 annually. VA borrowers skip that expense entirely. Lenders also tend to be more flexible on credit scores and debt-to-income ratios, since the guarantee offsets some of their exposure.
The tradeoff is a funding fee, a one-time charge that replaces the insurance premiums other loan types require. Most borrowers pay it at closing, though it can be financed into the loan. The fee varies by down payment size, loan type, and whether the borrower has used the benefit before. Certain veterans with service-connected disabilities are exempt from the fee entirely.
It also helps to see where VA loans sit in the broader lending landscape. VA loans compete directly with conventional mortgage loans, which usually require down payments of 3% to 20%, and with FHA mortgage loans, which allow 3.5% down but charge mortgage insurance premiums for the life of the loan in many cases. For eligible borrowers, the VA option typically wins on total cost.
Who Qualifies for VA Mortgage Loans in 2026?
Eligibility is broader than many people realize. The core requirement is qualifying military service, but the program also extends to surviving spouses and several other groups. In most cases, you will need a Certificate of Eligibility (COE), which lenders can now pull electronically in minutes.
The main groups that qualify include:
- Veterans who served 90 consecutive days of active duty during wartime or 181 days during peacetime
- Active-duty service members currently serving
- National Guard and Reserve members with six years of service or who were called to active duty under federal orders
- Surviving spouses of veterans who died in service or from a service-connected disability (remarriage rules apply)
- Certain members of the Public Health Service, NOAA, and cadets at service academies
Beyond service history, lenders apply their own credit and income standards, but the VA sets a favorable baseline. While there is no official minimum credit score in the VA guidelines, most lenders look for a score of 620 or higher, and some accept 580 with compensating factors. Residual income matters more than raw credit scores in many VA underwriting decisions: the lender checks whether you have enough money left each month after all major obligations, adjusted for family size and region.
There is also no hard debt-to-income cap written into VA rules, though lenders generally want to see DTI at or below 41% unless strong residual income or other factors compensate. This flexibility is one reason VA mortgage loans remain accessible to borrowers who might struggle to qualify elsewhere.
The Financial Advantages: Zero Down, No PMI, and Capped Closing Costs
The headline benefit of a VA mortgage loan is the zero-down structure. For buyers who have served, this removes the single biggest obstacle to homeownership: saving a down payment while also covering rent. On a $350,000 home, a conventional buyer putting 5% down needs $17,500 upfront, while a VA buyer needs nothing for the down payment itself.
Closing costs still apply, but the VA limits which fees a lender can charge. The agency prohibits certain junk fees, requires that borrowers only pay for items that are reasonable and customary, and allows sellers to cover all closing costs plus up to 4% in concessions. In competitive markets, that flexibility can make a VA offer as attractive as a conventional one.
Add the absence of monthly mortgage insurance and the savings compound. A conventional borrower with less than 20% down pays PMI until reaching roughly 20% equity. On a typical loan, that can run $150 to $300 per month for years. VA borrowers keep that money from day one, which improves cash flow and can be redirected toward principal, investments, or emergency savings.
Interest rates on VA loans also tend to run slightly below conventional rates, because the government guarantee reduces lender risk. The combination of a lower rate, no PMI, and no down payment means the total monthly payment on a VA loan is often hundreds of dollars lower than the closest conventional alternative.
VA Loan Limits, Funding Fees, and the 2026 Landscape
Since 2020, VA mortgage loans no longer carry a universal loan limit for borrowers with full entitlement. If you have your full entitlement available, you can borrow as much as a lender is willing to approve without a down payment, provided the property appraises for the purchase price. Borrowers with remaining entitlement or a prior VA loan still in place face county-level limits, which change annually.
The funding fee remains the primary upfront cost. Its size depends on three factors: the type of loan (purchase or refinance), your down payment, and whether this is your first use of the benefit. First-time users with no down payment typically pay 2.15% of the loan amount, while subsequent users pay 3.3%. A 5% down payment drops those figures to 1.5% and 1.65%, respectively. Borrowers with a service-connected disability rating, surviving spouses receiving DIC, and certain other groups pay nothing.
For 2026, high-cost counties continue to see elevated conforming-style limits, while most of the country sits at the baseline. Because these numbers shift each year, it pays to confirm current limits for your county before making an offer. The VA updates its limit tables annually, and lenders can pull the exact figure tied to your entitlement.
It is also worth noting that VA loans are assumable, meaning a future buyer can take over your loan at your existing rate. In a higher-rate environment, that feature can be a significant selling point, and it is one that conventional loans rarely match.
How to Apply for a VA Mortgage Loan: A Step-by-Step Path
The application process mirrors a conventional loan, but with a few VA-specific steps. Moving through them in order keeps the timeline short, often 30 to 45 days from offer to closing.
- Confirm eligibility and obtain your COE. Most lenders can retrieve it electronically through the VA’s system. If not, you can request one online or by mail using your DD-214 or equivalent service records.
- Compare offers from multiple VA-approved lenders. Rates, fees, and service vary widely. Gather at least three Loan Estimates so you can compare on equal terms.
- Complete the full application and provide documentation. Expect to supply pay stubs, W-2s, tax returns, bank statements, and proof of any disability rating if you are claiming a funding fee exemption.
- Schedule the VA appraisal. The VA assigns a licensed appraiser who checks both value and property condition. The appraisal includes a Minimum Property Requirements review, which flags safety and structural issues that must be corrected before closing.
- Clear underwriting and close. Once conditions are satisfied, the lender issues a Clear to Close, and you sign final documents. The funding fee, if applicable, appears on the Closing Disclosure.
One step that deserves extra attention is the appraisal. VA appraisals are stricter than conventional ones in some respects, particularly around health and safety items like peeling paint, missing handrails, or a non-functional HVAC system. Sellers sometimes need to make repairs before closing. Knowing this upfront helps you negotiate repair credits or set expectations with the seller.
If you are weighing a larger purchase in a high-cost market, jumbo mortgage loans may come into the conversation, but many veterans find that their full VA entitlement covers the purchase without needing a jumbo at all. Running the numbers on both sides is the surest way to know.
VA Loans vs. Other Mortgage Programs: A Quick Comparison
Choosing between loan types comes down to eligibility and total cost. VA loans are usually the cheapest option for those who qualify, but it helps to see the differences side by side.
- Down payment: VA 0%, FHA 3.5%, conventional 3% to 20%
- Mortgage insurance: VA none, FHA upfront and annual premiums, conventional PMI until 20% equity
- Credit flexibility: VA lenders often accept lower scores and higher DTIs, FHA is moderate, conventional is strictest
- Funding fee or premiums: VA charges a one-time funding fee (exemptions apply), FHA charges an upfront premium plus annual premiums
- Property standards: VA appraisals are stricter on safety and condition than conventional appraisals
The comparison makes the case plainly. For a borrower with entitlement, a VA loan typically delivers the lowest monthly payment and the lowest cash needed at closing. FHA can make sense for buyers without military service, and conventional loans offer more flexibility on property type and loan size in some scenarios.
It also pays to think about long-term plans. If you expect to sell within a few years, the funding fee may not fully amortize through monthly savings, though the no-PMI advantage usually covers it quickly. If you plan to stay put, the cumulative savings from no PMI and a lower rate often reach five figures.
Common Mistakes That Cost VA Borrowers Money
Even with a strong program, small missteps can erode the advantage. One frequent error is accepting the first lender’s offer without shopping. VA loan rates and fees vary by half a percentage point or more between lenders, which translates to thousands of dollars over the loan term. The VA’s own guidance encourages borrowers to compare at least three offers.
Another mistake is overlooking the funding fee exemption. Veterans with any service-connected disability rating, even 0% in some cases, along with certain surviving spouses, can avoid the fee entirely. It is not automatic: you must document your status with the lender. Missing this step on a $400,000 loan could mean paying more than $8,000 unnecessarily.
Borrowers also sometimes assume they must use their VA benefit only once. In reality, the entitlement is reusable. You can restore it by paying off the loan, or in some cases carry two VA loans at once if you have remaining entitlement. Understanding how entitlement works helps you plan for a move or a second property without losing the benefit.
Finally, some buyers skip the pre-approval stage and start touring homes before knowing their true budget. A VA pre-approval letter signals to sellers that your financing is credible and gives you a firm price ceiling. It also surfaces any credit or documentation issues early, when there is still time to resolve them.
Where to Compare VA Mortgage Loans and Get Personalized Quotes
Because VA loans are offered by thousands of lenders, the difference between an average deal and an excellent one often comes down to comparison. Express Mortgage Quotes is built for exactly that task. The platform is an educational and connection service, not a direct lender, which means you can review loan options and request quotes from verified lenders without pressure from a single institution.
Start by using the site’s mortgage calculator to estimate payments under different rate and term scenarios. Then submit a short form to receive tailored quotes for your situation, whether you are purchasing, refinancing an existing VA loan through the Interest Rate Reduction Refinance Loan (IRRRL) program, or exploring a cash-out refinance to access home equity. The IRRRL, in particular, is a streamlined option that typically requires no appraisal and minimal documentation, making it one of the fastest ways to lower your rate.
For veterans aged 62 and older, the site also covers reverse mortgage options, which can complement a broader retirement income plan. And for anyone still deciding between programs, the resource library offers side-by-side guides on FHA, conventional, and jumbo products so you can see how VA mortgage loans stack up in your specific market.
Your service earned this benefit. Taking an hour to compare offers and confirm your eligibility can save you tens of thousands of dollars over the life of your loan, and it puts you in a stronger position to buy the home you want with the terms you deserve.
About Daniel Smith
Recent Posts
Home Loan Comparison Online: A Smarter Way to Save
Home loan comparison online lets you line up multiple offers in minutes and spot hidden fees before you commit. See how to compare and save.
Low Interest Mortgage Rates: How to Qualify and Save
Low interest mortgage rates start with credit prep and lender comparison. See how to qualify and cut your monthly payment by hundreds.
VA Mortgage Loans: Zero Down for Veterans in 2026
VA mortgage loans offer zero down payment and no monthly mortgage insurance. See 2026 limits, funding fees, and how to compare lender quotes.
Reverse Mortgage Rates in 2026: A Homeowner’s Guide
Reverse mortgage rates affect how much equity you can access and how fast your loan balance grows. Compare rates to protect your retirement.
Find The Best Rates