HELOC Draw Period vs Repayment Period: What Changes
Understand how a HELOC draw period versus repayment period works, and learn budgeting tactics to avoid payment shock when your draw period ends.
By Grace Parker
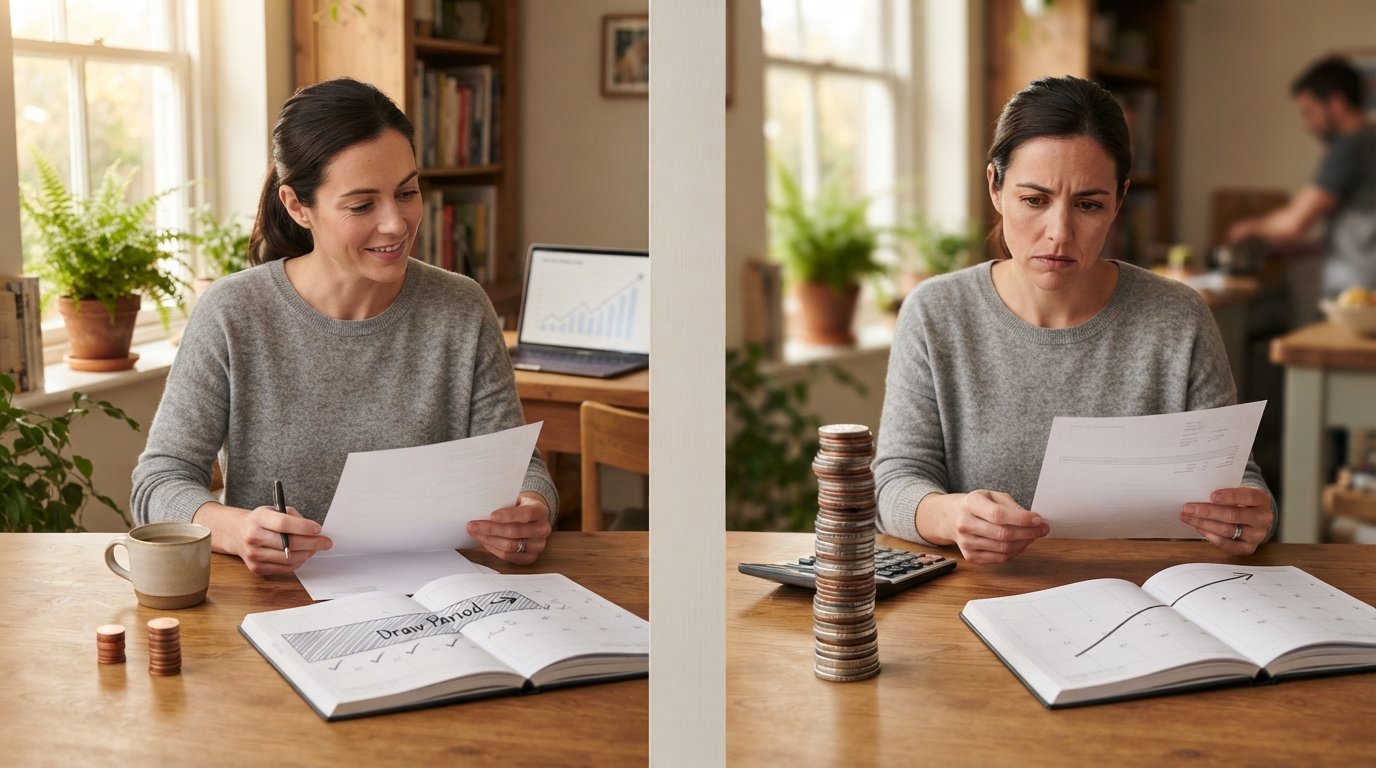
When you open a home equity line of credit, the lender typically splits the loan term into two distinct phases: the draw period and the repayment period. During the draw period, you can borrow money as needed, up to your credit limit, and you often have the option to make interest-only payments. Once the draw period ends, the repayment period begins, and your monthly payments can jump significantly because you must start paying down the principal as well as the interest. Understanding the difference between these two phases is critical for budgeting and avoiding payment shock.
What Is a HELOC Draw Period?
The draw period is the initial phase of a home equity line of credit, typically lasting 5 to 10 years. During this time, you can access funds up to your credit limit, much like a credit card. You can draw money as needed, repay it, and draw again, as long as you stay within your limit. Many lenders offer interest-only payments during the draw period, which keeps monthly payments low but does not reduce the principal balance. Some lenders require principal and interest payments during the draw period, but this is less common.
For example, if you have a $100,000 HELOC with a 10-year draw period and a 5% interest rate, an interest-only payment would be approximately $417 per month. If you borrowed the full $100,000 and made only interest-only payments, you would still owe $100,000 at the end of the draw period. This low payment can be attractive, but it can also create a false sense of affordability. It is important to plan for the higher payments that will come later.
During the draw period, you may also have the option to convert a portion of your balance to a fixed-rate loan, often called a fixed-rate advance. This can provide predictable payments for that portion, but it reduces your available credit. Additionally, some HELOCs have annual fees or inactivity fees, so it is wise to review your loan agreement carefully.
What Is a HELOC Repayment Period?
After the draw period ends, the repayment period begins. This phase typically lasts 10 to 20 years, during which you can no longer draw funds and must repay the outstanding balance plus interest. Your monthly payments will now include both principal and interest, which means they will be higher than the interest-only payments you may have been making. The exact payment amount depends on the remaining balance, the interest rate, and the length of the repayment period.
For instance, if you still owe $100,000 at the start of a 15-year repayment period with a 5% interest rate, your monthly payment would be approximately $791 for principal and interest. That is nearly double the interest-only payment. If the interest rate has risen to 8%, the payment would be about $956. This increase can strain a budget if you have not prepared for it.
Some lenders may offer a balloon payment at the end of the repayment period, meaning a large lump sum is due. This is less common with HELOCs but possible. It is essential to understand the terms of your specific loan to avoid surprises.
Key Differences Between Draw Period and Repayment Period
The fundamental difference between the draw period and the repayment period is how you interact with the money and how your payments are structured. During the draw period, you have flexibility to borrow and repay repeatedly, and payments may be interest-only. During the repayment period, you can no longer borrow, and payments include principal and interest, amortizing the loan over the remaining term.
Here is a quick comparison of the two phases:
- Access to funds: Draw period allows borrowing; repayment period does not.
- Payment structure: Draw period often offers interest-only payments; repayment period requires principal and interest.
- Impact on balance: Draw period may not reduce principal; repayment period gradually pays down the balance.
- Duration: Draw period typically 5-10 years; repayment period typically 10-20 years.
Understanding these differences helps you plan for the transition. For example, if you know your draw period ends in five years, you can start setting aside extra funds now to cover the higher payments later or to pay down the principal before the repayment period begins.
Payment Shock: What to Expect When the Draw Period Ends
Payment shock is the sudden increase in your monthly payment when the draw period ends and the repayment period begins. This can be substantial, especially if you have a large outstanding balance and the interest rate has risen. For example, if you borrowed $50,000 during the draw period and made interest-only payments at 4%, your payment might have been about $167 per month. When the repayment period starts with a 15-year term at 6%, your payment could jump to about $422 per month. That is a 150% increase.
To illustrate further, consider a homeowner who used a HELOC to consolidate $80,000 of debt. During a 10-year draw period with interest-only payments at 5%, the monthly payment is $333. When the draw period ends and a 20-year repayment period begins at 6%, the payment becomes $573. If rates rise to 8%, the payment becomes $669. These increases can be challenging for homeowners on fixed incomes or tight budgets.
Payment shock can be mitigated by planning ahead. Some lenders allow you to make principal payments during the draw period, which reduces the balance and lowers future payments. Others may offer a modification or extension, but these are not guaranteed. The best strategy is to anticipate the change and budget accordingly.
How to Prepare for the Repayment Period
Preparing for the repayment period should start well before the draw period ends. Here are some strategies to consider:
- Make principal payments during the draw period: Even small extra payments can reduce your balance and lower your future monthly payments. For example, paying an extra $100 per month toward principal on a $50,000 balance at 5% could save you thousands in interest and reduce your repayment period.
- Create a budget that accounts for higher payments: Estimate what your payment will be during the repayment period using a mortgage calculator. Then adjust your budget to set aside the difference now. This can help you avoid financial strain later.
- Explore refinancing options: If you are concerned about payment shock, consider refinancing your HELOC into a fixed-rate home equity loan or a cash-out refinance before the draw period ends. This can provide predictable payments and potentially lower interest rates. However, refinancing comes with closing costs and fees, so compare offers from multiple lenders.
- Consider a HELOC modification: Some lenders may allow you to extend the draw period or modify the terms, but this is not common and may involve fees. It is worth asking your lender if you anticipate difficulty.
- Set up automatic savings: Treat the difference between your current payment and your future payment as a mandatory savings contribution. For example, if your payment will increase by $300, set up an automatic transfer of $300 to a savings account each month. When the repayment period begins, you will have a cushion.
These steps can help you transition smoothly and avoid the stress of unexpected payment increases. For those considering a reverse mortgage as an alternative for accessing home equity in retirement, our guide on Home Equity Conversion Mortgage: A Guide for Seniors explains how that product differs and when it might be appropriate.
Refinancing or Restructuring Before the Draw Period Ends
If you are worried about the end of your draw period, you have several options to restructure your debt. Refinancing your HELOC into a fixed-rate home equity loan can lock in a predictable payment and interest rate. This is particularly appealing if interest rates are expected to rise. Alternatively, you could refinance your primary mortgage with a cash-out refinance to pay off the HELOC and potentially get a lower rate. However, this replaces your existing mortgage with a new one and may extend your repayment term.
Another option is to convert a portion of your HELOC balance to a fixed-rate advance if your lender offers it. This can provide stability for part of your debt while keeping the remaining line flexible. It is important to compare the costs of any refinancing option, including closing costs, application fees, and potential prepayment penalties. Use an online mortgage calculator to estimate monthly payments and total interest savings.
When considering refinancing, it is wise to shop around and compare offers from multiple lenders. Express Mortgage Quotes can connect you with verified lenders who offer home equity products and refinancing options. You can submit a form-based inquiry to receive personalized quotes without obligation. Remember that featured lenders may pay advertising fees, and a listing does not imply endorsement. Always confirm rates and terms directly with a licensed lender.
Budgeting Tactics for the Transition
Budgeting for the repayment period requires foresight and discipline. Start by calculating your future payment using the current interest rate and remaining balance. Then, compare it to your current payment to determine the difference. Incorporate that difference into your monthly budget as a line item for savings or debt reduction. For example, if your payment will increase by $400, allocate $400 toward principal payments during the draw period. This not only reduces your balance but also gets you accustomed to the higher payment.
Additionally, consider building an emergency fund to cover unexpected expenses. If you have been using your HELOC as a safety net, you will need an alternative once the draw period ends. Aim to save three to six months of living expenses in a liquid account. This can prevent you from relying on high-interest credit cards if an emergency arises.
Another tactic is to automate your finances. Set up automatic payments for your HELOC and automatic transfers to savings. This reduces the risk of missed payments and helps you stay on track. Review your budget regularly and adjust as needed. If you anticipate a significant payment increase, you may need to cut discretionary spending or increase income. For those who are 62 or older, a reverse mortgage might provide a way to access home equity without monthly payments, but it is a complex decision that requires careful consideration. For educational resources on mortgage products and payment calculators, you can visit MortgageDirectory, which offers plain-language guides and a payment calculator.
Common Questions About HELOC Draw Periods and Repayment Periods
Can I pay down principal during the draw period?
Yes, most HELOCs allow you to make principal payments during the draw period. In fact, doing so is highly recommended to reduce your balance and lower future payments. Some lenders may require a minimum payment that includes principal, but even if they do not, you can always pay more.
What happens if I cannot pay when the repayment period starts?
If you cannot afford the higher payments, contact your lender immediately. They may offer options such as a loan modification, extension, or repayment plan. Ignoring the problem can lead to late fees, damaged credit, and eventually foreclosure. It is better to address it early.
Can I refinance my HELOC during the draw period?
Yes, you can refinance a HELOC at any time, but it may be more beneficial to do so before the draw period ends to avoid payment shock. Refinancing could involve a new home equity loan, a cash-out refinance, or a new HELOC with better terms. Compare offers carefully.
Is the interest on a HELOC tax-deductible?
Interest on a HELOC may be tax-deductible if the funds are used to buy, build, or substantially improve the home that secures the loan. Tax laws can change, so consult a tax advisor for guidance specific to your situation.
Understanding the home equity line of credit draw period versus repayment period is essential for responsible borrowing. By planning ahead, making principal payments, and exploring refinancing options, you can manage the transition smoothly and avoid financial stress. For personalized guidance and to compare quotes from verified lenders, consider using Express Mortgage Quotes to explore your options.